
FirstService Residential Expands Its Portfolio in South Carolina, Welcoming Sea Crest Oceanfront Resort
Source: PR Newswire
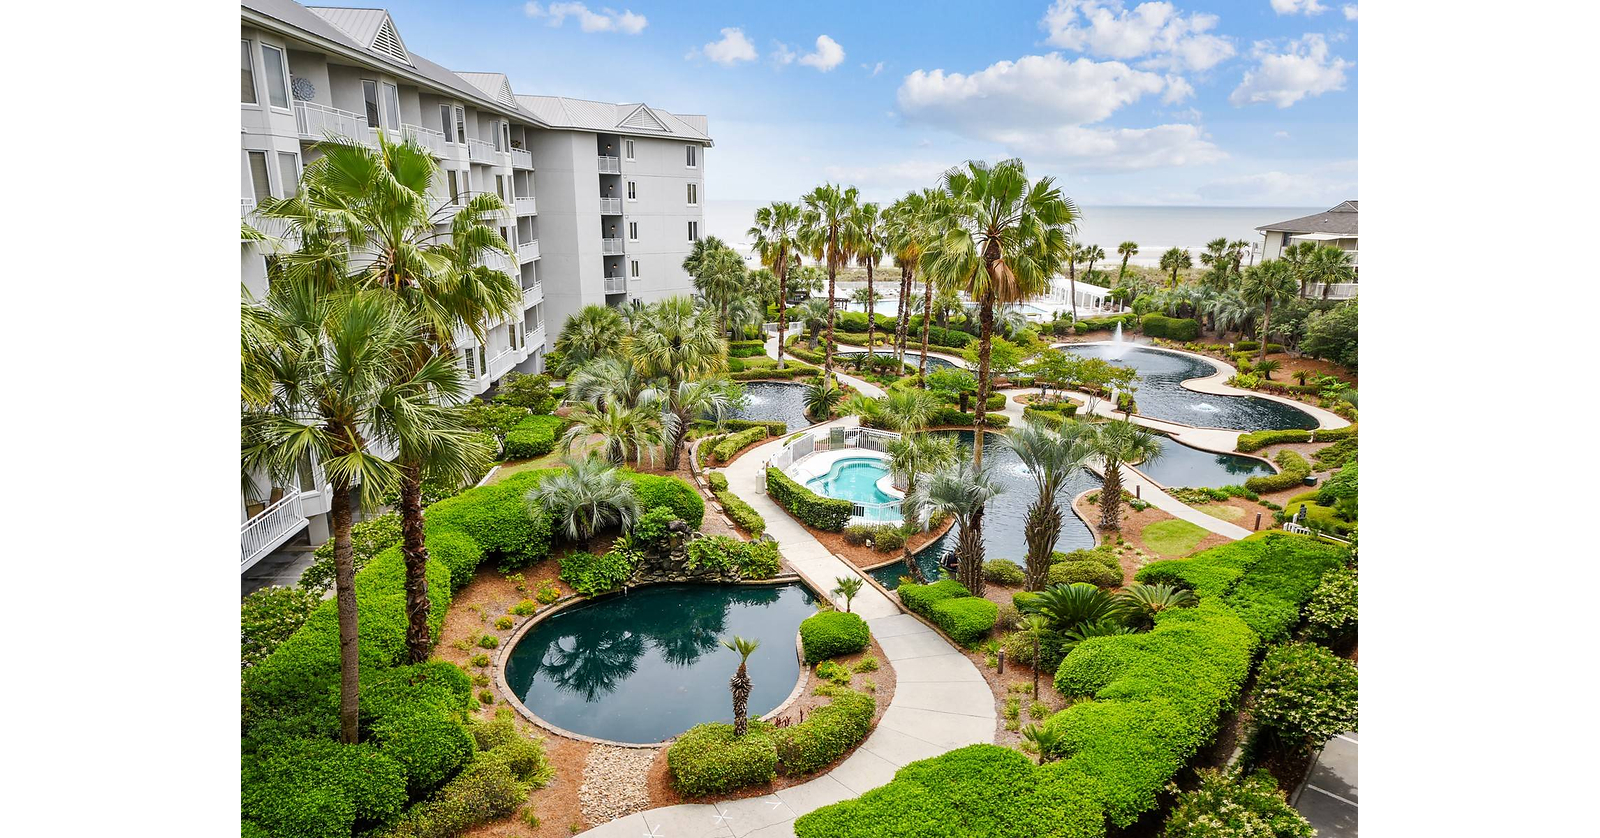
FirstService Residential, a subsidiary of FirstService Corp. (NASDAQ/TSX: FSV), was selected to provide full-service property management for the Sea Crest Oceanfront Resort in Hilton Head Island, South Carolina. The mandate followed the firm's work with the community board on a large lagoon-repair project and modestly expands its residential management portfolio, though no contract value or financial impact was disclosed.
Analysis
This is immaterial to FSV earnings in isolation, but it reinforces the higher-quality aspect of the Residential segment: recurring, contract-based management revenue with opportunities to attach energy, financial, restoration and project-management services. The relevant economic signal is not the unit win itself; it is whether regional onboarding can convert capital-project work into durable management mandates, improving client acquisition economics and raising revenue per community over the following 12-24 months.
For FSV, the near-term valuation driver remains Residential organic growth and margin conversion rather than incremental contract announcements. A broader recovery in coastal condominium maintenance, insurance remediation and deferred-capex spending could lift ancillary-service penetration, but also carries execution risk: large repair projects can create working-capital demands, reputational exposure and volatile pass-through revenue that does not translate proportionately into EBITDA.
Consensus may underappreciate FSV's defensive mix if housing transaction activity stays subdued. Community-management revenues are linked more to the installed base of associations and property complexity than home-sale volumes; this supports relative earnings durability versus transaction-sensitive housing-service peers. Conversely, a weak HOA affordability backdrop—insurance premium inflation, special assessments and delinquent dues—could pressure contract retention and delay discretionary amenity or repair work, limiting cross-sell upside.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No event-driven trade: treat this as a low-signal operational datapoint rather than a catalyst for FSV; avoid adding solely on the announcement.
- Maintain or initiate a 6-12 month relative long FSV versus RE/MAX (RMAX) or Compass (COMP) if residential transaction volumes remain weak: FSV's recurring management exposure should produce more resilient organic growth and EBITDA. Reassess if FSV Residential organic growth decelerates below low-single digits for two consecutive quarters.
- Monitor the next two earnings releases for Residential segment organic growth, adjusted EBITDA margin and disclosure on ancillary-service penetration. Upgrade conviction only if management demonstrates accelerating organic growth without margin dilution from project-related labor or onboarding costs.
- Key downside trigger: reduce FSV exposure on evidence of HOA affordability stress—rising client attrition, elevated receivables/delinquency, or management commentary that insurance and assessment burdens are deferring maintenance projects. These would challenge the assumed resilience premium in FSV's multiple.
More News
- Here's what happens to the economy when Treasury yields soar like they are now
- SoftBank shares jump over 7% after $11.1 billion bond issuance to fund OpenAI bet
- AirAsia’s Hunt for Cheaper Debt Won’t Be Easy With Oil Near $100
- Why is Kenya turning against Tata Chemicals in Magadi?
- Trump-Xi meeting: Why China's self-sufficiency changes the calculus
- Meta is having a ChatGPT moment with Muse. What is it and what makes it so special