
Hainan Airlines Retains SKYTRAX Five-Star Rating for 15th Consecutive Year, and Ranks among the Skytrax World's Best Airlines Top 10 List
Source: PR Newswire
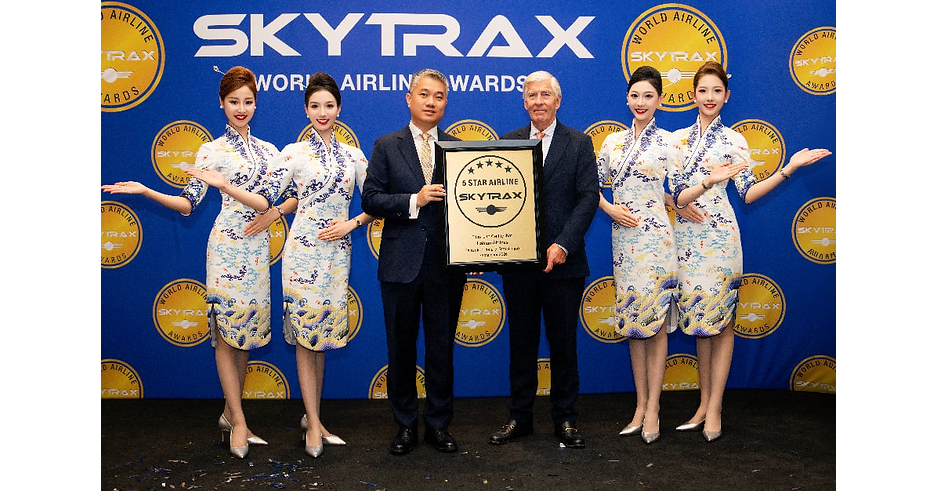
Hainan Airlines retained its Skytrax Five-Star Airline rating for a 15th consecutive year, ranked in the global top 10, and placed fourth for World's Best Cabin Crew. The carrier is expanding its international and regional network to more than 70 resumed, launched or planned routes, while increasing domestic connection-service coverage from 19 to 36 departure points and overseas points to 41. The recognition and network expansion support its premium-service positioning, though the announcement provides no financial results or earnings outlook.
Analysis
The direct listed-equity read-through is limited: Hainan Airlines is not a clean public proxy, and the announcement does not establish incremental revenue, load-factor, or yield data. For IHG, the partnership is better viewed as premium-brand marketing and loyalty acquisition rather than a material earnings driver; airline lounge and onboard visibility can support inbound-China awareness for HUALUXE and InterContinental, but is immaterial against IHG's global fee base.
The more relevant second-order issue is competitive intensity in China outbound premium travel. If Hainan translates service recognition into higher corporate-travel share, the pressure falls on China Eastern (600115.SS), China Southern (600029.SS), and Air China (601111.SS) to match soft-product and lounge investment, raising unit costs before pricing power is proven. International carriers with China exposure—Cathay Pacific (0293.HK) and Singapore Airlines (C6L.SI)—could face incremental competition on connecting premium traffic, though capacity discipline and bilateral route rights will matter far more than awards.
Over the next 1-3 months, this is unlikely to move IHG absent evidence that the airline partnership converts into booked room nights, loyalty enrollments, or hotel-management contract wins in Hainan/Chinese gateway cities. Over 6-18 months, the potentially investable signal is whether recovering Chinese outbound traffic shifts toward premium cabins and branded hotels; that would favor IHG's asset-light Greater China pipeline more than airline operators burdened by fleet, fuel, and pricing volatility. The thesis is falsified if China outbound capacity expands faster than premium demand, compressing airfares and hotel ADR despite higher passenger volumes.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No standalone trade in IHG on this announcement; maintain a watch alert for Greater China RevPAR acceleration, net unit growth, and disclosed loyalty/partnership conversion in the next two earnings cycles.
- If China outbound premium-demand indicators improve for two consecutive months, consider a 6-12 month long IHG versus short 600115.SS basket: IHG captures fee-based hotel demand with limited capital intensity, while airline competition risks diluting yield gains through service and capacity spending.
- Monitor Cathay Pacific (0293.HK) premium-cabin yield and China-route capacity through the next reporting period. A sustained yield decline alongside Hainan international expansion would support a tactical underweight, but do not initiate solely on service-award headlines.
- For IHG, invalidate any China-demand bullish positioning if Greater China RevPAR turns negative year-on-year or management cuts net system growth guidance; those data points matter materially more than partnership publicity.
More News
- Hainan Airlines Retains SKYTRAX Five-Star Rating for 15th Consecutive Year, and Ranks among the Skytrax World's Best Airlines Top 10 List
- AI safety efforts will require more compute, not less: experts
- Buffett Son Takes Chair as Berkshire Transition Ends
- SpaceX Nasdaq 100 weight to jump to 2.82% in quarterly rebalance -Bloomberg
- What does the EU have that the U.S. does not?
- Oracle Has Committed Hundreds of Billions to AI Data Centers. These 2 Industrial Stocks Will Power Them.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Reading Conviction in the Tape: What Level 3 Order Book Data Really Tells Discretionary PMs
- AI Tools for CFA Charterholders: An Evidence Standard