
Google’s Pixel 11 Pro Can’t Compete With Superior Chinese Flagship Phones
Source: Bloomberg
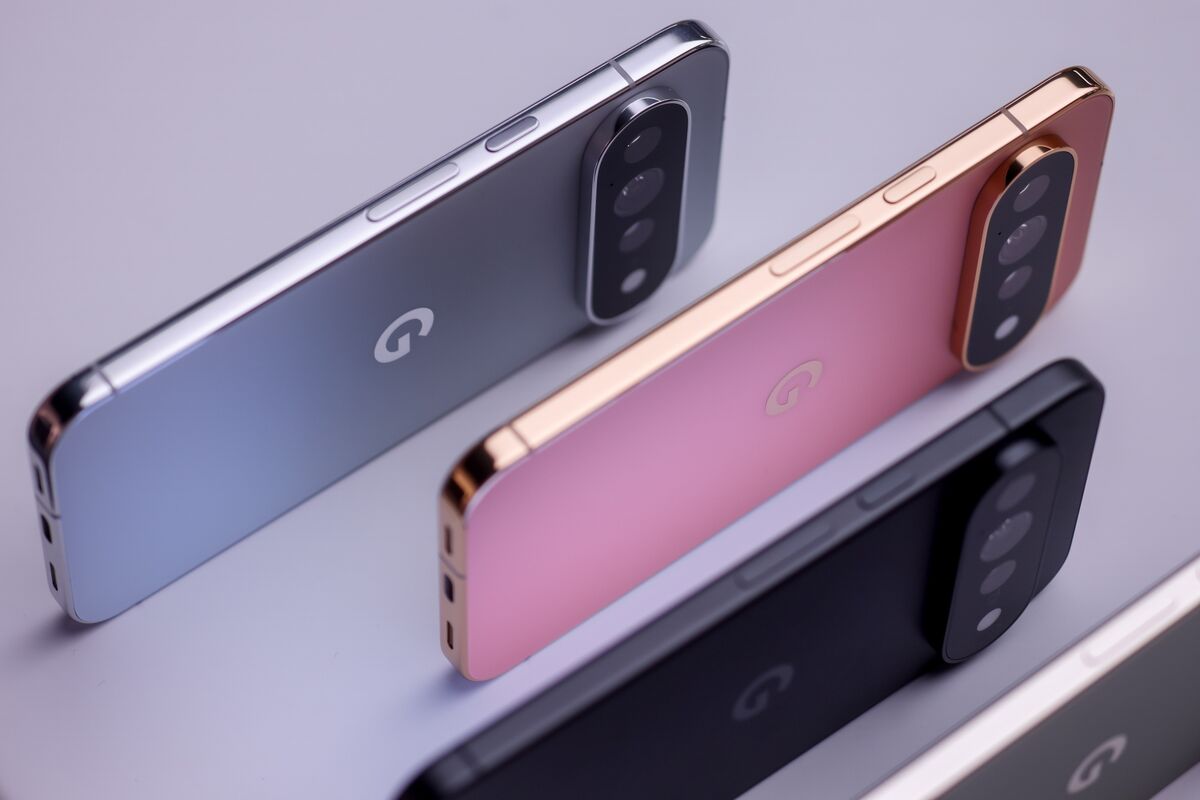
The article compares recent Google Pixel smartphone changes with top Chinese phones, arguing the Pixel 11 Pro now looks “prettier” but is less distinctive after a year using Vivo. It also notes Apple’s upcoming product cadence: upgraded Mac mini and Mac Studio desktops already unveiled, with new iPhones expected next. Overall, it’s more of a product/positioning take than a quantified financial catalyst, so likely limited near-term market impact.
Analysis
The investable takeaway is not the handset itself; it is that Google’s hardware is losing its role as a premium signal for the Android stack. When the reference device stops looking meaningfully better than the best Chinese flagships, Google loses a cheap but useful marketing lever for AI, camera, and ecosystem stickiness. That matters more for mid-cycle brand perception than for near-term financials, because Pixel is still too small to move consolidated numbers in a meaningful way.
The first-order loser is GOOGL’s hardware narrative; the second-order risk is that premium Android mindshare drifts further toward Chinese OEMs that can ship faster design iteration and more aggressive specs. Over 1-3 months, this is mostly a sentiment and launch-cycle issue rather than an earnings issue, but it can still weigh on the stock if management is forced to defend a consumer business that lacks differentiation. Over 6-18 months, continued hardware commoditization would push Google toward being a pure software/services beneficiary while reducing the strategic value of owning the device endpoint.
The contrarian view is that the market may be overpricing the importance of Pixel quality to the equity story. If hardware differentiation is fading, Google may actually be better off not subsidizing an arms race it cannot win, which would cap the downside from product disappointment. The real falsifier is evidence that weak Pixel reception spills into broader ecosystem metrics—engagement, AI feature adoption, or partner confidence—rather than just another poor-review cycle.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
-0.05
Ticker Sentiment
Key Decisions for Investors
- Do not short GOOGL solely on Pixel aesthetics; the hardware franchise is too small to drive the core valuation. If the stock sells off >2% on launch-week commentary without any read-through to search/cloud, use that weakness to add a small long in the next 1-2 sessions, with a 3-5% rebound target over 2-4 weeks.
- Relative-value trade: long AAPL / short GOOGL for 1-3 months. Thesis: premium smartphone differentiation still accrues to Apple, while Google’s device line is increasingly undifferentiated. Exit if Pixel preorder/channel checks surprise positively or if AAPL’s next iPhone cycle stumbles.
- Watch-list only: buy a short-dated GOOGL put spread into the next earnings call only if independent channel data shows launch underperformance. The catalyst is sentiment, not revenue; keep risk defined and size small.
- If you want exposure to the competitive dynamic, prefer Chinese Android OEM beneficiaries via local proxies rather than GOOGL shorting; the better handset economics are likely captured by the faster-moving OEMs, not by Google itself.
More News
- Global PC shipments crater 20% as rising prices hammer demand
- Cramer: Investors selling Apple on latest iPhone 18 report are 'stupid as plywood'
- Sequoia-backed Nuvacore seeks $2.5bn valuation in funding round
- Stocks making the biggest moves midday: T-Mobile, Verizon, AT&T, Crown Castle, Teva & more
- Two characters open up a world of typosquatting opportunities in Chromium browsers
- Gen Z is rejecting millennial beige and embracing the colorful ‘dopamine decor’ trend. Designers say it’s a coping mechanism