
FirstService Residential Expands in Myrtle Beach, Welcoming Holiday Sands South Ocean Front Homeowners Association to Its Premier Portfolio
Source: PR Newswire
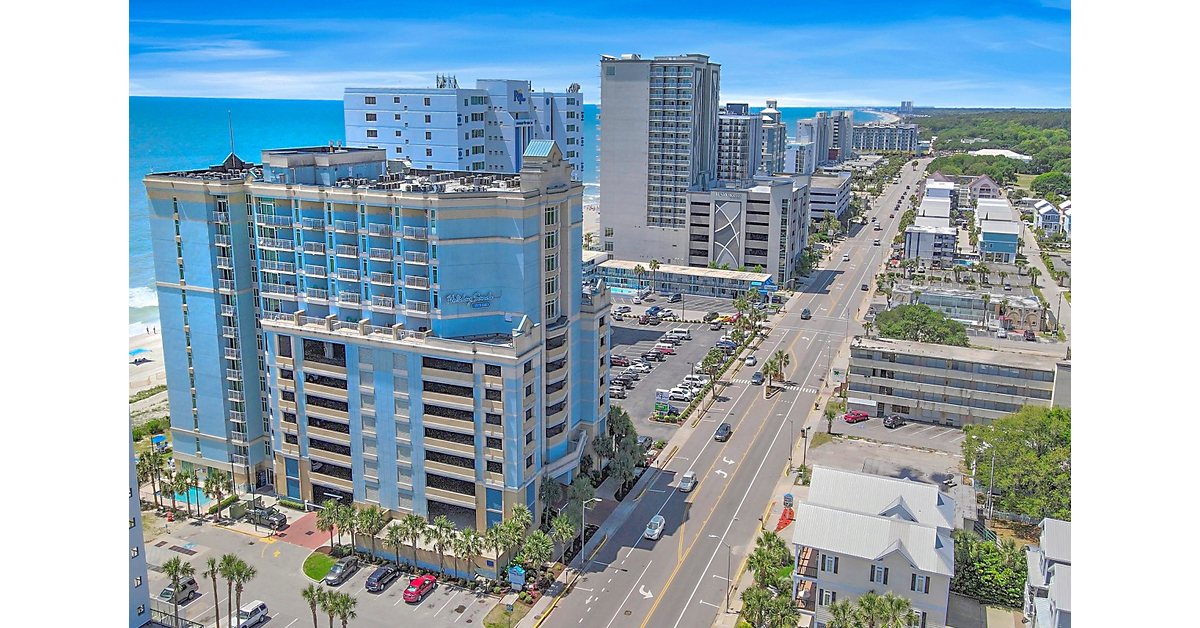
FirstService Residential, a subsidiary of FirstService Corp. (NASDAQ/TSX: FSV), was selected to provide full-service property management for Holiday Sands South Ocean Front Homeowners Association in Myrtle Beach, South Carolina. The contract expands FirstService Residential's managed-community footprint and provides the oceanfront resort property access to its high-rise management, financial, energy, and operational support services. No contract value, revenue contribution, or financial outlook impact was disclosed.
Analysis
This is not a fundamental earnings catalyst for FSV: a single HOA mandate is likely immaterial relative to Residential’s existing base, and the release provides no contract value, unit count, fee structure, or margin contribution. The relevant signal is qualitative—high-amenity coastal communities create recurring opportunities for ancillary energy, insurance/financial, project-management and amenity-service revenue—but those attach rates, rather than management-fee wins, determine whether local scale translates into incremental EBITDA.
Near term, the announcement should not alter consensus estimates or justify a directional move. Over 1-3 months, monitor whether FSV reports sustained net new-community growth and improved Residential organic revenue, particularly in Sun Belt/coastal markets where insurance, deferred maintenance and reserve-funding pressures can raise management complexity and pricing power. A broader conversion cycle from smaller regional managers could favor FSV, while elevated HOA dues, coastal insurance costs and weak resort-property transaction volumes could increase board cost sensitivity and retention risk.
The non-obvious risk is reputational asymmetry: high-rise oceanfront communities have concentrated exposure to storm losses, building-envelope remediation and special assessments. Management contracts are asset-light, but a service failure around post-storm recovery can produce churn and constrain pricing across an entire local market. Conversely, repeated wins in complex associations would reinforce FSV’s scale advantage versus privately held local managers, with limited direct public-market read-through to listed real-estate owners.
Contrarian view: investors may over-credit a steady stream of contract announcements as evidence of accelerating growth. Until management discloses organic growth, retention, net unit additions and ancillary penetration, these releases are better treated as a pipeline/brand datapoint than as an earnings signal. The thesis is falsified positively by an upward revision to Residential organic-growth or segment-margin guidance; negatively by deceleration in retention, pricing, or hurricane-related client losses.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this announcement; avoid treating it as an FSV earnings catalyst given absent contract economics and low indicated impact.
- Maintain FSV on a 1-3 month watchlist for Residential organic-growth, retention and margin disclosures at the next earnings release. Upgrade only if management demonstrates broad-based net additions plus ancillary-service attachment sufficient to support an upward EBITDA revision.
- For existing FSV exposure, use post-earnings guidance as the decision point: add on evidence of Residential organic growth accelerating without margin dilution; reduce if growth is acquired-led, retention weakens, or coastal insurance/remediation costs pressure client budgets.
- Monitor hurricane activity and coastal-property insurance renewals through the next 6-12 months as an asymmetric operational-risk indicator for FSV’s Southeast residential portfolio; deterioration would be a reason to hedge sector exposure rather than short FSV solely on this release.
More News
- Australia’s central bank chief warns inflation risks materialising
- This AI-picked stock jumps 18% on Amazon’s $8 billion power deal
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”
- Jensen Huang says Nvidia will sell twice as many chips next year
- Generac shares surge on big Amazon deal. Wall Street thinks the generator stock has more to go
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?
- What Is a Financial Ontology?