
DentScribe White Paper Reveals Why Diagnosed Treatment Goes Unscheduled
Source: PR Newswire
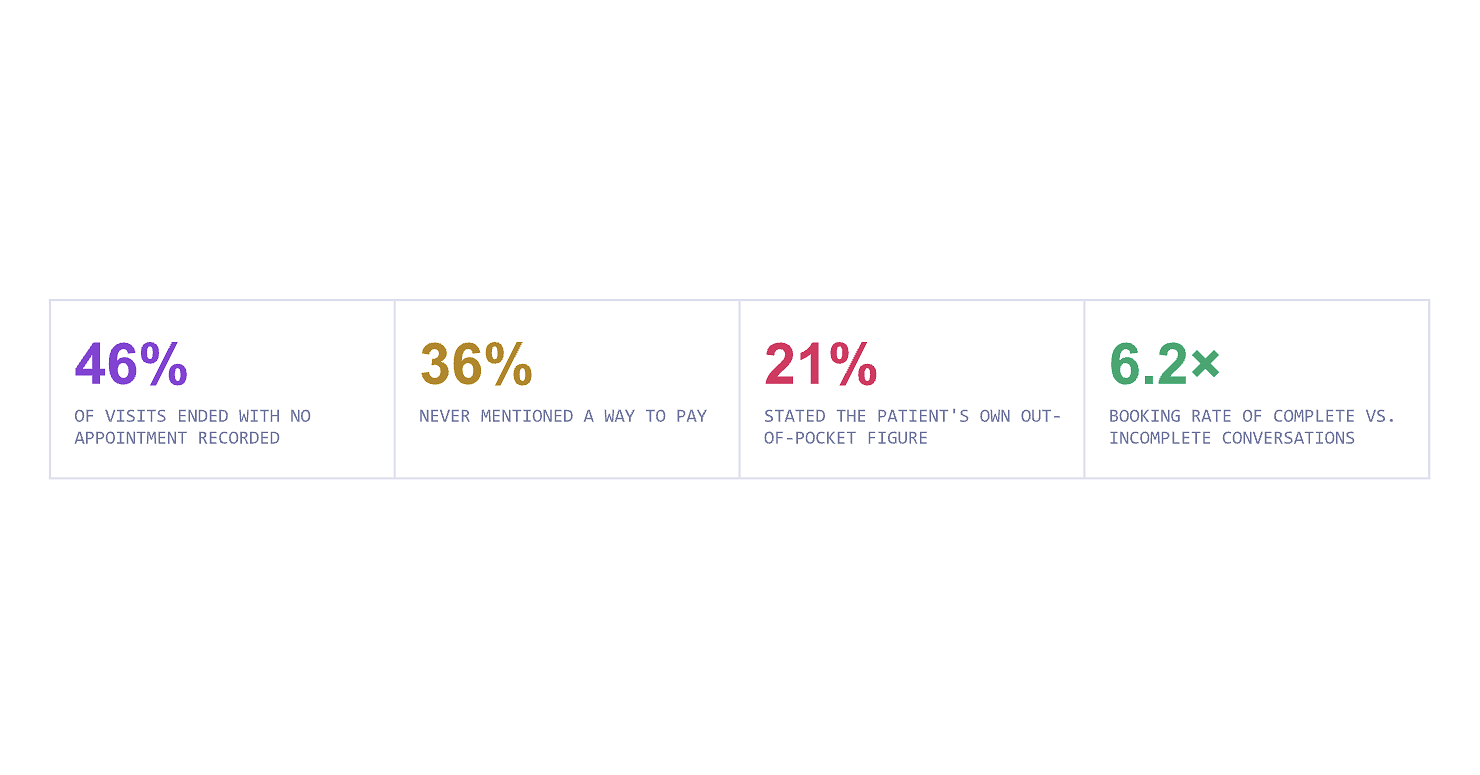
DentScribe (AI dental documentation) released a white paper claiming the main production leak occurs in the post-appointment “treatment coordinator” conversation: 46% of visits ended with no appointment recorded and only 21% gave patients their own out-of-pocket figure. The company reports complete conversations booked at 6.2x the rate of incomplete ones, with $65,696 in quoted treatment remaining unresolved in the sample, and 98 office commitments with no owner or due date. The release is positioned as an operational/AI enablement tool for DSOs to improve case acceptance via structured Treatment Coordinator Notes, but it does not present pricing or financial guidance.
Analysis
This is less an AI model story than a workflow-instrumentation story: the monetizable edge is turning a loosely managed human conversation into a measurable sales funnel. If the process signal is real, the economic winner is the operator that can standardize follow-up and pricing clarity across locations, which favors larger DSOs and platform vendors that can enforce discipline at scale. The public-equity read-through is modest but directionally positive for dental ecosystem names with exposure to procedure volume and consumables, especially HSIC, NVST, XRAY, and potentially ALGN if higher case completion translates into more elective starts.
Near term, the market should discount most of this as vendor marketing until there is third-party evidence of lift after implementation, not just a white paper. The main falsifier is a pilot that improves note quality but does not move booked-case conversion after 30-90 days, which would imply the bottleneck is not documentation but staffing, trust, or patient affordability. A second risk is adoption friction: if structured notes add admin burden or create compliance/privacy headaches around payment conversations, usage could stall even if the ROI math looks attractive.
The contrarian point is that the consensus may underappreciate how much value in healthcare sits in management accountability rather than diagnosis. If the software reliably forces owner assignment, follow-up timing, and objection tagging, it can lift collections without adding chairs or ads; that is a quiet margin story, not a flashy AI story. But absent hard conversion data, this remains a private-market operational tool, not a clean public-market catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate public-equity trade; treat this as a watch item until a DSO or multi-site practice publishes pre/post conversion data showing booked-case lift persists beyond 30-60 days.
- Add HSIC, NVST, XRAY, and ALGN to the dental-automation watchlist; the first confirmation signal would be management commentary on improved case acceptance, mix, or same-store procedure growth tied to workflow software adoption.
- Conditional long HSIC on a pullback only if a larger DSO or PMS integration announcement shows measurable revenue-per-visit improvement; thesis target is modest multiple expansion from improved dental ecosystem growth, with invalidation if dental segment growth stays flat through the next print.
- If evidence emerges that structured TC notes are mainly improving collections rather than procedure volume, prefer HSIC over ALGN/NVST because distribution and consumables should capture the broader cash-collection benefit first.
- Set a 1-3 month alert for any privacy/compliance or integration issues; any headline around patient financial-data handling or poor staff adoption would argue this is a tooling story with limited investable upside.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Treasuries Soar as Tech Slump Threatens Growth
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- What's behind the sell-off in AI neocloud stocks like CoreWeave and Nebius
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- The $4.7 Trillion Bet: When Does AI Capex Become AI Revenue?
- Equity Research Automation Statistics: A 2026 Evidence Check