
Bitmine Immersion Technologies (BMNR) maakt bekend dat het 5,96 miljoen ETH-tokens in bezit heeft en dat het totale bezit aan cryptovaluta en contanten USD 15,8 miljard bedraagt.
Source: PR Newswire
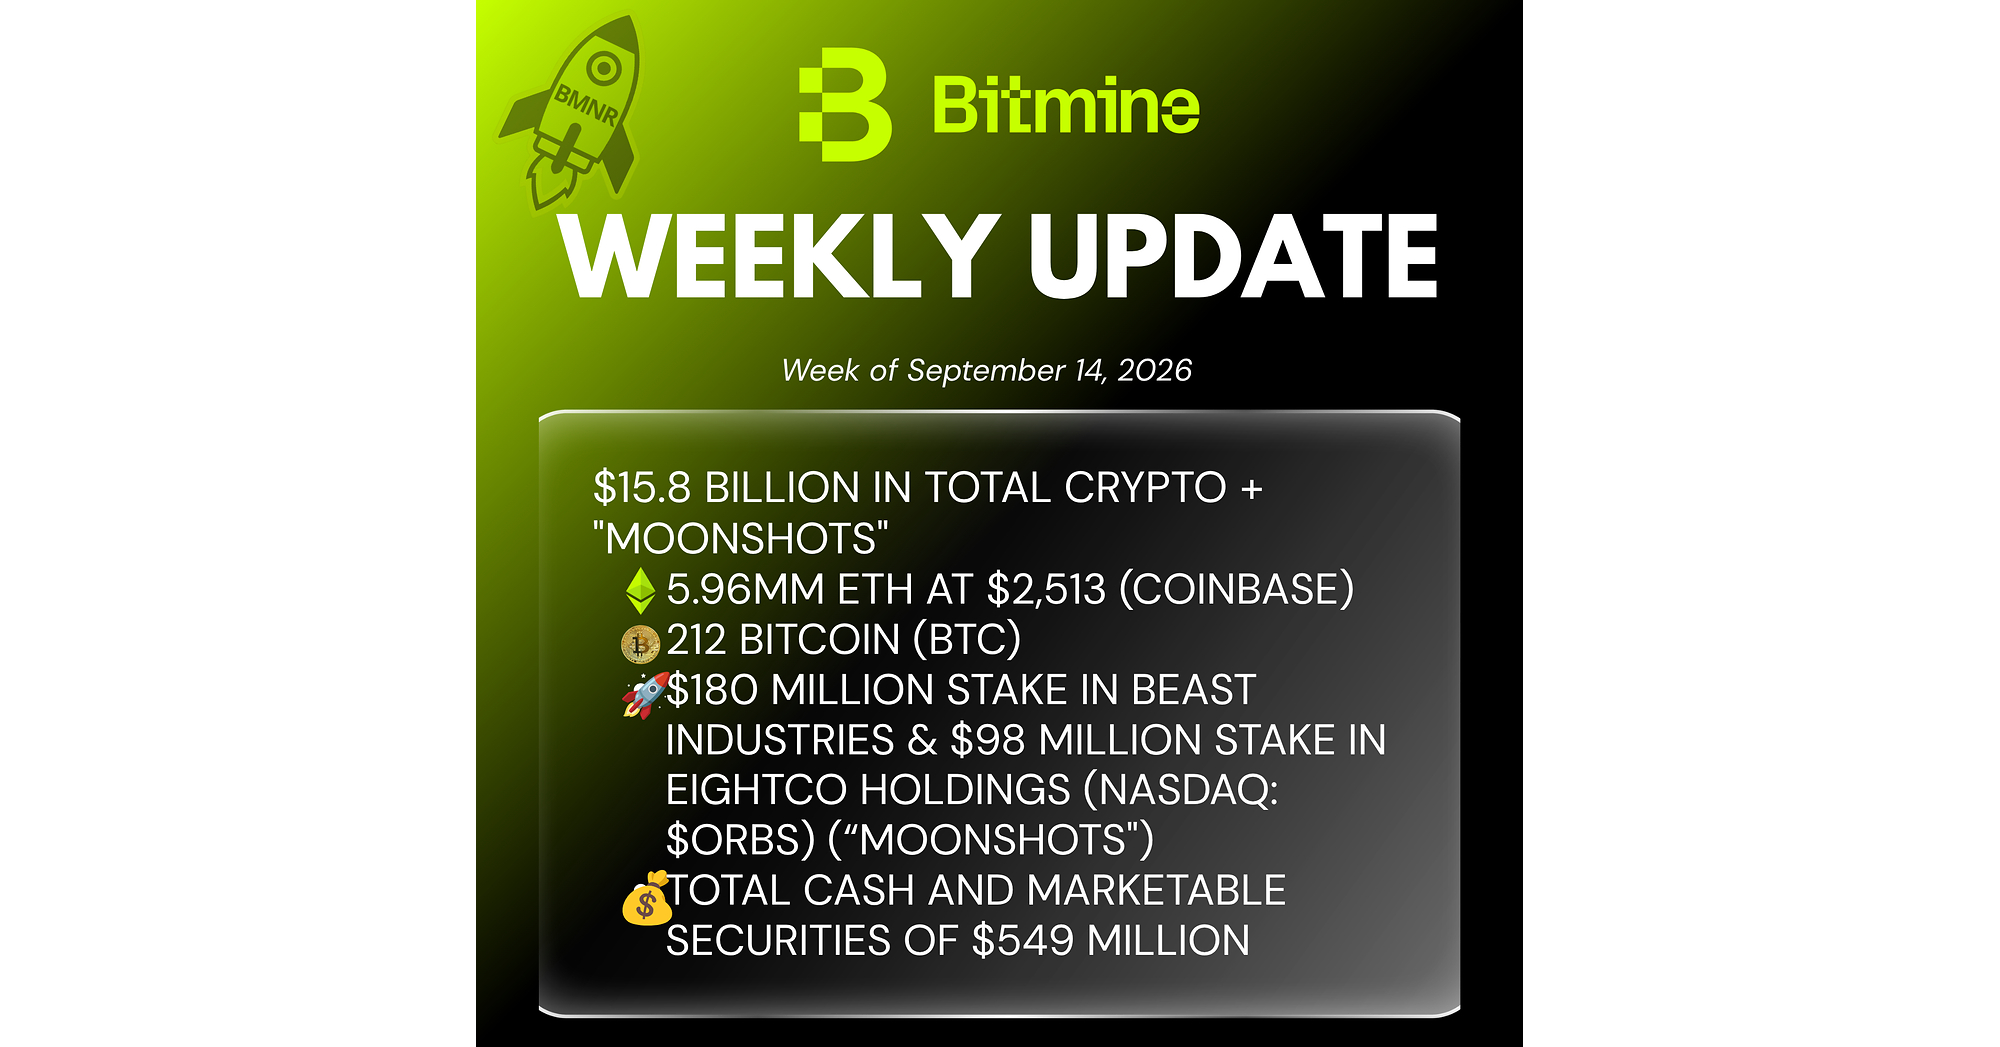
Bitmine held 5,956,378 ETH valued at $2,513 per token as of 13 September, equivalent to 4.9% of Ethereum's 122.0 million-token supply, alongside $549 million of cash and marketable securities. The company acquired 27,180 ETH during the past week and has staked 5.07 million ETH (85% of holdings), projecting $334 million of annualized staking income currently and up to $392 million at full deployment. Management argues ETH's 5,866bp Q3 outperformance versus the S&P 500, potential CLARITY Act progress, tokenization and agentic-AI adoption could drive further institutional crypto demand, though these outlooks are highly dependent on volatile ETH prices and regulatory outcomes.
Analysis
BMNR has evolved from a directional ETH proxy into a concentrated, leveraged-by-capital-markets closed-end vehicle: its equity sensitivity is dominated by ETH mark-to-market and any premium/discount to crypto NAV, not the reported staking run-rate. The staking business can partially offset corporate overhead, but a roughly 2%-3% gross yield on the ETH base does little to cushion a 15%-30% ETH drawdown; investors should not capitalize projected yield as recurring software-like earnings.
The non-obvious risk is market microstructure. A single corporate holder approaching 5% of ETH supply reduces freely tradable float while simultaneously creating a potential forced seller if BMNR needs to fund further accumulation, redeem preferred capital, or defend a falling equity valuation. That dynamic can amplify both an ETH upside squeeze and a downside NAV-discount spiral; it also raises Ethereum governance, validator-concentration, slashing, and regulatory optics that are not captured in a simple treasury valuation.
Near term, a favorable legislative outcome or continued ETH/BTC momentum could sustain retail/institutional flows into BMNR over days to weeks, with COIN benefiting indirectly from higher ETH turnover and custody demand. Over 1-3 months, the more important catalyst is whether BMNR can demonstrate externally sourced MAVAN revenue and durable realized staking yield rather than internally staking its own balance sheet. Over 6-18 months, tokenization adoption is investable only if it translates into transaction fees, stablecoin settlement volumes, and institutional validator demand; the AI linkage remains narrative rather than a measurable Ethereum cash-flow driver.
Consensus appears to be extrapolating asset appreciation while underweighting financing dilution and premium-to-NAV risk. BMNR can outperform sharply in an ETH melt-up because restricted supply and a liquid equity wrapper attract momentum capital, but it should underperform spot ETH if the equity premium compresses even with ETH flat. Falsifiers for the cautious relative view are sustained NAV-premium expansion alongside disclosed third-party MAVAN revenue, or a clear regulatory framework that materially broadens institutional staking participation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.68
Ticker Sentiment
Key Decisions for Investors
- Use a 1-3 month relative-value framework: long ETH exposure via ETH ETF/futures and short BMNR only if BMNR trades at a material premium to independently calculated crypto NAV; require current diluted share count, debt/preferred terms, and locked/staked asset treatment before entry. Target premium normalization, with stop if the premium expands another 25% or third-party staking revenue is disclosed.
- For upside participation, prefer long COIN over BMNR for the next 4-8 weeks if ETH volumes and institutional custody flows accelerate: COIN monetizes turnover without BMNR's single-asset treasury concentration. Exit on declining monthly trading-volume trends or an adverse U.S. staking/regulatory interpretation.
- Pair trade for an ETH-led cycle: long BMNR / short MSTR in small size over days to several weeks only while ETH/BTC continues to make higher highs. The trade captures a potential rotation from BTC treasury vehicles to ETH treasury vehicles; cut if ETH/BTC breaks its prior monthly support or BMNR issues equity at a discount to NAV.
- Do not underwrite the projected staking income until management discloses validator uptime, slashing history, fee splits, liquidity restrictions, and third-party client assets. Treat any inability to maintain realized yield near the stated run-rate for two reporting periods as a catalyst to reduce BMNR exposure.
- Monitor the legislative vote and BMNR financing filings as binary alerts. A delayed/adverse outcome, new preferred issuance, or equity issuance below NAV would likely matter more to BMNR than a modest ETH rally and supports a tactical short or put-spread hedge.
More News
- Elon Musk says he can build a wireless carrier in two to three years. Is that possible?
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off