
GMIF2026: AI Inference Powers the "Token Factory" and Drives System-Level Rethinking of Memory & Storage
Source: PR Newswire
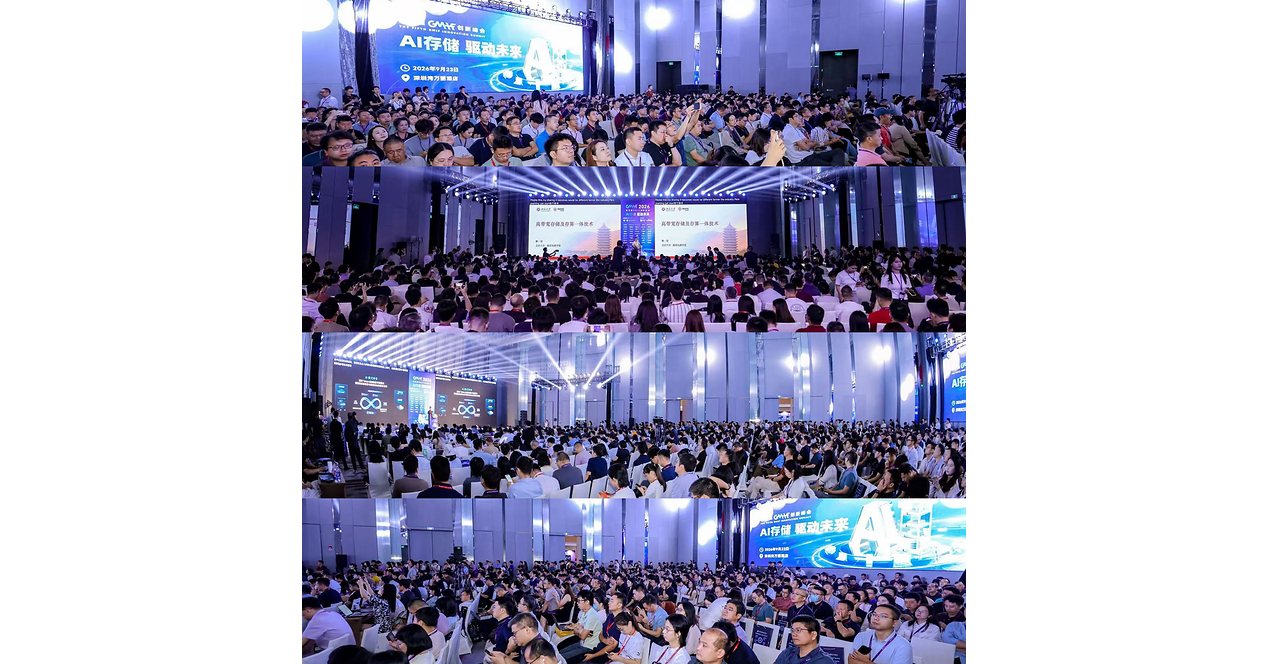
At GMIF2026 in Shenzhen, industry speakers positioned memory and storage as strategic infrastructure for AI inference, citing demand for bandwidth, capacity, and energy efficiency as AI deployments scale. Morgan Stanley’s Daniel Yen projected that more than half of cloud data-center capex will go to memory and storage, excluding HBM, by 2027. Lenovo’s Tao Zhou said 80% of enterprises have deployed at least one type of agent, but fewer than 40% of projects can scale and deliver positive ROI; the article reports industry views and product showcases, not a new company earnings result.
Analysis
The investable mechanism is not “AI uses more memory,” but whether storage offload lowers inference cost enough to expand workloads—and therefore total storage consumption—without displacing higher-value memory. If KV-cache tiering makes large-model inference economical, NAND/enterprise SSD demand could benefit even as some workloads shift away from scarce, expensive HBM. That is a volume-positive but potentially mix-dilutive outcome for the memory complex; NAND supply response and pricing discipline will determine who captures the value.
Among mapped names, SNDK has the clearest direct exposure to enterprise SSD and NAND adoption; SIMO could benefit from controller content as storage architectures become more complex. ARM’s system-efficiency positioning is relevant, but the article provides no evidence that this translates into incremental licensing or royalty economics. Hyperscalers and system vendors may capture much of the savings, while additional NAND capacity or aggressive pricing could limit supplier returns.
The source is a supplier-focused conference release, not evidence of booked demand. Treat its capex outlook and adoption claims as hypotheses until corroborated by hyperscaler spending disclosures, enterprise SSD shipments, NAND pricing/inventory, and company guidance. Near term, this is weak as a standalone catalyst; over 6–18 months, successful storage tiering could broaden AI infrastructure demand. Contrarian risk: investors may conflate more storage capacity with durable pricing power, despite memory’s cyclical supply response.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No event-driven trade on the release alone. Put SNDK on a conditional long watch: enter only after evidence from company results or customer disclosures of rising data-center SSD volumes and stable/improving NAND pricing; size modestly given supply-cycle risk.
- For SNDK, falsify the thesis if NAND inventory builds, contract pricing weakens, or guidance fails to show enterprise SSD demand converting into revenue. Do not infer demand from conference demos or ecosystem awards.
- Track SIMO for controller design wins and revenue conversion over the next 1–3 months; treat the theme as an alert, not a position, until reported results substantiate incremental content. ARM is a secondary beneficiary unless system-efficiency adoption demonstrably lifts its economics.
More News
- AI’s Risks and Rewards (ARM, SNPS)
- TechCrunch Mobility: Rivian’s next act
- The Best Growth Stock to Invest $10,000 in Right Now
- The $5 Trillion Club: Which Is the Better Stock to Own, Apple or Nvidia?
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- Ukraine launches over 1,000 drones at Russia, setting oil facilities ablaze