
Die NOVVA Group sichert sich ein bahnbrechendes Portfolio an erneuerbaren Energien mit einer Leistung von 3,17 GW von ABO Energy zur Stromversorgung der globalen KI-Infrastruktur
Source: PR Newswire
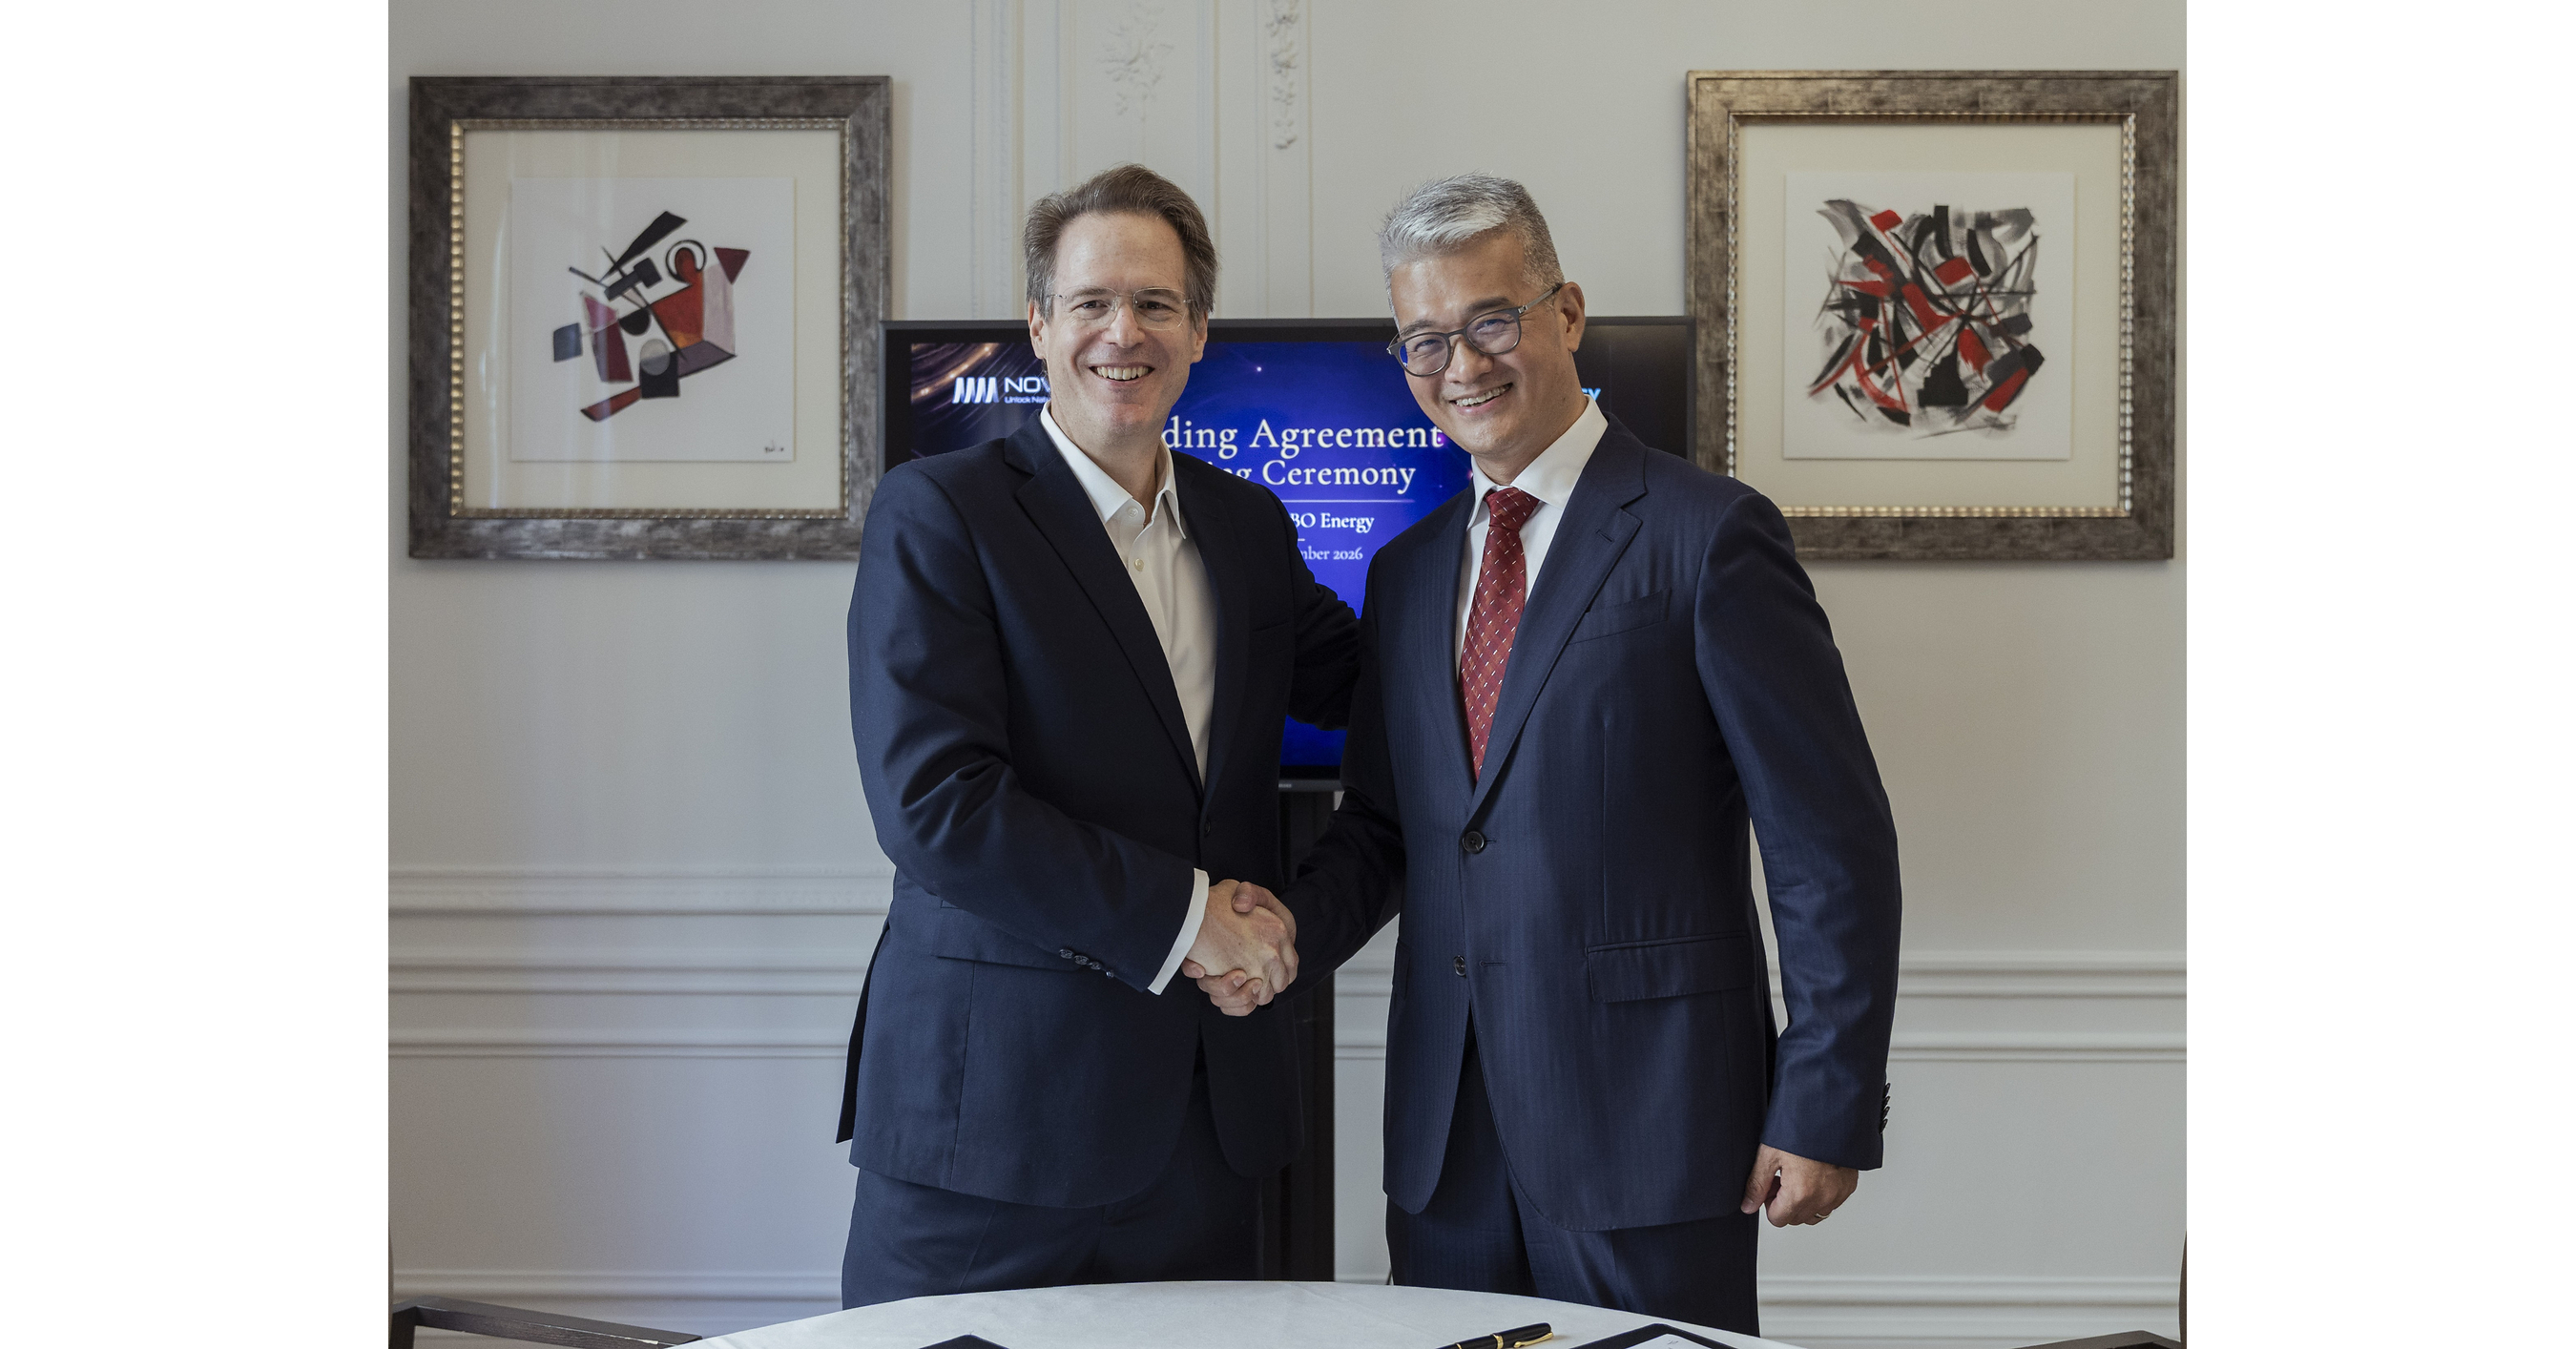
Novva signed a binding framework agreement to acquire a 3.17 GW renewable-energy portfolio in Argentina from ABO Energy, materially expanding its Latin American pipeline for AI data-center power infrastructure. The deal follows Novva's acquisition of three Colombian solar projects from ABO Energy earlier in 2026 and supports its strategy to bundle financeable wind and solar capacity for next-generation data centers, powered land and powered shells. The transaction strengthens Novva's positioning in Latin American clean-energy infrastructure, though no purchase price, project-stage details or closing timetable were disclosed.
Analysis
For AB9, the relevant question is not the headline portfolio capacity but conversion into cash: development-stage asset sales can crystallize recycling capital and reduce funding needs, but valuation depends on interconnection rights, permitting maturity, contracted offtake and closing conditions. A framework agreement is materially weaker than a signed asset purchase agreement with disclosed consideration; the market should not capitalize a full gain until these terms and expected close timing are verified. Near term, the news supports AB9's developer multiple only if it demonstrates repeatable monetization rather than a one-off bilateral transaction.
Argentina adds a significant discount rate to any nominal project value. FX convertibility, tariff/offtake enforceability, transmission congestion and sovereign-risk-driven cost of capital can impair project bankability even where renewable resource quality is attractive. The buyer's data-center demand thesis does not eliminate those constraints: AI load is most valuable where it is physically co-located with reliable grid capacity or backed by hard-currency, creditworthy power contracts. Delays in those prerequisites would shift the portfolio from a near-term monetization catalyst into a long-duration option.
The second-order beneficiary is likely AB9's balance sheet and development bandwidth: sale proceeds, if meaningful, could be redeployed into lower-risk core geographies or storage projects, where late-stage permitted assets command higher risk-adjusted returns. Conversely, this transaction removes future retained-project upside, so the correct comparison is sale proceeds plus redeployment IRR versus the value of holding and building. Consensus may overread the AI association; the investable signal is a developer capital-recycling event, not evidence of immediate incremental data-center electricity demand.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- Maintain AB9 as a watch-list long rather than initiate on the release. Upgrade only upon disclosure of consideration, deposit/termination provisions, project-stage breakdown and expected closing date; a cash consideration that validates value above AB9's implied development-pipeline valuation would be the rerating catalyst over 1-3 months.
- For existing AB9 exposure, retain a modest position through the next results update, but reduce if management does not quantify proceeds and capital allocation. Thesis is falsified by a delayed/conditional closing, material Argentina impairment provisions, or higher net-debt guidance that indicates no meaningful cash realization.
- Do not express the view through broad clean-energy ETFs such as ICLN in the next 1-3 months: Argentine execution risk is idiosyncratic and the transaction is unlikely to move diversified renewable-equipment earnings. The cleaner trade is AB9-specific only after transaction economics are independently verifiable.
- Monitor Argentine sovereign spreads, FX-policy changes and transmission-connection milestones over 6-18 months. A sustained widening in sovereign risk or inability to secure dollar-linked offtake would warrant treating the remaining Argentina pipeline at option value rather than assigning operating-project multiples.
More News
- Skupina NOVVA získala od spoločnosti ABO Energy prelomové portfólio obnoviteľných zdrojov energie s výkonom 3,17 GW na napájanie globálnej infraštruktúry umelej inteligencie
- Skupina NOVVA získala od společnosti ABO Energy významné portfolio obnovitelných zdrojů energie o výkonu 3,17 GW, které bude napájet globální infrastrukturu umělé inteligence
- NOVVA Group adquiere una cartera histórica de energía renovable de 3,17 GW a ABO Energy
- NOVVA Group secures landmark 3.17 GW renewable energy portfolio from ABO Energy to power global AI infrastructure
- US House votes to end Iran war, 7 Republicans join in favour
- Exclusive-SK Hynix in talks with Intel about deal to make memory chips in the US for the first time, sources say