
NEXT IS NOW: CFMOTO Brings Its Global Vision to Life at EICMA 2026
Source: PR Newswire
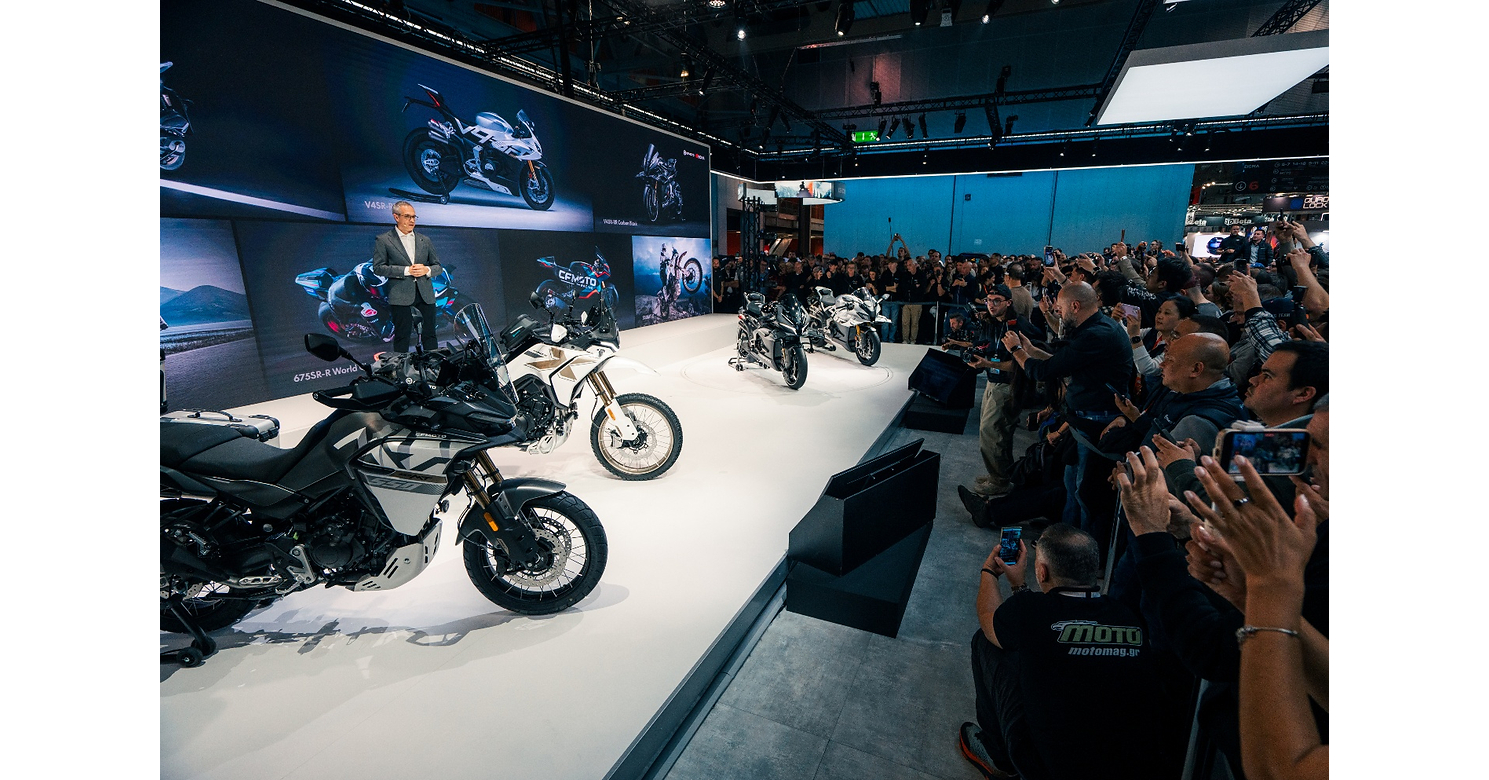
CFMOTO reported US$186 million of R&D investment in the first three quarters of 2026, up 46.39% year over year, and unveiled a broad lineup of motorcycles, scooters and off-road vehicles at EICMA 2026. Its global network spans more than 100 countries and regions and over 9,000 partners. The announcements highlight investment and product expansion, but the article provides no sales or earnings impact.
Analysis
The investable signal is execution, not the launch slate. A broader range and more local dealer/service coverage could help CFMOTO compete with established powersports brands such as Polaris, BRP and Honda, but product specifications and race visibility do not establish consumer demand, pricing power or profitable share gains. The second-order risk is operational: more models, sub-brands and markets can raise inventory, parts, warranty and dealer-support complexity before scale benefits arrive. The reported R&D step-up is therefore both a potential capability investment and a near-term margin burden; its payoff depends on launches converting into sell-through rather than dealer inventory.
The V4 superbike is most plausibly a brand halo, not a material volume driver absent evidence on homologation, production plans and pricing. The ORV and mid-displacement models have a clearer path to commercial relevance, but overlap among models could dilute throughput or cannibalize existing products. Electrification remains an option rather than a demonstrated growth engine: no unit economics, battery sourcing, or adoption data are provided.
Immediate market impact should be limited: this is company-sponsored show coverage, not independently verified demand or financial guidance, and no ticker is supplied for direct exposure. Over 1–3 months, dealer orders, deliveries and inventory will matter more than launch attention; over 6–18 months, sustained international sell-through and warranty-adjusted margins would validate the globalization thesis. The contrarian risk is treating engineering ambition as evidence of premium-brand economics before distribution productivity is proven.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No direct trade on this release alone. Do not use Polaris, BRP or Honda as a proxy short: the article provides no evidence of competitor share loss or a near-term earnings revision.
- Put CFMOTO on a watchlist for verifiable follow-through: production timing, market-by-market homologation, dealer orders versus retail sell-through, inventory, pricing, and warranty/parts costs. These are the missing inputs needed to assess whether R&D and distribution expansion earn an adequate return.
- For a 1–3 month catalyst check, look for independent registration or shipment data and dealer inventory trends. Strong retail sell-through without discounting would support the share-gain thesis; shipment growth accompanied by rising dealer stock or promotions would undermine it.
- Falsify the longer-term premium-brand thesis if launches are delayed, key markets restrict homologation, or management reports weak sell-through and deteriorating margins as R&D and service-network costs scale.
More News
- Tech stock rout, driven by US AI fears, continues in Asian trading
- Asian Markets Tally Losses From Worsening Global Rout
- AI’s Grip on Financial Markets Was Never Clearer on the Way Down
- Elon Musk once said the Cybertruck would be Tesla’s ‘best product ever.’ Now he’s winding down production
- Fox completes its $22B acquisition of Roku
- Elanco Shares Jump After Q3 Beat and Outlook Raise