
The Agency Appoints James Corcoran as Chief Financial Officer For New Jersey, Manhattan and Westchester Operations
Source: PRWeb
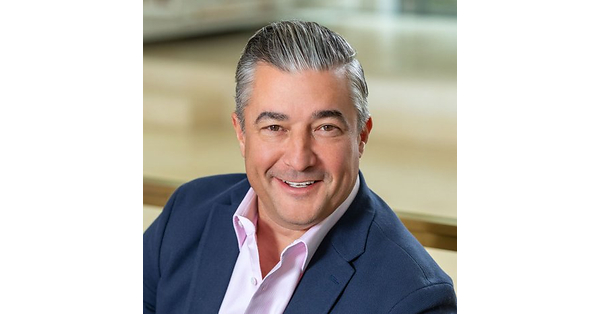
The Agency appointed James Corcoran CFO of its independently owned New Jersey, Manhattan and Westchester operations following the June 2026 transition of approximately 1,200 agents across 26 greater New York offices from Christie's International Real Estate. Corcoran, a real-estate finance executive with more than 20 years of experience, will oversee financial strategy, planning and operations as the brokerage integrates the offices and expands its Northeast infrastructure. The leadership hire signals continued investment in operational scale but is unlikely to have material public-market impact.
Analysis
This is not a public-markets catalyst: The Agency and its tri-state operating group are privately held, and a senior finance hire does not establish a measurable change in transaction volume, agent productivity, or profitability. The relevant read-through is that independent luxury-brokerage operators are still spending on integration and back-office capacity rather than retrenching, modestly supporting the view that high-end housing transaction activity may be stabilizing in the New York metro area.
The competitive implication is more meaningful for franchise-heavy public brokers than for homebuilders. Expanded scale and centralized finance can improve recruiting economics, lead-generation conversion, and commission retention for a local operator, raising competitive pressure at the margin on Anywhere Real Estate (HOUS), Compass (COMP), and eXp World Holdings (EXPI) in affluent Northeast submarkets. But any impact is too small relative to these companies' national agent bases to alter near-term estimates; it becomes investable only if it signals a broader wave of brand conversions or agent migration.
Over the next 1-3 months, watch fall Manhattan and suburban contract data, jumbo-mortgage spreads, and public-broker commentary on agent count and transaction-side trends. A narrowing of jumbo spreads and improving high-end inventory turnover would matter more for COMP, whose concentration makes it the highest-beta listed expression of a luxury-market recovery. The thesis is falsified if transaction gains are driven only by price mix while unit closings and agent retention remain weak, or if mortgage rates re-accelerate and suppress discretionary move-up demand.
Contrarian view: investors may overinterpret office additions and leadership investment as proof of a housing upcycle. Brokerage fixed-cost leverage cuts both ways; integration, technology, and recruiting spend can depress margins before volume converts, while well-capitalized local independents can take share without expanding the industry's aggregate commission pool. There is no standalone trade from this release.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No immediate position: treat this as a private-company operational datapoint, not an earnings-revision catalyst for listed brokers.
- Place COMP on a 1-3 month long watchlist versus HOUS if Manhattan/Westchester contract volumes improve for two consecutive monthly prints and COMP reports stable-to-positive principal-agent retention; COMP offers greater upside torque to a luxury-volume recovery but carries higher execution and cash-burn risk.
- Avoid using the news to buy HOUS or EXPI. Reassess only if either company identifies accelerated Northeast franchise conversions, net agent additions, or improved transaction-side growth in the next earnings cycle.
- For existing housing exposure, monitor jumbo mortgage spreads and 10-year Treasury yields: a sustained rate rise of 50 bps or renewed widening in jumbo spreads would argue against adding luxury-brokerage beta despite local operational expansion.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Microsoft's Big Bets on AI Start to Pay Off