
1 in 3 Americans have lost track of retirement savings from a previous job, new Empower research finds
Source: PR Newswire
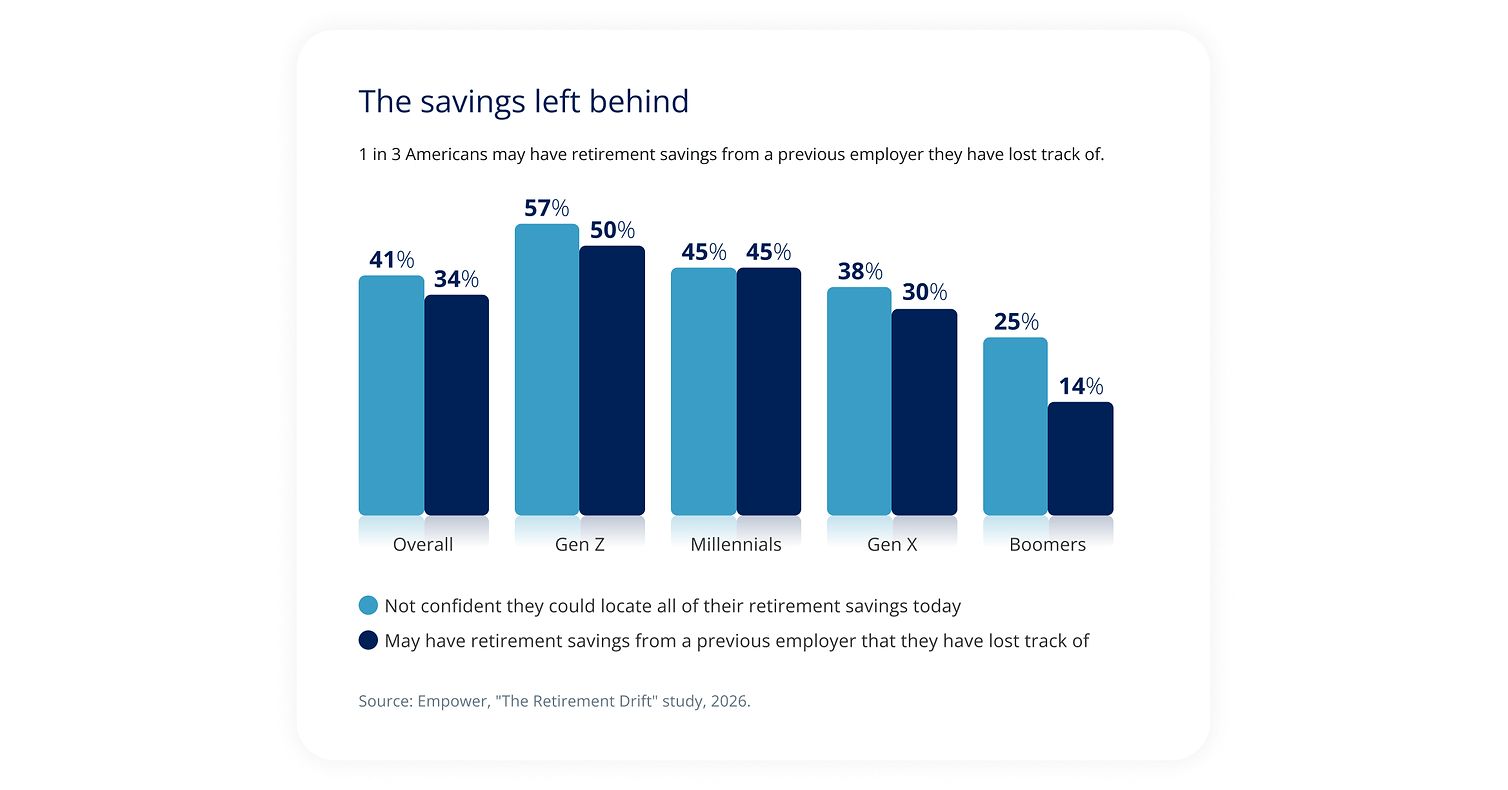
Empower’s survey of 2,005 U.S. adults found 34% may have lost track of retirement savings from a previous employer, including 50% of Gen Z and 45% of Millennials. More than half (54%) said savings spread across multiple accounts make retirement planning harder, while 76% said clear, step-by-step guidance would make them more likely to act. The findings describe consumer retirement-planning challenges and are not a reported change in Empower’s financial performance.
Analysis
This is a demand signal for retirement-account consolidation and advice, not evidence of incremental assets or revenue: the survey is company-sponsored, and it does not establish how many accounts are actually recoverable, their balances, or whether savers would roll them to Empower. If the friction is real, the strategic prize is retaining assets during job changes and capturing IRA rollovers, advice relationships, and potentially longer-lived client data. That could intensify competition among recordkeepers and wealth platforms, including Fidelity, Vanguard, and Alight, while making simpler rollover workflows a distribution advantage. The countervailing effect is that consolidation can move assets away from an incumbent employer-plan provider, and execution depends on employer-plan rules, fees, investment options, and advice/regulatory safeguards—not just consumer intent.
Near term, the release is unlikely to support a fundamental repricing: it offers no conversion, retention, or revenue data and no public-company identity in the supplied mapping. Over 1–3 months, watch for firms to report rollover capture, IRA flows, participant retention, and acquisition costs. Over 6–18 months, digital guidance could lower servicing friction, but human-advice preference in the survey also implies higher-touch service may remain necessary. Contrarian read: widespread account fragmentation sounds like a large addressable market, but awareness and stated willingness are not action; account balances and actual rollover rates determine economics. No directional trade is justified from this release alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.00
Key Decisions for Investors
- No trade on the survey alone; treat it as a low-confidence industry signal rather than proof of earnings upside for any provider.
- Monitor retirement-platform disclosures for IRA rollover inflows, assets retained after job changes, participant growth, and advice adoption; these are the metrics needed to validate monetization.
- If a provider later demonstrates sustained rollover capture without materially higher acquisition or servicing costs, reassess it against recordkeeping and wealth-management peers; the thesis is weakened by flat flows or rising costs.
- Watch regulatory or plan-design changes affecting rollovers, as well as employer restrictions and fee comparisons, which could limit consolidation even if consumer interest is genuine.
More News
- The French are rioting as inflation hits 3.4% while wage growth and GDP remain stagnant. It’s higher in Trump’s America
- French markets tumble as riots add to political crisis
- European stocks fall after violent protests in France, while oil drops as Trump puts Russia sanctions on hold
- Citi Global Chief Economist on Global Growth
- China’s Growth Rebound Eases Pressure for More Stimulus
- France is rioting over surging inflation, skyrocketing national debt and crumbling schools. America is its sleeping twin
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Search Earnings Call Transcripts With AI
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI