
The Rising Cost of Money Is Seeping Into Everything
Source: Bloomberg
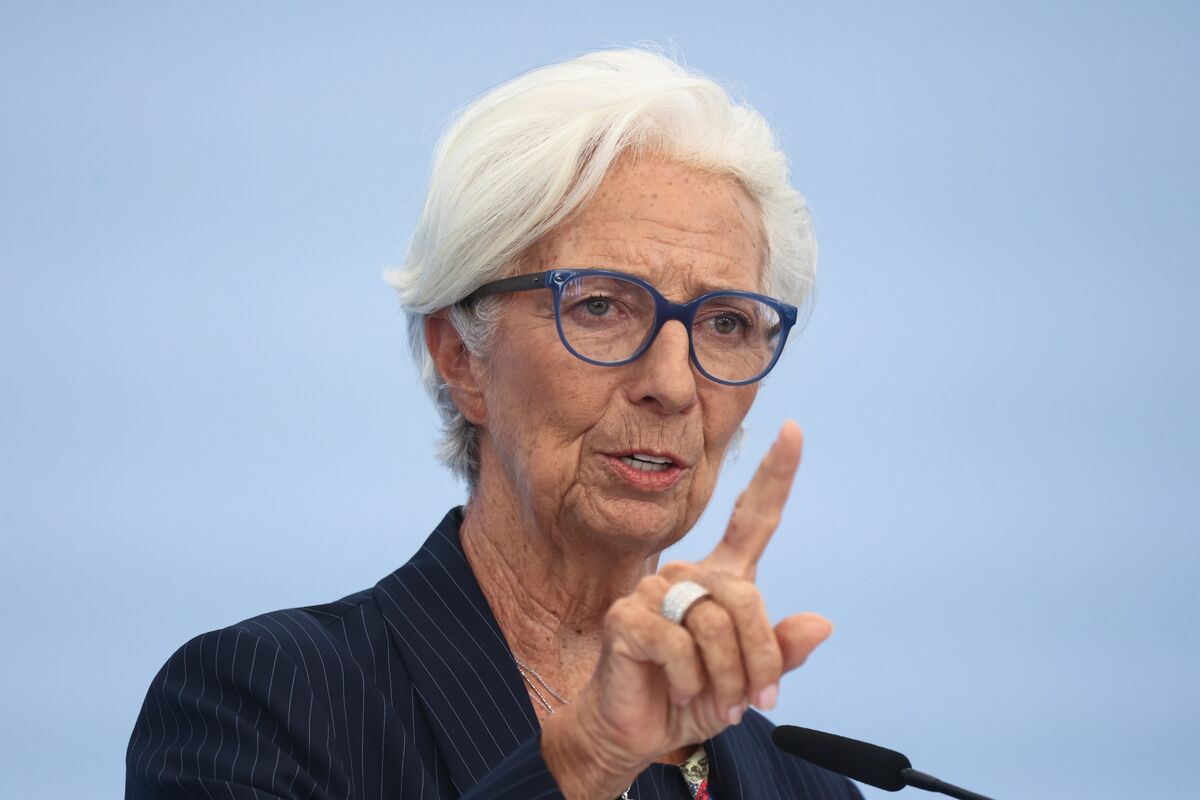
The article highlights that persistently higher borrowing costs are increasingly affecting mortgages, markets, wealth management and private capital. It emphasizes uncertainty over the path of global interest rates ahead of a Dec. 9 London event, while pointing to ECB President Christine Lagarde's views on the policy outlook.
Analysis
This is not a standalone market catalyst, but it reinforces a regime in which the marginal borrower—not the headline policy rate—drives equity dispersion. The key transmission channel over the next 1-3 months is refinancing: commercial real estate, sponsor-backed issuers and leveraged small caps face materially higher interest expense before broad household stress is visible. Public companies with near-term maturities and floating-rate debt should see estimate risk and multiple compression well ahead of an actual default cycle.
The more actionable second-order effect is private-market clearing. Higher discount rates and constrained exit markets force down-rounds, continuation vehicles and asset sales, benefiting listed alternative managers with permanent capital and opportunistic credit platforms—BX, APO, ARES and KKR—provided fundraising remains intact. Conversely, regional banks with CRE concentration and weak deposit franchises remain exposed to losses that are currently deferred by loan extensions rather than resolved; KRE is a cleaner risk proxy than broad financials.
Consensus remains focused on the timing of central-bank cuts. More important is whether long-end yields and credit spreads decline enough to reopen transaction markets: modest policy easing alongside a sticky term premium would not repair CRE valuations or private-equity exit multiples. A durable bull case for rate-sensitive assets requires both lower 10-year Treasury yields and stable-to-tighter high-yield spreads; cuts driven by recession would be negative for cyclicals despite lower front-end rates.
Over 6-18 months, persistent real rates favor cash-generative incumbents and discourage capital-intensive challengers. Housing supply remains constrained, but affordability pressure shifts demand toward rentals and away from entry-level ownership, supporting well-capitalized apartment REITs only if long rates fall; otherwise, nominal rent resilience can be overwhelmed by refinancing and cap-rate expansion.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.15
Key Decisions for Investors
- Maintain a defensive pair for the next 1-3 months: long BX or APO / short KRE. Alternative managers benefit from stressed-asset deployment and eventual transaction-market normalization, while KRE retains CRE and funding-cost asymmetry. Reassess if high-yield spreads widen above roughly 500 bps, which would impair fundraising and realizations.
- Avoid broad REIT beta until the 10-year Treasury yield falls sustainably rather than merely on a single weak macro print. Use VNQ as the sector monitor; a move lower in rates accompanied by stable credit spreads would favor selectively adding residential REIT exposure such as AVB or EQR over office-heavy exposure.
- Screen and underweight highly levered small-cap and sponsor-backed public equities with significant 2026-2027 maturities; IWM is an imperfect liquid hedge for this refinancing vulnerability. The thesis is invalidated if credit spreads compress materially and new-issue markets reopen at coupons that allow liability management without major equity dilution.
- For a rate-relief expression, prefer a 3-6 month long IEF versus short KRE structure rather than outright long rate-sensitive equities. Risk/reward improves if disinflation lowers intermediate yields, while the regional-bank short preserves exposure to the slower-moving CRE loss-recognition cycle.
More News
- US 30-Year Yield Hits Highest Since 2004
- SEBI Allows Portfolio Managers to Invest Overseas, Short Equity Options
- History shows financial calamities occur when rates rise rapidly like this: 'Something always breaks'
- Kevin Warsh might have to get a lot less popular on Capitol Hill as bond yields soar and rate expectations turn hawkish
- Surging Treasury yields are posing a brand new problem for Kevin Warsh and the Fed
- 30-year fixed mortgage rate jumps sharply Thursday to 7.45%
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research