
YFORE Debuts ODMS In-Cabin Sensing System to Enhance Cockpit Safety
Source: PR Newswire
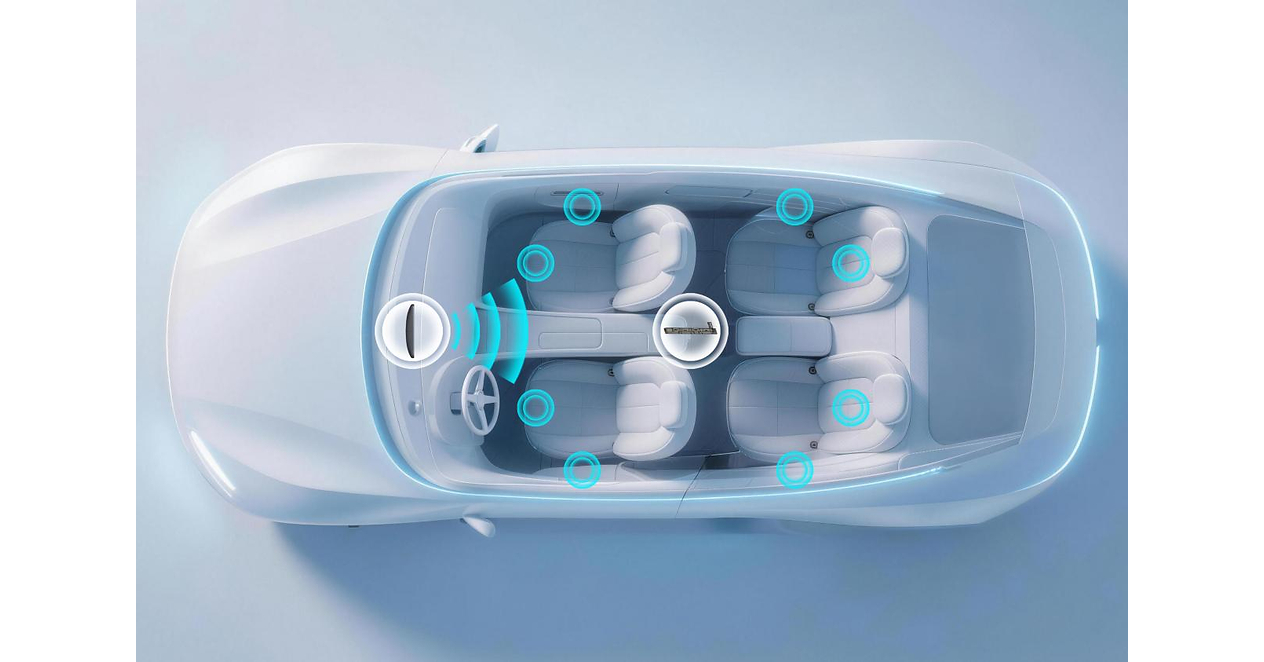
YFORE Technology (new North America manufacturing facility in Georgia) debuted its Occupant & Driver Monitoring System (ODMS), combining a DMS/OMS smart mirror with automotive-grade cabin radar to improve detection across rear rows and footwells where vision-only systems can miss occupants. The ODMS targets seven functions including fatigue/distraction/phone use and seatbelt/occupant classification, aiming to support Euro NCAP “five-star” safety outcomes. The news is more product and capability-focused than financial, so the expected market impact is limited for most public-market investors.
Analysis
This is less a revenue event than a content-mix signal: cabin monitoring is moving from a nice-to-have feature to a compliance-adjacent module, which tends to benefit incumbents with OEM relationships and hurts fragmented seat/headliner point solutions. The economics likely accrue to whoever owns the integrated mirror/radar stack, but the headline should not be mistaken for near-term P&L; the real value is in future platform content and higher attach rates, not this one announcement.
The second-order winner is likely the automotive sensing supply chain: image sensors, cabin radar, and adjacent compute/connectivity vendors get pulled deeper into interior electronics content per vehicle. Gentex looks like the cleanest public proxy if the smart-mirror architecture gains share, while STMicroelectronics and onsemi are better ways to express incremental sensor content than betting on the Tier-1 itself. Potential losers are legacy interior suppliers with lower electronics intensity, especially where the bill of materials shifts from mechanical/trim content toward software-defined modules.
The contrarian view is that markets often overprice these PR-driven launches: OEM validation, software homologation, and platform SOP can take 12-24 months, and Euro NCAP/NHTSA acceptance may still settle on cheaper camera-first solutions. If regulators do not require radar-based full-cabin coverage, the addressable spend is smaller and margin capture gets competed away quickly. The thesis breaks if OEM sourcing announcements fail to show up by the next model-year cycle or if safety standards remain permissive on lower-cost architectures.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- Do not chase the announcement itself; wait 30-60 days for named OEM platform wins before adding exposure. If one appears, favor a 6-12 month long GNTX / long STM basket as the cleaner way to own cabin-content expansion.
- Use any post-PR strength in broad auto suppliers to fade the move rather than buy it outright: pair long GNTX against short MGA or LEA for a 3-6 month relative-value trade, targeting 8-12% spread capture if integrated sensing adoption becomes more explicit.
- Set a watch item on Euro NCAP draft protocol updates and NHTSA occupant-monitoring guidance; if either accepts camera-only compliance, reduce any cabin-sensing exposure because the incremental radar content thesis weakens materially.
- If no new OEM design win is disclosed by the next earnings cycle, treat this as capability signaling rather than monetization and avoid direct exposure to YFORE-adjacent Tier-1 names.
More News
- Why this little known Chinese chipmaker has caused a global stock rout
- Apple releases HomeView smart home hub with screen as showcase for Siri AI
- Microsoft Eyes First Record in Nearly a Year as AI Rally Builds
- Why did investors react so negatively to Schneider-PTC deal? M&A expert weighs in
- French fridge fright: Why supermarkets have become target for hackers
- Chip Selloff Deepens Before Wall Street Earnings
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Financial Research Benchmarks: What the Scores Mean
- State of M&A and Private Markets, June 2026: A $4.9 Trillion Rebound, Underwritten on Money That Never Got Cheaper