
Seatrium and Karpowership Mark Sailaway of LNGT Türkiye & Completion of Seven-Vessel FSRU Conversion Programme
Source: PR Newswire
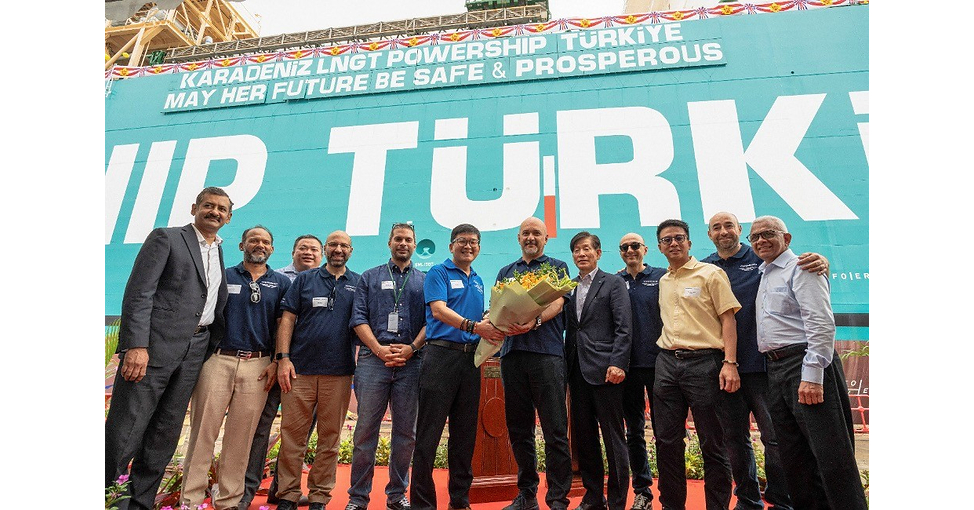
Seatrium and Karpowership completed the LNGT Türkiye, the seventh and final FSRU conversion in their programme converting seven LNG carriers into floating regasification units since 2018. The vessels will supply feed gas to Karpowership's Powership fleet across four continents, supporting its LNG-to-power operations; Karpowership operates 45 Powerships with more than 8,500 MW of installed capacity. The completion reinforces Seatrium's FSRU-conversion capabilities and the partners indicated plans to expand collaboration into next-generation Powerships and offshore-energy projects.
Analysis
For Seatrium (S51.SI), programme completion is operationally positive but not automatically earnings-positive: the relevant question is whether the released Admiralty labor, dock and engineering capacity is redeployed at comparable gross margin before handback. A completed multi-year conversion contract removes execution risk and working-capital uncertainty, but also creates revenue roll-off risk over the next 2-4 quarters unless follow-on Powership, FPSO, repair or gas-infrastructure awards are contractually booked.
The stronger read-through is strategic rather than near-term financial. FSRU conversion capability is scarce because it requires cryogenic integration, regasification systems and reliable commissioning, creating a barrier versus conventional shipyards; this may improve Seatrium's bid discipline on future LNG-to-power and offshore electrification projects. However, Karpowership is private and its future order pipeline is not independently visible, so management commentary about expanded collaboration should not be capitalized into estimates without order value, delivery timing, milestone profile and margin disclosure.
A contrarian interpretation is that floating LNG-to-power demand can be cyclical and sovereign-credit constrained rather than a clean recurring-growth market. New projects depend on host-country PPAs, LNG affordability and financing; weaker LNG prices help project economics, while higher global gas prices can impair end-customer collections and defer vessel orders. Over 6-18 months, the more investable beneficiaries of lower gas prices may be LNG import infrastructure and merchant LNG carriers, while Seatrium's upside requires demonstrable conversion of technical credentials into higher-margin backlog.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- Maintain a watch, not a new long, on S51.SI into the next two results cycles. Upgrade only if disclosed orderbook replenishment covers the completed programme's revenue run-off and Repairs & Upgrades/Oil & Gas segment margin holds or expands; absence of replacement awards is thesis-falsifying.
- For investors already long S51.SI, use any press-release-driven strength to reduce exposure unless accompanied by a firm new contract with value, delivery dates and payment milestones. The risk/reward is unfavorable when the incremental information is completion rather than a booked award.
- Monitor LNG benchmarks and emerging-market power-project announcements over 1-3 months as leading indicators for floating LNG-to-power demand. Sustained lower delivered LNG costs plus financed power contracts would support a future Seatrium backlog thesis; rising LNG prices or PPA/payment disputes would favor avoiding the exposure.
- Track competitive contract wins at Hanwha Ocean (042660.KS), Samsung Heavy (010140.KS) and HD Hyundai Heavy Industries (329180.KS). A meaningful FSRU/FPSO conversion award to these yards at aggressive pricing would indicate margin competition and weaken the case for a scarcity premium at S51.SI.
More News
- Saudi, Turkish, Pakistani chiefs plan urgent talks amid Yemen fighting
- US 30-Year Yield Hits Highest Since 2004
- Oil falls amid optimism over potential diplomatic solution to the Iran conflict
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- Kevin Warsh might have to get a lot less popular on Capitol Hill as bond yields soar and rate expectations turn hawkish
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads