
Clear Channel Outdoor Renews and Expands Advertising Partnership with Northwest Florida Beaches International Airport
Source: PR Newswire
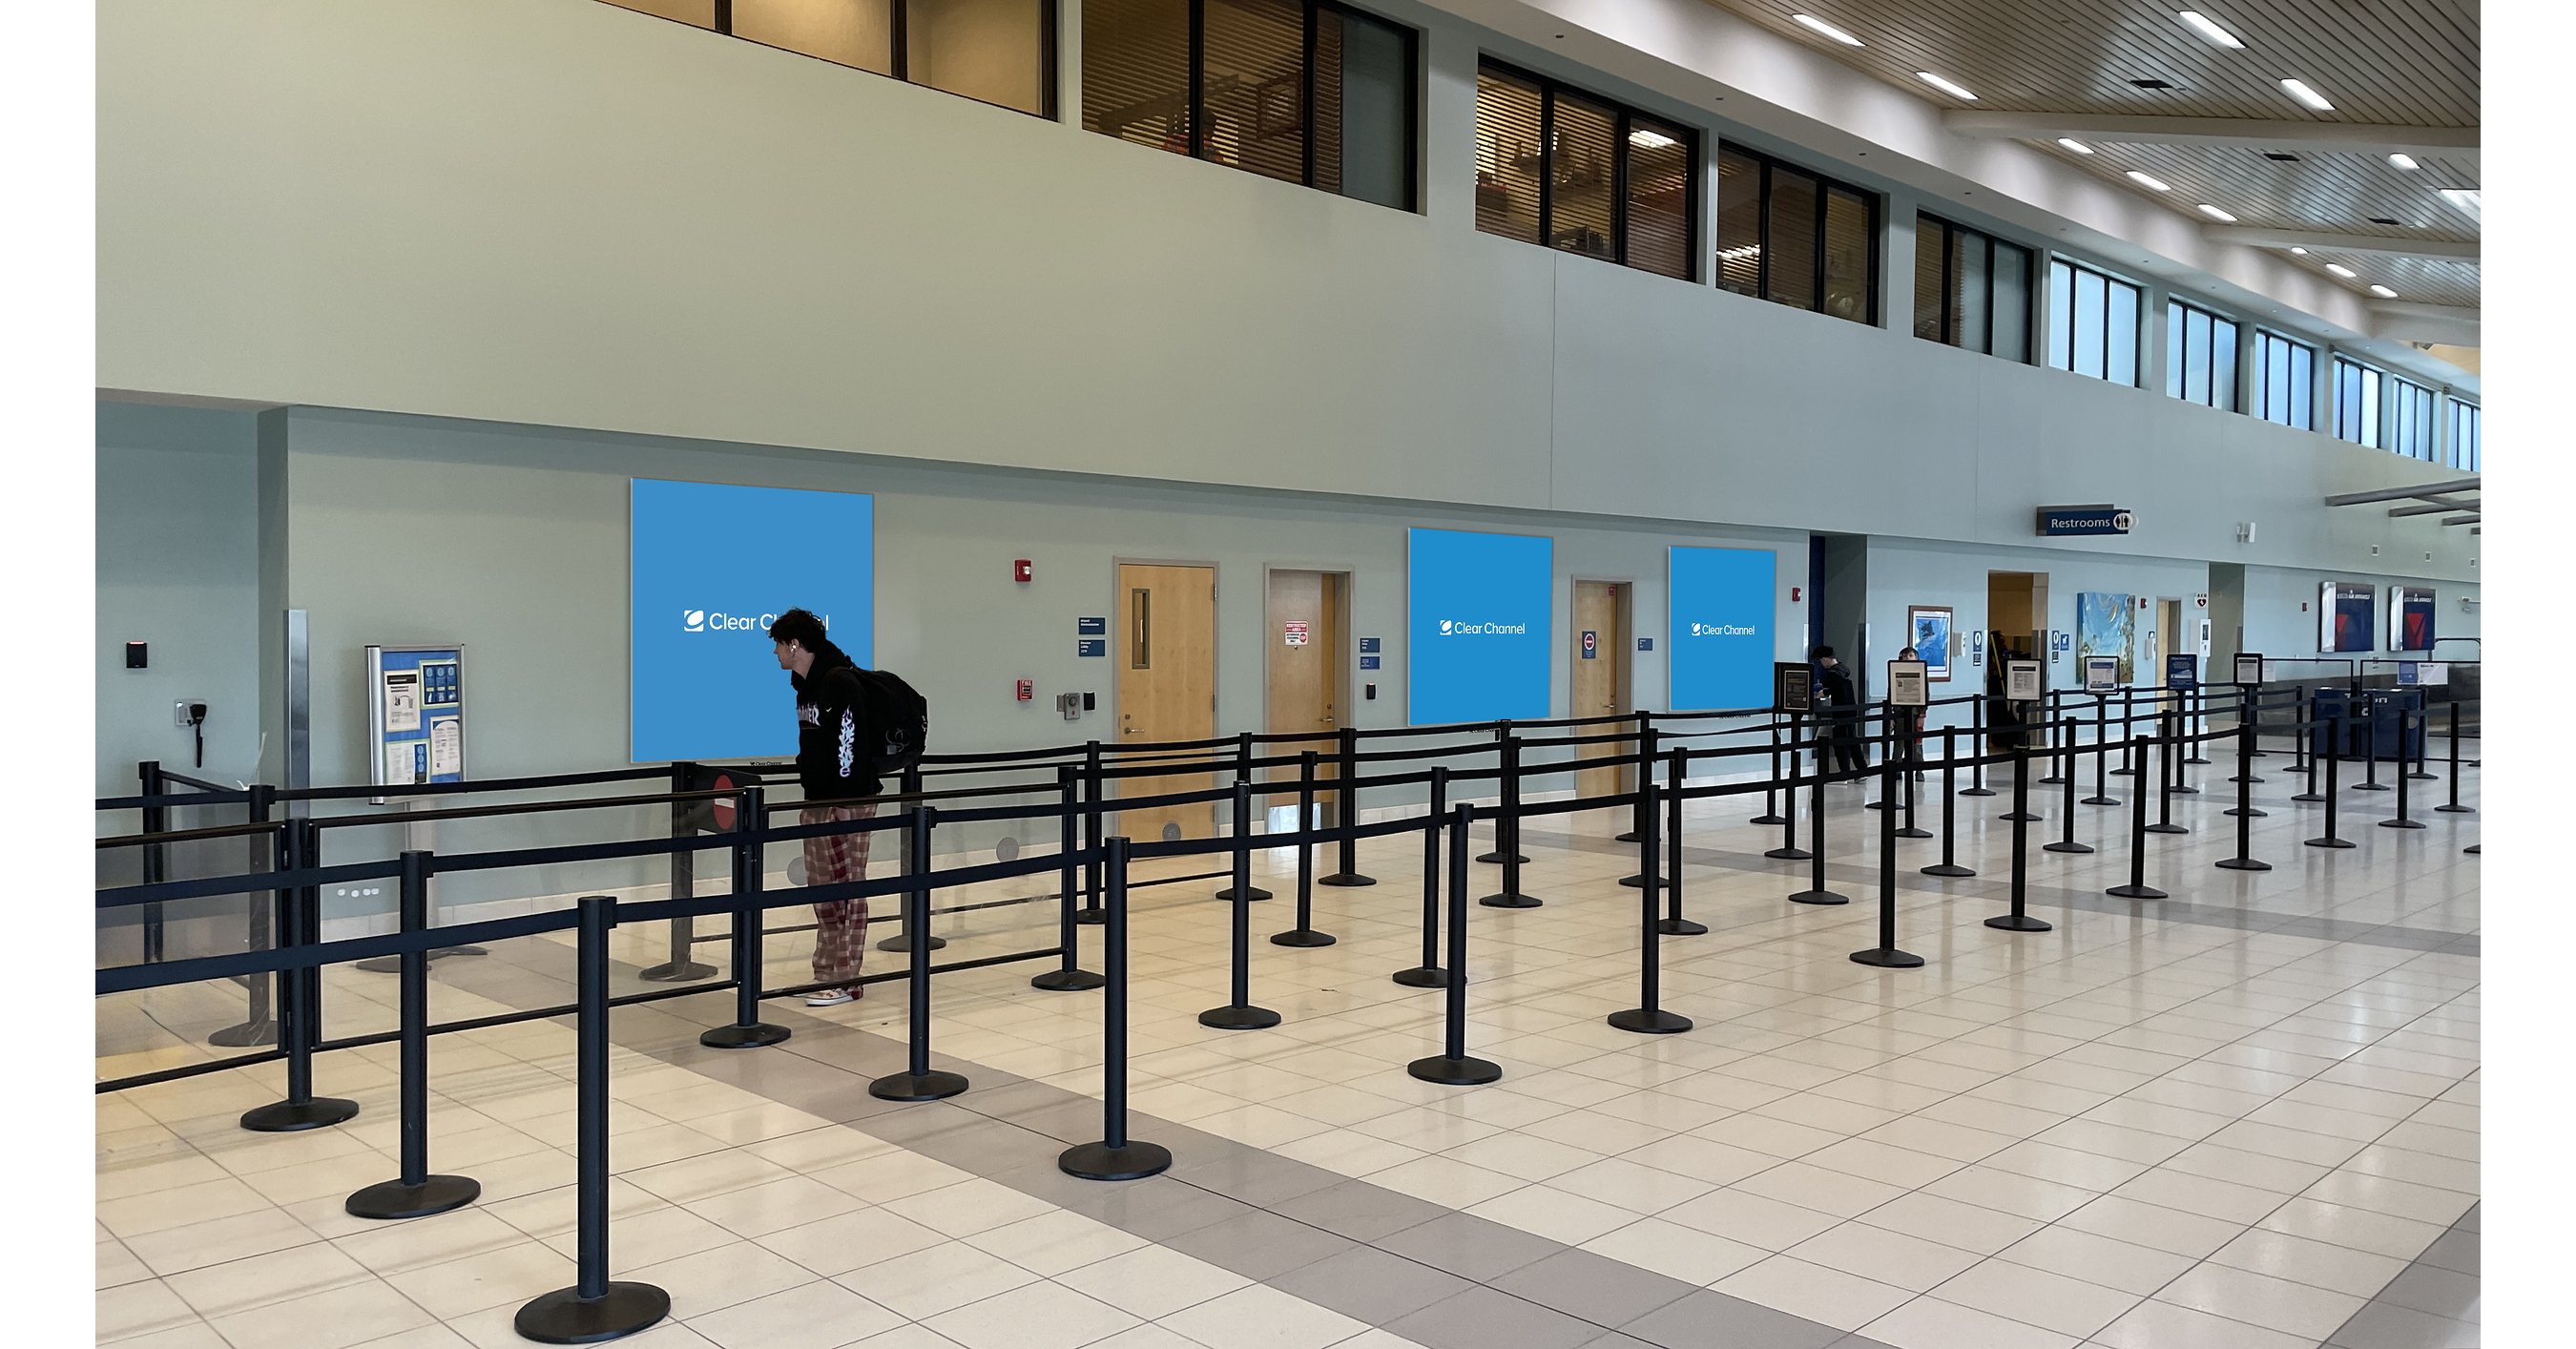
Clear Channel Outdoor renewed and expanded its advertising partnership with Northwest Florida Beaches International Airport under an initial three-year agreement, committing to invest in digital displays and experiential advertising as the airport expands its terminal toward a 2029 completion. ECP served a record 1.9 million passengers in 2025, up 3.1% year over year. The deal supports the airport’s commercial growth, but no investment amount or financial impact for CCO was disclosed.
Analysis
The signal is strategically positive for CCO but not yet an earnings catalyst: retaining the concession protects access to inventory, while digital displays could improve ad yield and let CCO sell campaigns more flexibly. The key unknown is whether advertiser demand and pricing justify the infrastructure spend within an initial three-year term; neither the investment amount nor contract economics are disclosed. Passenger growth is supportive, but traffic is not equivalent to monetizable impressions, and a leisure-heavy market may bring seasonality. Construction through 2029 creates a timing mismatch risk: installation delays or terminal disruption could defer revenue while investment is already committed. The renewal demonstrates retention at one airport, not broad share gains against providers such as JCDecaux, and ECP alone is unlikely to establish a material consolidated earnings change for CCO. The named airlines have no clear direct earnings read-through from this advertising agreement. Near term, expect limited fundamental repricing; over 1–3 months, watch CCO disclosures for airport-segment growth, digital inventory utilization and capex. Over 6–18 months, the thesis depends on digital yield gains exceeding incremental costs and the airport’s traffic continuing to expand. Falsifiers include delayed construction or deployment, weakening ECP passenger volumes, and CCO reporting higher airport investment without corresponding revenue or yield improvement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on the announcement: the deal economics and scale are undisclosed, so the information does not support a defensible estimate of CCO earnings impact.
- Treat CCO as a watch item rather than chasing the positive headline. Reassess after the next earnings disclosures for airport-segment revenue trends, digital inventory utilization and incremental capex.
- Verify the concession’s payment structure, CCO’s committed investment and the timing of installation against the 2029 terminal completion; these determine whether the three-year initial term offers adequate payback.
- A constructive thesis would weaken if ECP traffic reverses, the terminal schedule slips materially, or CCO’s airport revenue/yield fails to improve as digital capacity comes online.
More News
- Airlines are trading nearly 23% higher ticket prices for emptier planes as jet fuel prices spike over 90% from the Iran War’s fuel squeeze
- Analysis-US airlines favor higher fares over fuller planes as fuel costs squeeze profits
- American Airlines hikes annual fees on rewards cards for first time since 2018
- Caviar, champagne and a Porsche ride as aviation widens its class divide
- TD Cowen keeps United, Delta top airline picks as fuel costs threaten earnings
- Stock Market Today, Oct. 27: JetBlue Surges 19% on Stronger Q4 Revenue Guidance and Margin Improvement