
CMPC arriesga grado de inversión por proyecto Natureza en Brasil
Source: Bloomberg
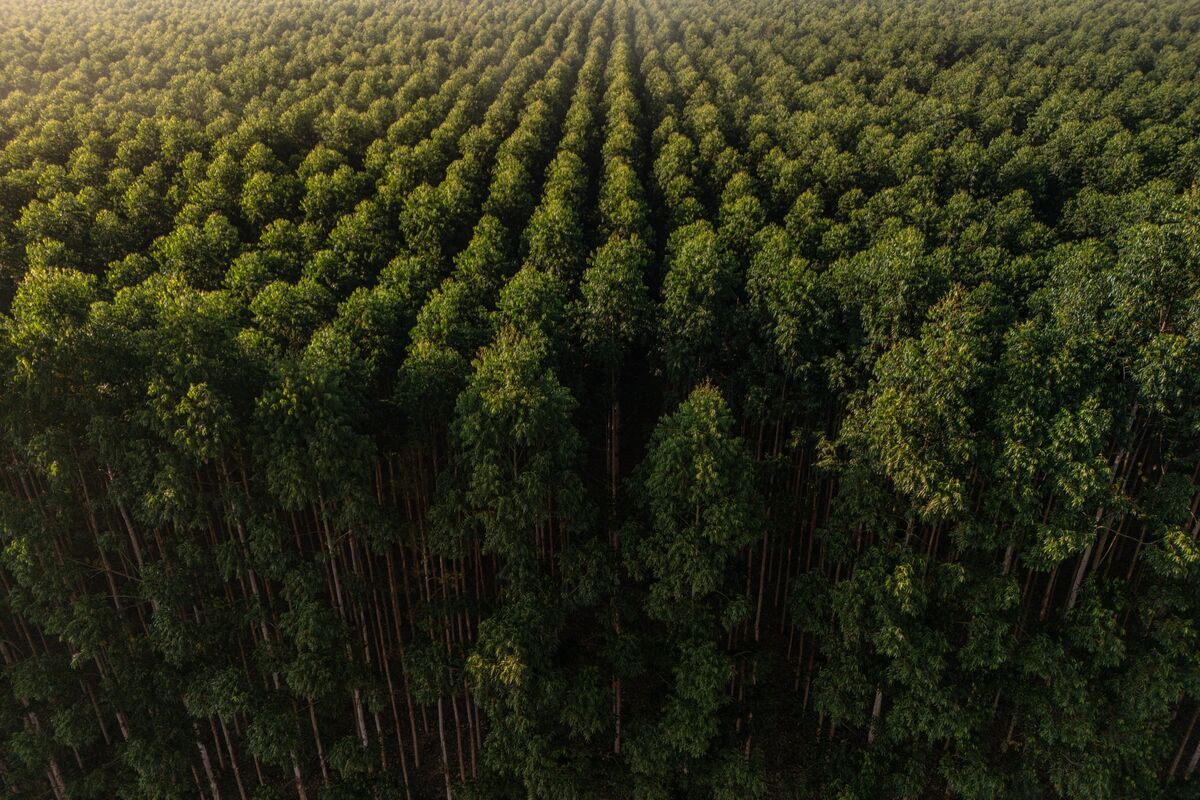
CMPC faces a choice over its US$4.6 billion Natureza pulp mill in Brazil, an investment nearly twice the company’s market value. Proceeding could put its investment-grade rating at risk as debt is already elevated and pulp prices are under pressure; shelving the project could leave CMPC behind industry rivals.
Analysis
The market is pricing a capital-allocation trade-off, not just a construction decision. If CMPC proceeds, investors may demand a higher credit-risk premium before incremental capacity contributes cash flow; the equity can also face a valuation overhang if funding relies on dilution. If it delays or shelves the project, near-term balance-sheet pressure eases, but competitors such as Suzano may gain relative positioning in pulp capacity. That is not automatically bullish for the sector: if Natureza proceeds into a weak pulp market, added supply could pressure prices and impair returns across producers.
In the next days, expect headline sensitivity around approval and financing; over 1–3 months, the key catalysts are a final investment decision, funding mix, leverage targets, and credit-rating commentary. Over 6–18 months, construction execution, pulp-price recovery, and eventual supply growth matter more than the announced project value. The contrarian point is that “falling behind” is not necessarily value-destructive: declining a large project could protect returns if expected pulp economics do not clear the cost of capital. The article provides no project economics, financing plan, or rating thresholds, so the investment-grade risk is a scenario, not an established outcome.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.30
Key Decisions for Investors
- Keep CMPC credit on a relative-value watch rather than shorting outright: consider underweighting its bonds versus comparable pulp issuers only if a firm investment decision arrives without credible funding and leverage guardrails. Verify maturities, covenants, rating-agency thresholds, and current spread valuation first.
- Avoid treating project delay as an automatic equity positive or proceeding as an automatic negative. Reassess after disclosure of expected returns, construction schedule, funding mix, and downside pulp-price sensitivities; these are necessary to judge dilution and credit risk.
- Monitor pulp prices and competitor capacity plans. A sustained pulp-price recovery alongside disciplined industry investment would weaken the bear case; weak prices plus multiple large capacity additions would strengthen it.
- Falsifiers: CMPC presents funding that preserves its stated credit metrics and rating outlook, or the project economics show robust returns under conservative pulp assumptions. Conversely, a rating outlook downgrade, materially weaker leverage guidance, or further pulp-price deterioration would raise the case for credit underweight.
More News
- Why Dangote’s Nigeria Refinery IPO Is Such a Big Deal for Africa
- Oman evacuates injured crew from attacked tanker in Strait of Hormuz
- Oil rises as concerns over Houthi attacks on Saudi Arabia eclipse supply recovery
- Australia top court rules against coal mine expansion, citing climate harm
- Diesel Price Surge Hits Farmers, Raising Food Inflation Risk
- Rebounding oil exports through Strait of Hormuz are vulnerable to stepped-up Iranian tanker attacks