
Hyundai Motor Company Executives Recognized for Leadership and Achievements in 2026 Automotive News All-Star Awards
Source: PR Newswire
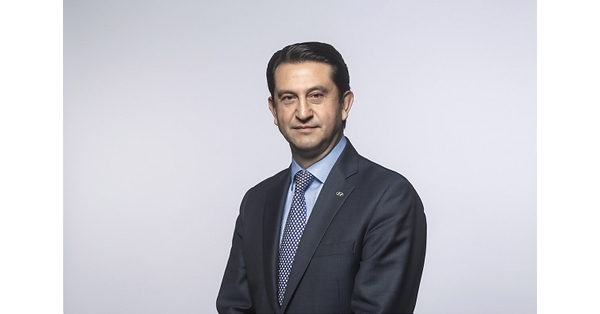
Hyundai Motor Company executives José Muñoz, SangYup Lee, and Claudia Márquez were named 2026 Automotive News All-Stars for leadership in design and U.S. business operations. The article highlights Hyundai Motor Group’s planned $26B U.S. investment (2025–2028) covering expanded vehicle production and a new Louisiana steel mill, alongside “five consecutive years of record” U.S. retail sales through 2025 and a stated shift toward ICE, EV, and hybrids. While primarily an industry recognition piece, the disclosed capex and sales momentum are modestly positive for Hyundai’s near-to-medium term outlook.
Analysis
This reads as a credibility signal for HYMLF, not a standalone earnings catalyst. The market only should care if the recognition reflects durable execution that shows up in U.S. unit share, dealer economics, and mix; otherwise it is just inexpensive corporate optics. The real mechanism is that a strong product/ops cadence can support pricing discipline in a softer auto tape, but the flip side is heavier fixed investment in plants and localization, which raises the penalty if demand rolls over.
GM is the cleaner relative loser if Hyundai’s North American push keeps taking share in the core profit pools: crossovers, hybrids/EVs, and eventually pickups. That matters because a small share shift in high-margin segments can move GM’s North America profit more than broad industry growth does. The Amazon/Waymo references are more about ecosystem validation than near-term revenue; any upside to AMZN or GOOGL is likely long-dated optionality around software, autonomy, or fleet integration, not something to underwrite this quarter.
Time horizon matters: the headline itself should fade fast, but the next 1-3 months are about monthly sales prints, incentive intensity, and whether Hyundai’s new product cadence holds share without margin dilution. Over 6-18 months, the key question is whether the U.S. investment translates into operating leverage or simply more capacity in an already competitive market. The thesis breaks if Hyundai’s U.S. retail growth slows while incentives rise, or if GM stabilizes share and margins at the same time.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- Tactical relative-value: long HYMLF / short GM on a 3-6 month horizon if Hyundai U.S. share data remains firm; target 10-15% relative outperformance, stop if GM North America margins reaccelerate or Hyundai incentives widen materially.
- Do not buy AMZN or GOOGL on this headline alone; treat the partner references as option value only and wait for a disclosed commercial revenue stream or shipped product before underwriting any P&L impact.
- Set a watch item on HYMLF rather than a chase: if U.S. monthly sales and mix improve for 2 consecutive prints, use any 3-5% pullback to build a small long; if not, treat the move as sentiment-only and stay flat.
- For event-driven traders, consider a conservative call spread on HYMLF only ahead of the next U.S. sales update; the risk/reward is acceptable only if sizing reflects low conviction and limited liquidity in the ADR.
More News
- TSMC chip capacity is ‘fierce’ battleground for AI customers, amid record quarter
- Nvidia’s European spending spree is about much more than Europe
- Here's our monthly update on our 32 stocks, including 2 more names to buy
- VW Wants to Take On Wrangler and Bronco on Their US Home Turf
- Cost of AI default insurance spikes as data centre confidence wobbles
- AWS, Anthropic race to deploy army of specialized engineers key to proving AI spending will pay off