
HONDA CENTER KICKS OFF 2026-27 SEASON WITH EXCITING NHL SCHEDULE, HIGHLY ANTICIPATED CONCERTS, NEW FOOD & BEVERAGE, AND CONTINUED ARENA UPGRADES AHEAD OF OCVIBE OPENING SPRING 2027
Source: PR Newswire
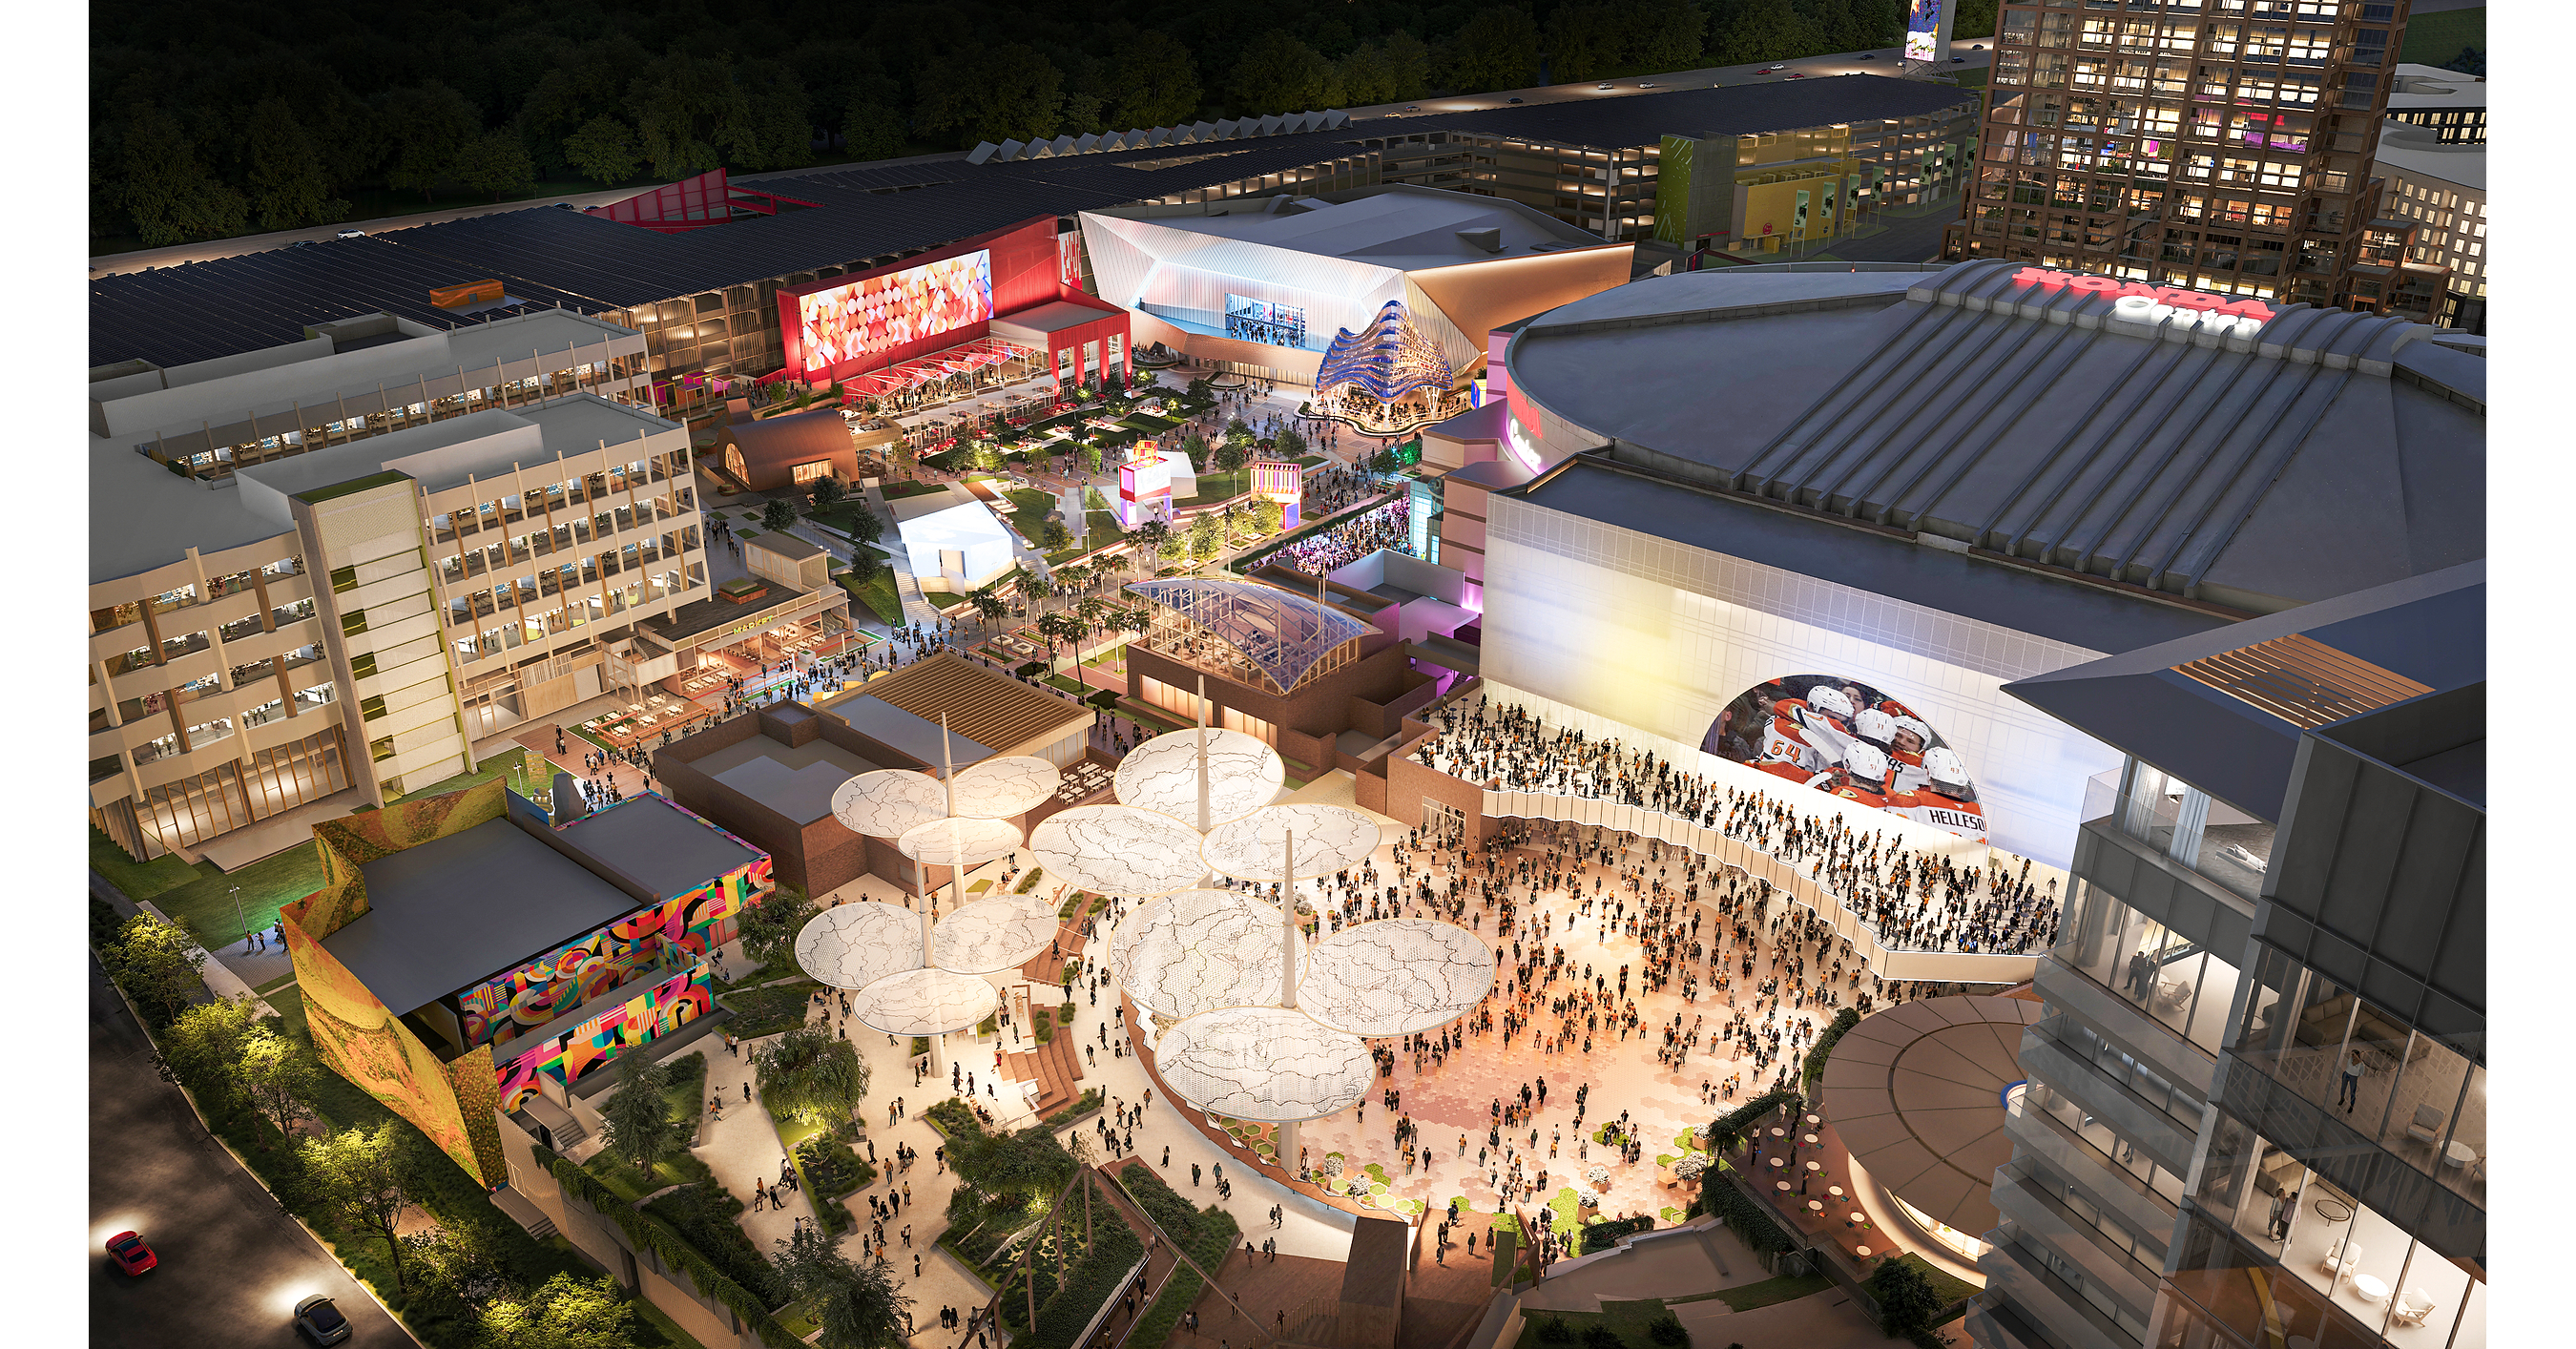
Honda Center is continuing its privately funded $1 billion Encore renovation through 2027 while the Samueli family’s $5 billion, 100-acre OCVIBE mixed-use district begins its first phase opening in early 2027. Phase 1 will include a 5,000-capacity concert hall, the 50,000-square-foot Katella Commons market hall, public spaces and The Weave office building; the full development is targeted for completion in 2033 with more than 2,000 residences, 35+ dining venues and three entertainment venues. The upgrades expand the arena’s premium offerings, food and beverage program, and event calendar, positioning the site as a year-round Orange County entertainment destination.
Analysis
This is not a material earnings driver for any listed issuer in the data set; the relevant read-through is confirmation that premium live-event venues are shifting spend toward higher per-capita monetization rather than relying solely on attendance growth. STZ and TAP can benefit at the margin where branded placements secure pour rights and high-traffic visibility, but one venue is immaterial relative to their US beer portfolios; the more investable question is whether this model signals sustained strength in on-premise consumer spending through 2027.
DAKT has the clearest, albeit still small, revenue linkage. Large-format display installations have attractive project economics but lumpy revenue recognition and often carry lower visibility than recurring software/service revenue; investors should not extrapolate a single branded screen into a bookings inflection without evidence of broader sports-and-entertainment order growth. The meaningful 6-18 month second-order effect is competitive pressure on nearby Anaheim hospitality and retail, while mature destination districts such as MSGE's Las Vegas assets and certain local hotel operators face little direct substitution.
The contrarian view is that the development narrative can overstate incremental demand: much of spending may be diverted from other Orange County entertainment and dining outlets, while construction disruptions and a weaker discretionary consumer could delay tenant ramp and premium-seat utilization. For beverage suppliers, the key falsifier is not venue traffic but whether on-premise mix, depletion growth, and pricing hold up in quarterly disclosures; promotional drink pricing can lift volume while diluting venue-level profitability.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Ticker Sentiment
Key Decisions for Investors
- No standalone position in DAKT, STZ, TAP, or KMB on this announcement. Set a DAKT watch alert for a disclosed entertainment-venue order or a sustained acceleration in commercial-systems backlog; only consider a long if backlog conversion supports upward FY revenue guidance, as the current information has insufficient scale.
- Maintain any existing STZ overweight only if US beer depletion growth and gross-margin guidance remain intact over the next 1-3 months. Treat incremental venue activations as brand-supportive rather than an EPS catalyst; trim if beer depletions decelerate while promotional spending rises.
- For TAP, use upcoming US beer volume and pricing data as a relative-value signal versus STZ: a long STZ/short TAP pair remains preferable only if premium/import on-premise share continues gaining. Exit the pair if TAP demonstrates sustained volume stabilization without incremental discounting.
- Avoid drawing an investment conclusion on BA or HMC: their references are branding/location context with no identifiable revenue, procurement, or demand transmission mechanism.
More News
- Boeing beats Northrop to build the US Navy’s $20bn F/A-XX fighter
- Boeing Adds Navy’s Sixth-Generation Fighter to Its Roster
- Boeing was at risk of losing all fighter-jet production altogether. Now the stock is up on a new Navy contract.
- Why is Boeing stock rallying today?
- Nvidia is approaching a breakout level. Plus, what we want to see from Micron
- Boeing stock rises on $20B US Navy contract; UBS says selloff gone too far
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Software for Buy-Side Teams: Build the Research Stack
- Augmented Intelligence: AllMind, Elevate Human Judgement With an Accessible, Powerful, Data-Driven Financial AI Toolkit