
Kane Biotech Expands Canadian Commercial Reach with Ontario Medical Supply Inc.
Source: globenewswire.com
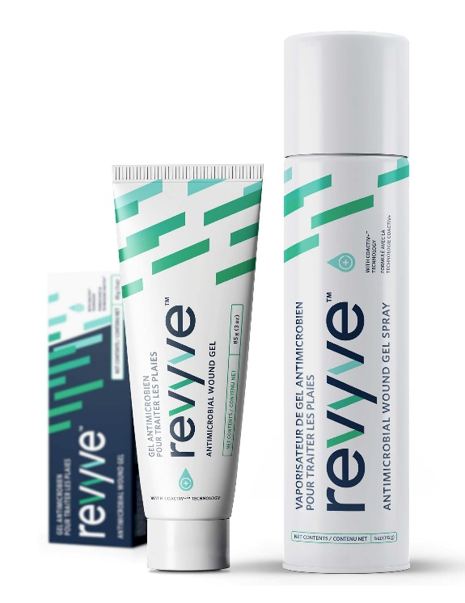
Kane Biotech announced a non-exclusive distribution agreement with Ontario Medical Supply Inc. (OMS), an Ottawa-based distributor serving Canada. The deal expands Kane’s distribution reach in the Canadian market, but provides limited financial detail, implying modest near-term impact.
Analysis
This looks more like a commercialization checkpoint than a fundamental inflection. A non-exclusive channel adds reach, but it also tells you the product still needs borrowed distribution rather than winning shelf space on its own; that usually means the market should haircut near-term revenue visibility and focus on sell-through, reorder rates, and gross margin after distributor discounts.
The real second-order effect is on working capital and operating leverage: if OMS takes inventory, Kane can get a temporary cash-flow lift and better line-of-sight into Canadian demand, but only if returns are low and the distributor actually pushes the product. If adoption is weak, the agreement becomes cosmetic and may even compress gross margin once channel incentives are layered in. For competitors, the more relevant threat is not immediate share loss but a small validation signal that could force adjacent wound-care or specialty-care vendors to defend the same distributor shelf space.
Time horizon matters: the stock could react for days on headline optics, but the business impact likely won’t be testable for 1-3 quarters. The main falsifier is a lack of sequential revenue acceleration, no mention of meaningful initial purchase orders, or any need for financing that offsets channel expansion. In that scenario, the agreement should be treated as a low-conviction marketing event rather than evidence of durable demand.
Contrarian view: the consensus may be overstating the signal quality because distribution announcements in microcap medtech are often used to imply momentum without proving demand. If the market bids the name on this alone, that strength may be fadeable unless management later quantifies order size, repeat cadence, and contribution margin.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No immediate position in KNBIF; wait 1-2 quarters for disclosed sell-through, reorder cadence, and gross margin before underwriting any real revenue impact.
- If KNBIF rallies >10-15% on the announcement without order-size disclosure, consider fading the move with a tight risk budget; the setup is more optics than earnings.
- Set an alert on the next quarterly filing for sequential Canadian revenue growth and operating cash burn; a positive surprise there would be the first credible confirmation of channel value.
- Only consider a starter long if management later shows distributor-led revenue inflection and no incremental dilution; otherwise the risk/reward is poor for a microcap with limited channel control.
More News
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Apple’s $1,999 iPhone Duo puts the company's status-symbol power to the test
- Kimberly-Clark is having its best week in four years. Here's what is propelling shares higher