
TCL umacnia swoją pozycję na rynku smartfonów, prezentując serię P80 na targach IFA 2026
Source: PR Newswire
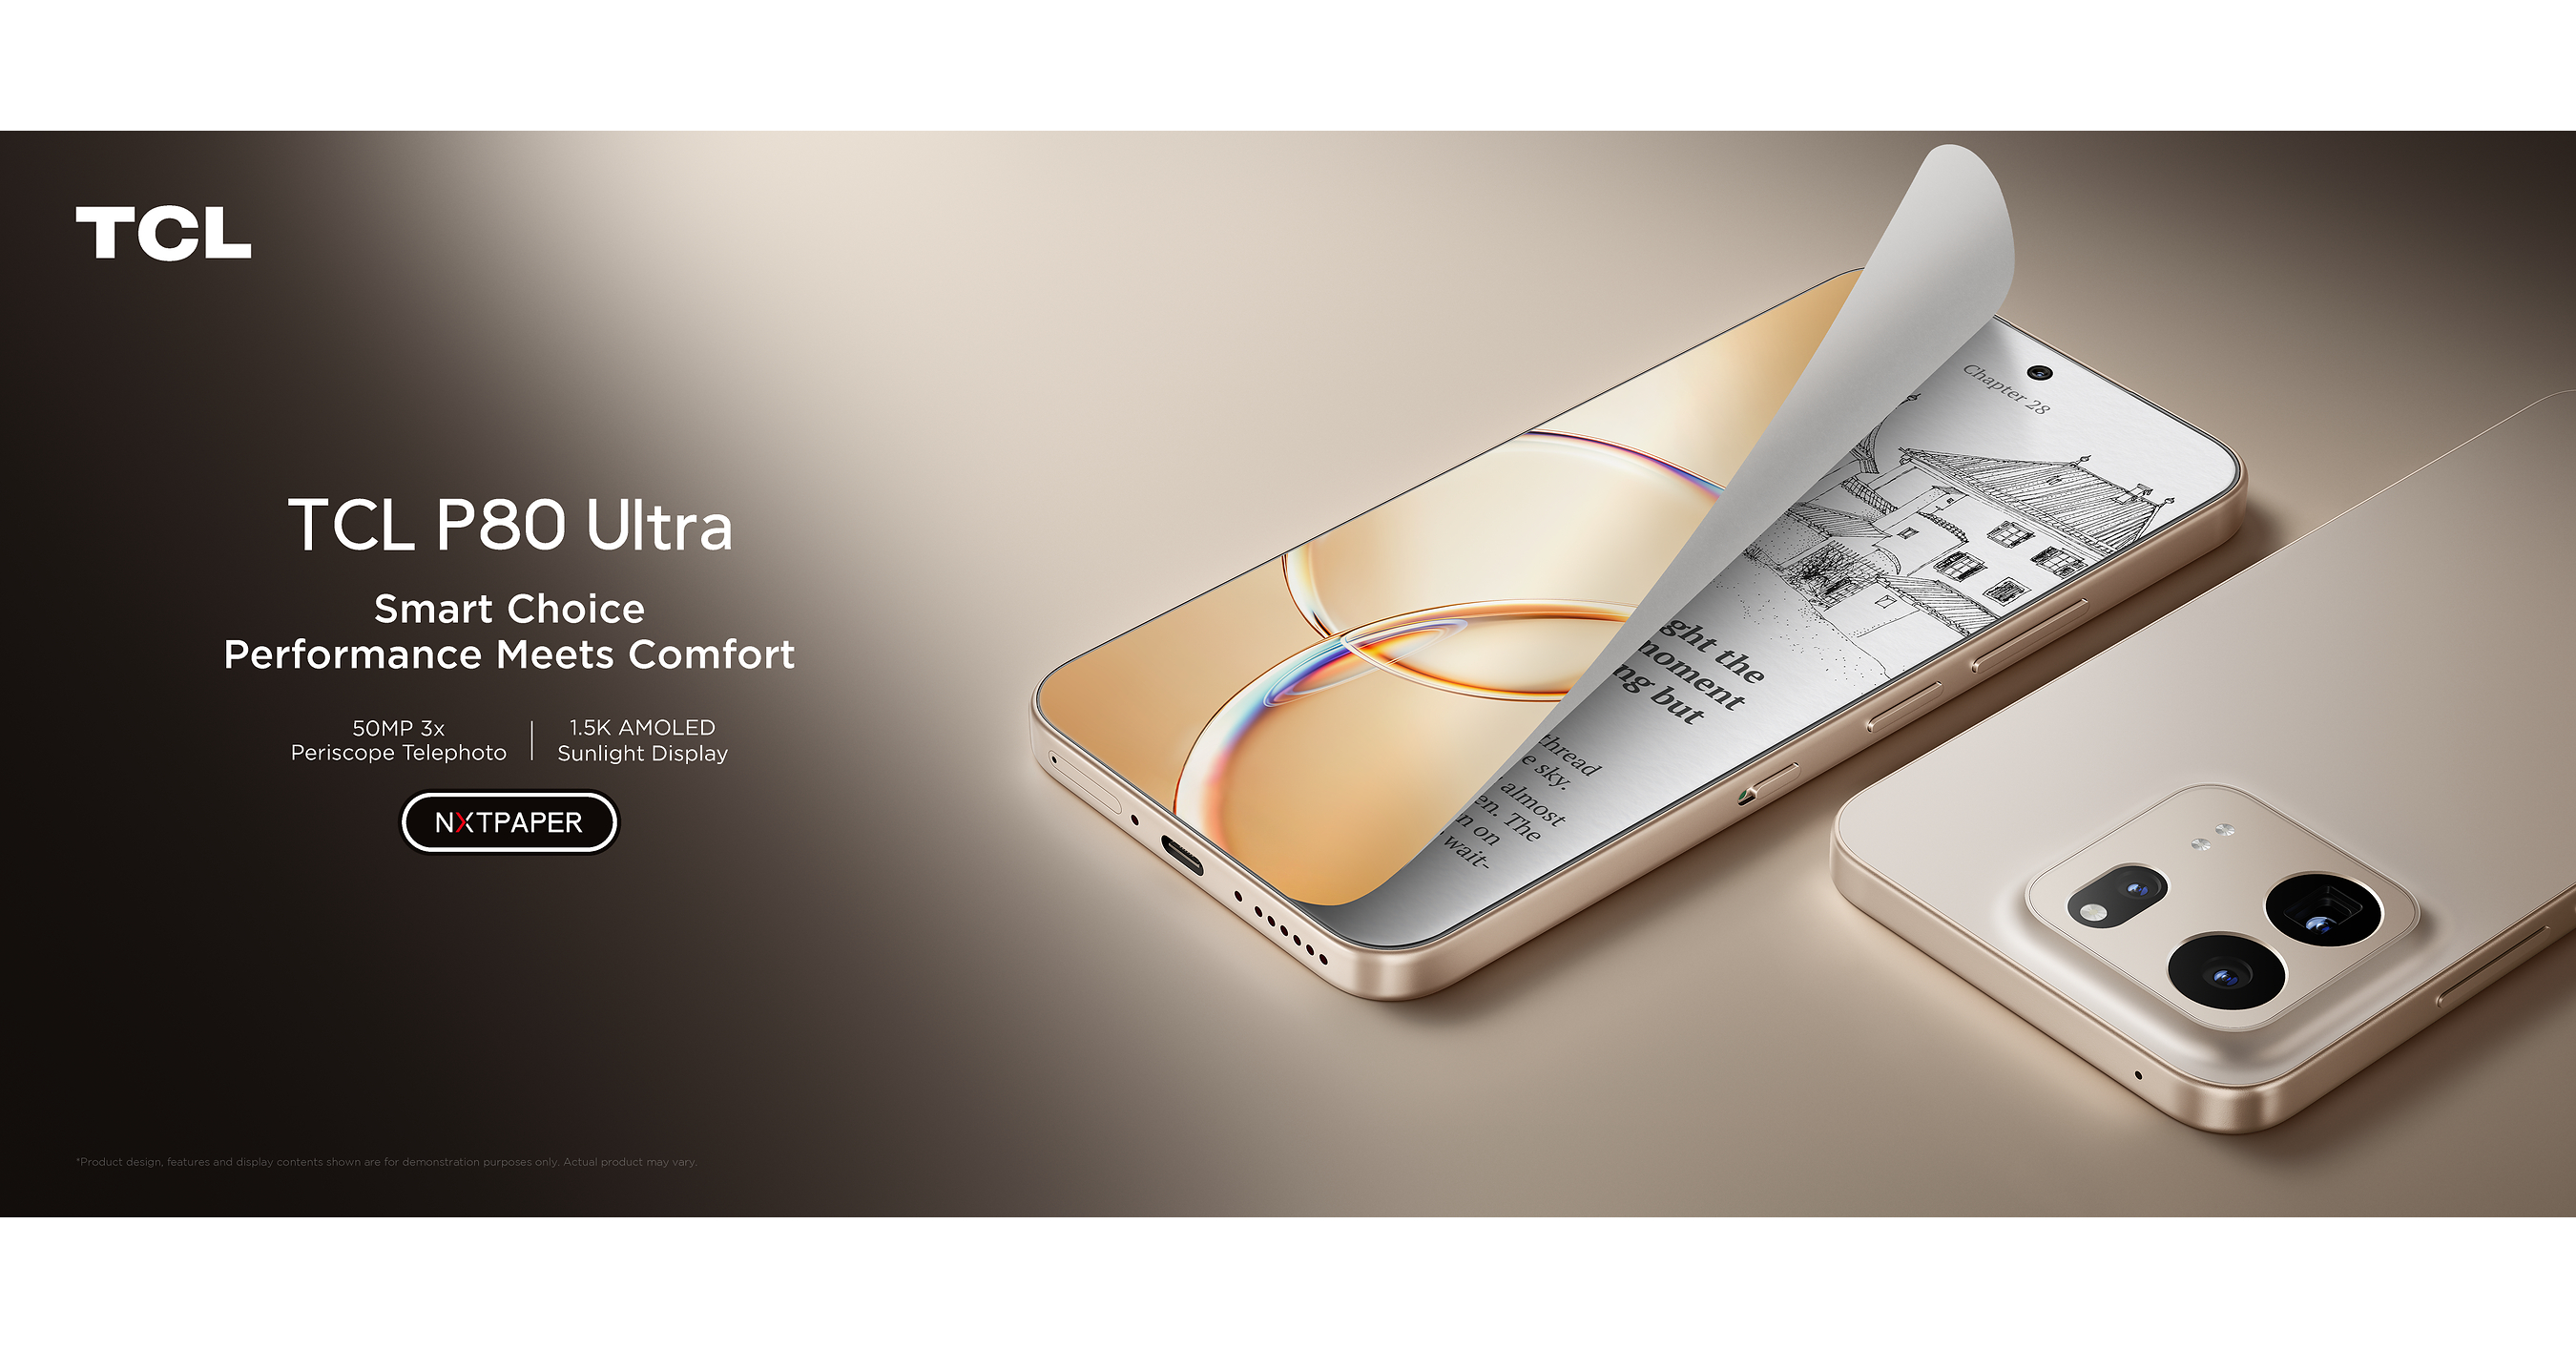
TCL zaprezentował na IFA 2026 serię smartfonów P80 (P80 Ultra, P80 Pro, P80) z nowym wyświetlaczem NXTPAPER AMOLED ograniczającym odblaski i ekspozycję na światło niebieskie. P80 Ultra wyróżnia się peryskopowym aparatem 50 MP z 3-krotnym zoomem optycznym (OIS + EIS), a P80 Pro oferuje NXTPAPER AMOLED 1,5K oraz baterię 5800 mAh i do 512 GB pamięci. To przede wszystkim komunikat produktowy wzmacniający pozycjonowanie TCL w segmencie premium, bez wskazania wpływu finansowego na wyniki.
Analysis
This is mostly a positioning signal, not a near-term P&L event: TCL is trying to move upmarket without a commensurate proof point in ecosystem lock-in, software, or carrier pull. The first-order read is mildly negative for the mid-tier Android shelf because any incremental feature set that borrows from premium devices forces rivals to spend more on promo, trade-in, and channel incentives to defend share. The more important second-order effect is margin compression: in a market where specs are easy to copy, premium claims often translate into higher BOM and marketing cost before they translate into higher ASPs.
Over 1-3 months, the key catalyst is not the launch itself but whether European carriers and large retailers give TCL meaningful distribution. If sell-through does not accelerate, this becomes inventory noise and a brand exercise; if it does, the pressure lands on Xiaomi (1810.HK), Samsung’s A-series, and other value-premium Android names that compete on the same ‘good enough, but cheaper’ buyer. The feature mix also nudges the category toward display differentiation rather than camera-only differentiation, which is mildly supportive for component vendors if it drives replacement cycles, but that benefit is likely diluted because TCL is pushing its own display story.
Contrarian view: the market may be underestimating how little handset launches matter for sub-scale OEMs absent a services layer, carrier subsidies, or a meaningful OS wedge. The bigger risk is that TCL spends into premium optics and ends up widening losses rather than taking share. I would not chase this as a standalone long; it becomes actionable only if channel checks show TCL gaining durable shelf space or if peers guide to tougher promotions in EMEA.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No direct trade in TCL; treat this as competitive noise unless channel checks show sustained carrier placement or inventory draw-down in Europe over the next 1-2 quarters.
- Set a watchlist short on Xiaomi (1810.HK) only if European Android promo intensity rises; the risk/reward works better as a relative-value trade than an outright short because handset launches usually fade unless backed by distribution.
- If sell-through data confirm TCL share gains, pair long 005930.KS on any pullback vs. short 1810.HK to express a quality-vs-value Android differentiation trade; thesis is that premium execution wins more margin than spec-sheet imitation.
- Falsifier: if TCL does not materially expand carrier/retail footprint by the next earnings cycle, abandon any bearish read on peers—the launch is then just brand maintenance, not a share-shift catalyst.
More News
- Bending Spoons wants to revive software castoffs. Berkshire is backing the plan
- AI rapidly improving, could vastly boost U.S. GDP, Anthropic's Clark tells policymakers
- ‘How many canaries have we killed in the coal mine?’ — Wall Street debates if the latest AI bubble warnings are another head fake or the real thing
- Semiconductor market to remain solid ‘at least through next year,’ South Korea finance minister says
- Nasdaq Index: AI Selloff Deepens as Chips and CoreWeave Break
- Alphabet’s chief investment officer responds to Jefferies warning that the most likely outcome of the AI boom is massive U.S. capital destruction
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework