
XCMG Breaks Ground on Its First Overseas Base for Mining Equipment Component Overhaul and Remanufacturing in Indonesia
Source: PR Newswire
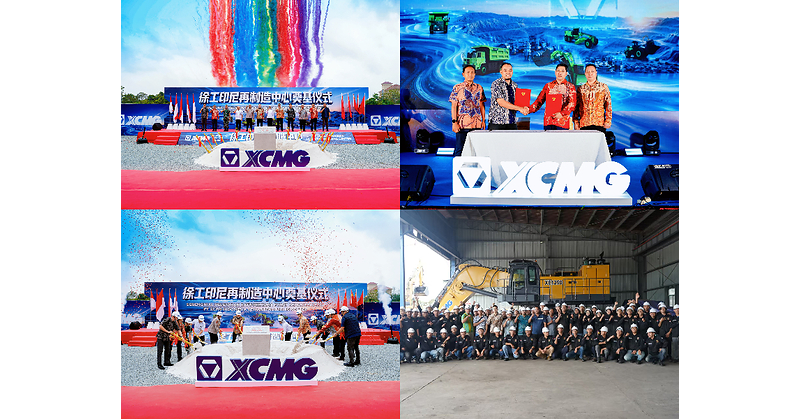
XCMG broke ground on its first overseas mining-equipment component overhaul and remanufacturing center in Balikpapan, Indonesia, expanding its localized aftermarket capabilities. The facility will provide component remanufacturing, parts warehousing, technical training and used-equipment refurbishment, aiming to reduce downtime and operating costs for Indonesian mining customers. The investment follows XCMG's recent Indonesia financing-company launch, new-energy manufacturing base commissioning and local R&D center inauguration, extending its full-lifecycle equipment-services strategy.
Analysis
This is strategically more important than a single service-site announcement: bundling local financing, equipment supply, parts, refurbishment and remanufacturing lowers the buyer's effective switching option. For Indonesian mining contractors, a shorter repair cycle reduces the working-capital and production-risk penalty of adopting Chinese equipment, which can shift procurement from upfront-price comparisons toward fleet total-cost-of-ownership. The likely pressure falls first on premium OEM aftermarket pools—Caterpillar (CAT), Komatsu (KMTUY) and Volvo Construction Equipment parent Volvo AB (VLVLY)—where parts and rebuilds typically carry materially higher margins than new equipment.
Near term, this is unlikely to move listed global OEM estimates because the project has no disclosed capacity, capex, commissioning date or contracted fleet base. Over 6-18 months, however, local remanufacturing can make XCMG bids more credible in large Indonesian coal, nickel and infrastructure tenders, especially if captive financing is used to subsidize initial fleet acquisition. The second-order risk is a lower residual value for incumbent OEM fleets if an expanding Chinese used-equipment/refurbishment channel creates a cheaper secondary-market alternative.
The consensus may overstate the immediate threat to CAT: mine operators will not rapidly migrate critical fleets without demonstrated component reliability, parts-fill rates and financing discipline. The key falsification for a competitive-loss thesis is evidence that XCMG's localized network fails to convert into tender wins or materially improves only service cost rather than machine uptime. Monitor Indonesian heavy-equipment unit sales, mining-capex awards, CAT/KMTUY regional dealer commentary, and any disclosed local credit-loss metrics from XCMG's finance platform over the next two reporting cycles.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No standalone directional trade on this release; XCMG is not an accessible listed vehicle and disclosed economics are insufficient to underwrite an earnings impact.
- Place a 6-12 month watch on CAT and KMTUY Indonesian/ASEAN aftermarket commentary: initiate a relative short CAT versus long a diversified industrial only if management cites competitive pricing, lost mining tenders, or aftermarket-margin pressure attributable to Chinese OEM localization.
- For Indonesia-exposed mining operators, monitor United Tractors (UNTR.JK) and Astra International (ASII.JK): local service competition can pressure their equipment-distribution economics, but only consider a short after verified deterioration in Komatsu unit share, parts gross margin, or dealer inventory turns.
- Treat XCMG-linked financing as the highest-risk variable: a rapid increase in financed unit sales without transparent delinquency and residual-value disclosure would be a credit-cycle warning, not confirmation of sustainable market-share gains.
More News
- Saudi Oil Cuts Tied to War Hit Europe: Evening Briefing Americas
- Houthis accuse Saudi Arabia of launching 26 strikes in 24 hours
- Warren Buffett stepping down as chairman of Berkshire Hathaway: 'Father Time always wins'
- After threatening to seize Greenland by force, Trump agrees to leave it with Denmark and boost military presence. ‘We will be very protective of it!’
- European Oil Supply Pressure Mounts After Saudi Cuts
- Oman oil escape route: How ship-to-ship transfers work — despite big risks