
OMAHA STEAKS UNVEILS BUSINESS TRANSFORMATION AND NEW "NO BULL" BRAND PLATFORM, DOUBLING DOWN ON VALUE AND TRANSPARENCY
Source: PR Newswire
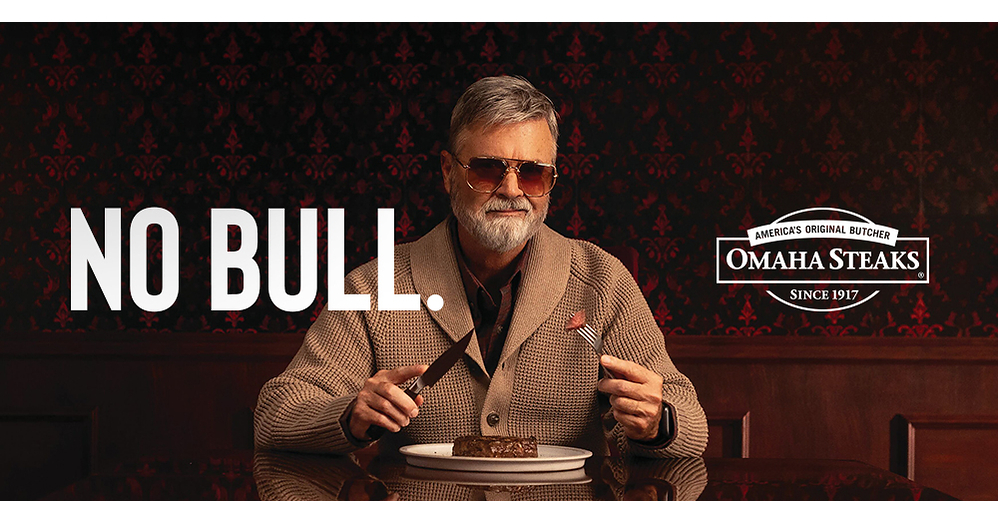
Omaha Steaks unveiled a business transformation centered on premium proteins, 100% U.S.-sourced beef, expanded customizable offerings and its new "No Bull" marketing platform. Investments in retail and fulfillment have cut average delivery time to two days from more than six days in early 2025, enabling same-day and next-day delivery for more customers. The 109-year-old private company is targeting younger urban consumers and busy families through expanded omnichannel marketing, while broadening its protein assortment with products such as parmesan-crusted chicken nuggets.
Analysis
This is not directly investable because Omaha Steaks is private, and the release provides no store count, fulfillment capex, order-frequency, customer-acquisition-cost, or gross-margin data. The relevant public read-through is that premium-food e-commerce is converging toward local inventory and rapid fulfillment, raising the fixed-cost hurdle for national direct-to-consumer peers. SHAK, CAVA and grocery operators with dense physical networks have an embedded advantage in convenience; pure-play shipped-food models face higher pressure to subsidize freight and reduce delivery windows.
The U.S.-sourced positioning marginally improves domestic beef-demand visibility, but it is not automatically bullish for cattle exposure: a premium marketer can absorb higher input costs only if its pricing power and gifting demand hold. TSN and HRL could benefit at the margin if branded protein demand broadens beyond beef, while large processors such as JBS and CARGILL-linked private supply chains retain more bargaining power than downstream marketers. The more meaningful second-order effect is demand for regional cold-storage and last-mile capacity, where capacity utilization—not campaign messaging—will determine whether faster delivery is margin accretive.
Over the next 1-3 months, this is primarily a competitive signal rather than an earnings catalyst for public equities. The thesis becomes actionable over 6-18 months only if incumbents report rising online grocery/meal-category growth without a corresponding deterioration in fulfillment expense, gross margin, or promotional intensity. A weakening consumer, elevated cattle prices, or evidence that expedited shipping is being funded through discounting would invalidate the premium-convenience narrative.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No standalone trade on the release; place an earnings watch on KR, WMT and COST for online grocery growth, fulfillment-cost commentary and premium fresh-food mix over the next two reporting cycles.
- Maintain a relative preference for COST over direct-to-consumer premium-food concepts: membership economics and store density better absorb cold-chain and last-mile costs. Reassess if Costco food gross margin compresses materially or renewal trends weaken.
- Watch TSN and HRL for evidence of sustained branded protein volume growth versus price-led revenue. Do not add on this signal alone; require volume acceleration and stable input-cost guidance before treating it as a demand catalyst.
- For logistics exposure, monitor COLD and GXO rather than initiate immediately: a long is warranted only if cold-storage occupancy/pricing or contract-logistics volumes improve while capital intensity remains contained. Rising warehouse capex without utilization gains is the key falsifier.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Sudan’s soaring fuel prices make getting by harder for workers
- Nvidia's role as AI financier faces first big test as neoclouds take market hit