
HUMAIN Collaborates with Compal to Drive Cloud-to-Edge AI Expansion, Showcasing Partnership at LEAP 2026
Source: PR Newswire
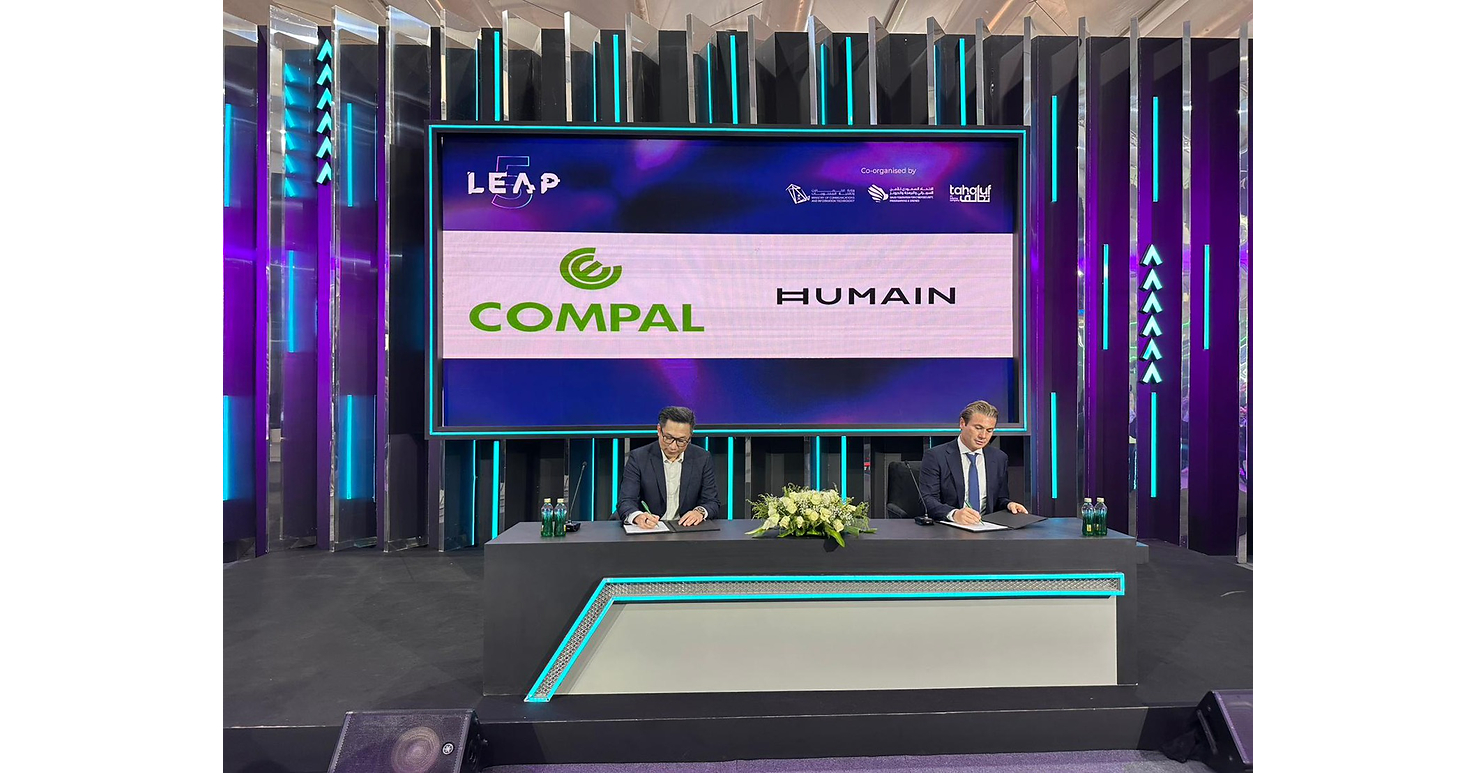
HUMAIN (PIF-backed) selected Compal Electronics as a long-term strategic ODM partner to develop and manufacture next-generation AI infrastructure spanning cloud AI, edge computing, and “Physical AI,” with a roadmap for successive AI server generations. The partnership highlights NVIDIA- and AMD-based AI server platforms and includes AI PC initiatives plus Compal’s PolyMedX physical AI for smart-hospital use (via NVIDIA Agent-Ready Rheo Blueprint). The collaboration is showcased at LEAP 2026; impact is likely more incremental/strategic than immediate for markets.
Analysis
This is less a single-order revenue event than a signal that sovereign AI buyers are moving toward multi-vendor, ODM-led procurement. That structure is modestly supportive for both NVDA and AMD because it pulls forward platform qualification and increases the odds of repeated server refreshes, but the incremental edge is probably stronger for AMD: diversified buyers often want a second source to reduce CUDA lock-in and negotiating leverage. In the next 1-3 months, the stock reaction should be driven by whether this turns into named capacity or backlog; absent that, it is mostly narrative alpha.
The second-order effect is margin mix. An ODM-centric deployment model usually shifts value away from pure silicon pricing toward integration, thermal, and deployment services, which can broaden the market but lower the purity of the gross-margin expansion story. That matters because the upside case for the AI complex is often priced as if every sovereign build looks like hyperscale cloud; if these programs are more customized and slower to scale, the revenue ramp is real but the earnings conversion is more gradual over 6-18 months.
The contrarian risk is that investors overread a press-release partnership as committed capex. The thesis is falsified if neither NVDA nor AMD shows better datacenter commentary in the next two earnings cycles, or if the regional AI build-out stays at demo stage without purchase orders. If there is follow-through, the cleaner expression is relative-share gain for AMD rather than a broad beta trade in the AI basket.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Small tactical long AMD / short NVDA pair for 1-3 months: thesis is sovereign AI buyers' preference for vendor diversification; target modest relative outperformance, stop if NVDA re-accelerates datacenter guidance or AMD fails to show channel confirmation.
- Do not chase NVDA outright on this headline; wait for evidence of actual orders or raised datacenter commentary. Treat as a watch item for the next two earnings prints, not an immediate conviction long.
- If AMD sells off with the broader AI complex, use a 3-6 month call spread instead of stock for defined risk; the payoff is strongest if this partnership is one of several sovereign AI wins, weak if it remains promotional.
- No actionable read-through for TSCC or WWRL from the current disclosure; avoid forcing a trade until there is evidence of direct supply-chain exposure or contract flow.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Taiwan to curb AI chip sales to China for more U.S. alignment- Bloomberg
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- Suddenly, Wall Street is worried that the U.S. economy is more ‘vulnerable’ than it looks
- TSMC chip capacity is ‘fierce’ battleground for AI customers, amid record quarter
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations
- Selecting an AI Research Platform for Institutional Investors