
STRATEGIC PARTNERSHIP WITH CARESTER FOR OXIDE SEPARATION DEVELOPMENT AND 10-YEAR OFFTAKE AGREEMENT
Source: PR Newswire
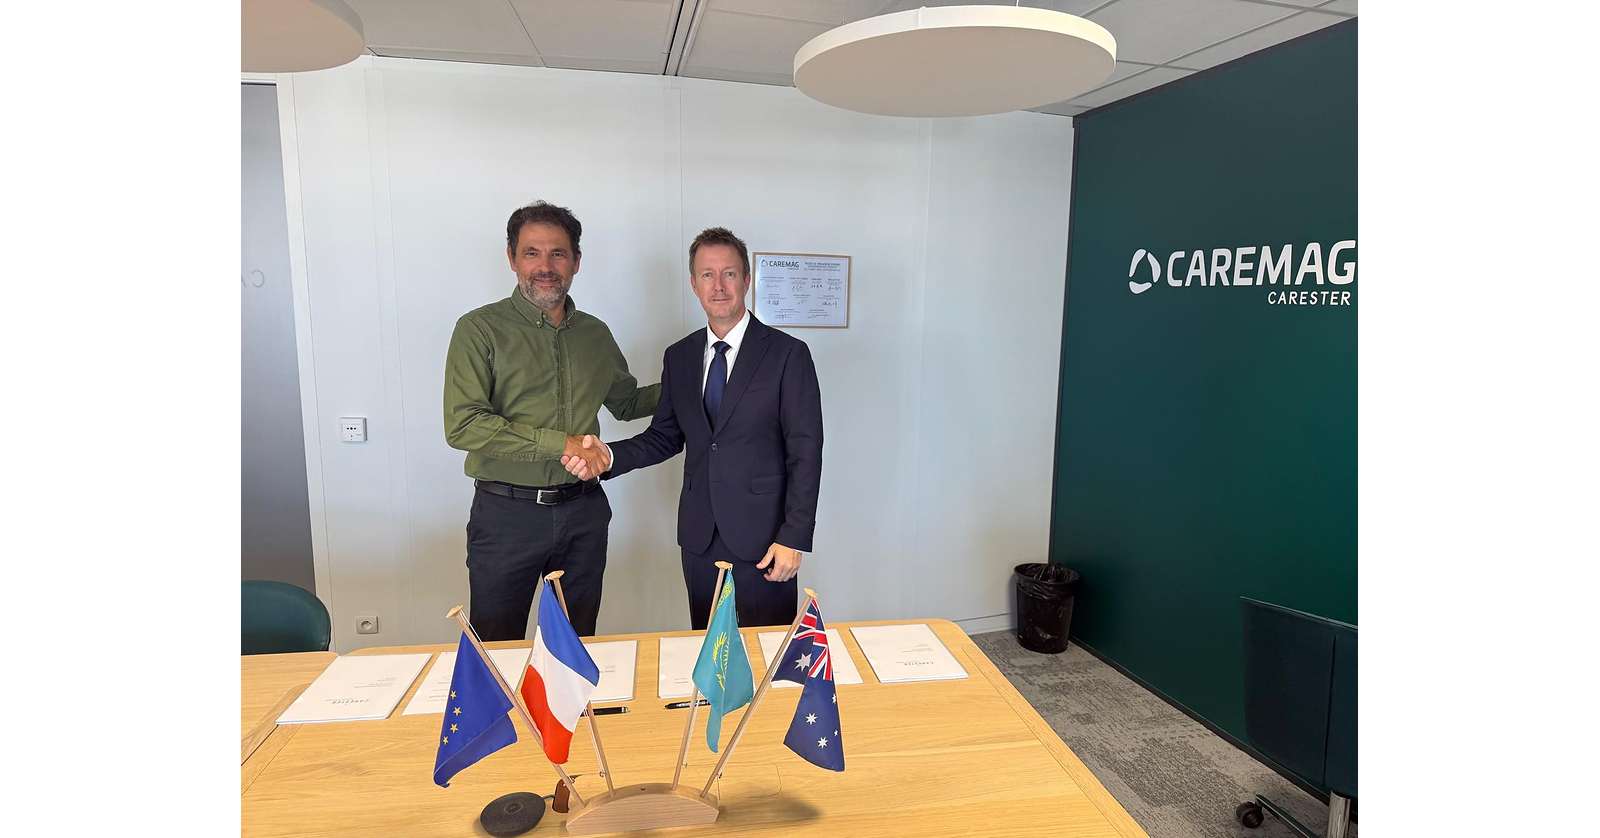
Lindian Resources entered a binding partnership with Carester for an 8,000tpa rare-earth oxide (REO) solvent extraction and oxide separation facility at Stepnogorsk, Kazakhstan, with DFS targeted for completion by end-2026 and first production in Q4 2026. The company secured a long-term offtake for up to 20 years covering 70% of SEGH volumes and RoFR on >70% of MHREC volumes, with pricing linked to Carester realized prices and potential government floor prices for magnet oxides (notably Dy, Tb, and Y). The Caremag refinery in France is supported by €216m in French/Japanese funding, reinforcing a long-term route to market for higher-value separated oxides.
Analysis
This is more important as a financing and credibility step than as near-term earnings news. The main market mechanism is a lower discount rate on downstream rare-earth optionality: a binding buyer, sovereign-adjacent support, and a named separation partner make the project look bankable enough to justify a higher multiple on resource optionality, even before a single oxide kilogram is sold. That said, the value creation is still largely back-end loaded; the equity should only rerate if the DFS shows capex intensity and recoveries are good enough to keep the build inside internal funding capacity.
For the ecosystem, the immediate beneficiary is the rare-earth separation theme rather than one isolated name. Western magnet-chain investors will read this as evidence that non-China oxide capacity can be assembled through government-backed industrial policy, which should be constructive for de-risked peers like MP Materials and the broader critical-minerals engineering complex. TTEK gets a small, low-beta backlog signal from DFS work, but this is not a material earnings driver; the bigger effect is reputational, positioning it for more critical-minerals advisory mandates.
The risk is execution, not demand. The next 1-3 months are about DFS disclosure, capex, reagent/power assumptions, and whether the internal-funding claim survives scrutiny; over 6-18 months the real test is commissioning and product qualification. The contrarian read is that the market may be overpaying for offtake optics: strategic buyers will sign paper early, but if Dy/Tb/Y recovery assumptions or Kazakhstan build costs disappoint, the equity can still dilute hard. What would falsify the thesis is a DFS that implies materially higher capex, a financing gap, or a delay that pushes first production beyond the current schedule by more than two quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- Speculative long IWTNF only on pullbacks after the announcement-driven pop; this is a 3-6 month catalyst trade into DFS and commissioning updates, not a fundamentals hold. Thesis breaks if DFS capex/recovery metrics come in weak or if financing requires dilutive equity.
- Do not chase TTEK on this headline. Treat it as a watch item only: the incremental DFS/engineering revenue is too small to move the model, so any long should be based on broader infrastructure/critical-minerals backlog, not this project alone.
- Use MP Materials as the cleaner public-market beneficiary if you want sector exposure to non-China rare-earth separation credibility. Prefer a medium-term long on weakness; upside is a modest multiple rerating if the market starts pricing Western strategic-chain scarcity, but stop out if rare-earth sentiment fades after the next DFS print.
- If you want a more defensive expression, pair long de-risked rare-earth exposure against short a basket of pure exploration names with no downstream route-to-market. The thesis is that capital will reward integrated, offtake-backed assets over paper resources over the next 6-12 months.
- Set an alert for the DFS release and any capex number that exceeds internally fundable levels; that is the key falsifier. If capex or schedule slips materially, take profits quickly because the current announcement premium is likely to compress back to optionality value.
More News
- Gold steadies after sharp drop as hotter PPI lifts Fed hike bets
- Stock futures are little changed as key consumer inflation report looms ahead: Live updates
- Iran war live: IRGC attacks US unmanned vessel in Hormuz; two ships hit
- Trading Day: Inflation palpitations
- Microsoft AI Focused Data Center Plan to Add 26 Gigawatts of Compute
- U.S. stock futures steady with CPI on tap; Oracle firms on strong earnings