
Princess Cruises Sets the Stage for Extraordinary Discovery Down Under in 2028-29
Source: PR Newswire
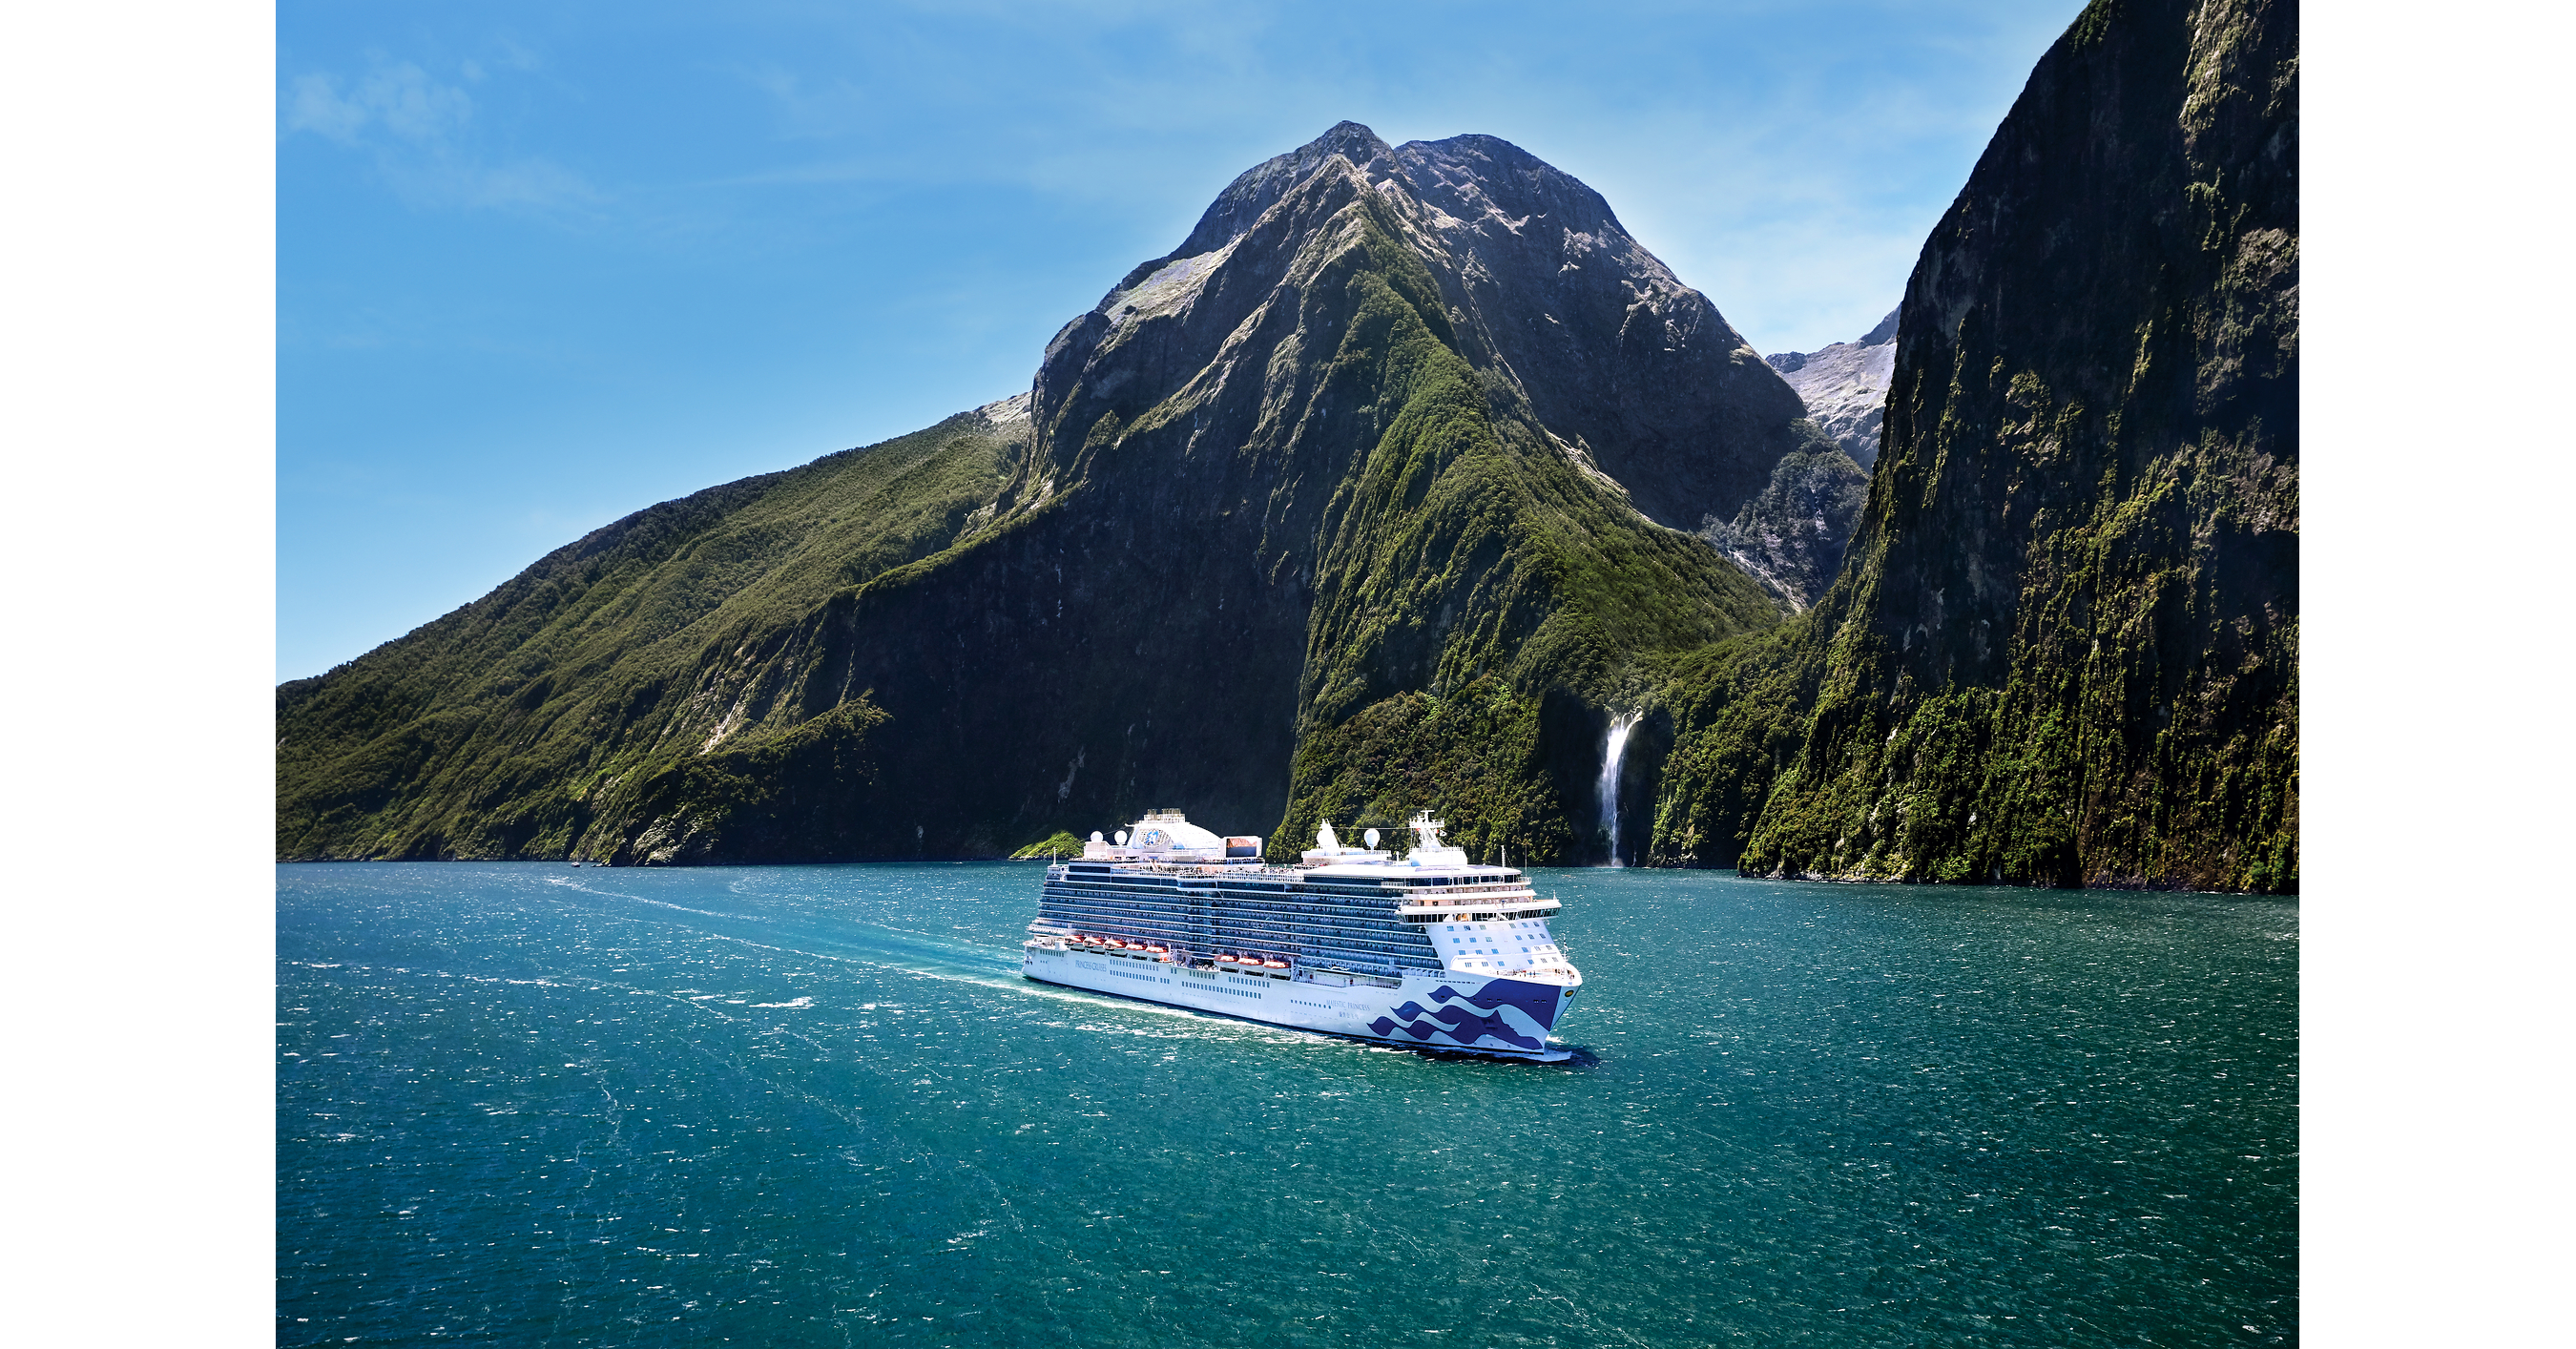
Princess Cruises announced its 2028–29 Australia and New Zealand season, with more than 90 departures across 70-plus itineraries, and the 2029 Grand World Odyssey, a 129-night roundtrip cruise from Australia visiting 61 destinations in 31 countries. Voyages go on sale November 10, 2026; promotional booking offers run through February 16, 2027.
Analysis
The announcement is a modest demand signal, not evidence of incremental earnings: the voyages are nearly two years away, and launch promotions could support early deposits while diluting realized fare or onboard spending. For CCL, the key read-through is the booking curve and net yield after incentives—not itinerary count or headline length. A 129-night voyage may monetize otherwise less flexible ship capacity, but it also commits a vessel for a long period; verify the ship’s planned deployment, refurbishment needs and the economics of repositioning before assigning material upside.
Near term, the November booking launch is unlikely to change consolidated fundamentals. Over 1–3 months, deposits and booking pace may offer a useful demand check, but promotional onboard credits and reduced deposits make gross bookings a poor standalone indicator. Over 6–18 months, Australian port access, local consumer demand, airlift, fuel and currency moves will matter more to the season’s profitability than itinerary breadth. Added capacity can also intensify competition for passengers and port slots, with spillovers to other cruise operators and destination operators; the release does not establish net industry demand growth.
Contrarian read: the unusually generous incentives on the long cruise may indicate a need to secure commitment early, rather than pricing power. That is not proof of weak demand, but it argues against extrapolating the promotional launch into margin expansion. The thesis improves if bookings build at healthy net pricing and later promotions ease; it weakens if discounts persist or deployment/capex requirements rise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on this release. Treat it as a low-weight positive for CCL sentiment, not an earnings revision; avoid chasing any launch-driven share-price move without evidence of net yield improvement.
- Set an alert for post-launch booking pace, deposit conversion, cancellation rates and realized pricing net of onboard credits. Compare these with CCL’s own prior booking disclosures; the release provides no independently verifiable demand or margin data.
- For a 1–3 month catalyst watch, reassess if CCL commentary confirms strong Australia/New Zealand net yields or indicates promotional offers are being withdrawn. Persistent incentives, weaker pricing, or increased deployment and refurbishment costs would falsify the positive read-through.
- Before considering a position, verify Grand Princess’s deployment and refurbishment plan, relevant ship capacity and regional port/operating constraints. These determine whether the long itinerary adds attractive utilization or ties up capacity at an unfavorable opportunity cost.
More News
- Fed chairman talks tough on inflation — plus, what's behind Micron's big rally
- Investors Eye AI Payoff in Microsoft, Alphabet Earnings
- The 2,000-Nit OLED in Apple’s New MacBook Is a Big Deal
- Apple brings touch to the Mac, reversing years-old stance on touchscreen laptop
- Apple’s touchscreen MacBook Pro pushes laptop pricing to a new extreme
- The Inside Story of Why Apple Finally Brought a Touch Display to the Mac