
Epix Cruise and Travel Expands Group Cruise Services to a Broader Range of Groups
Source: PR Newswire
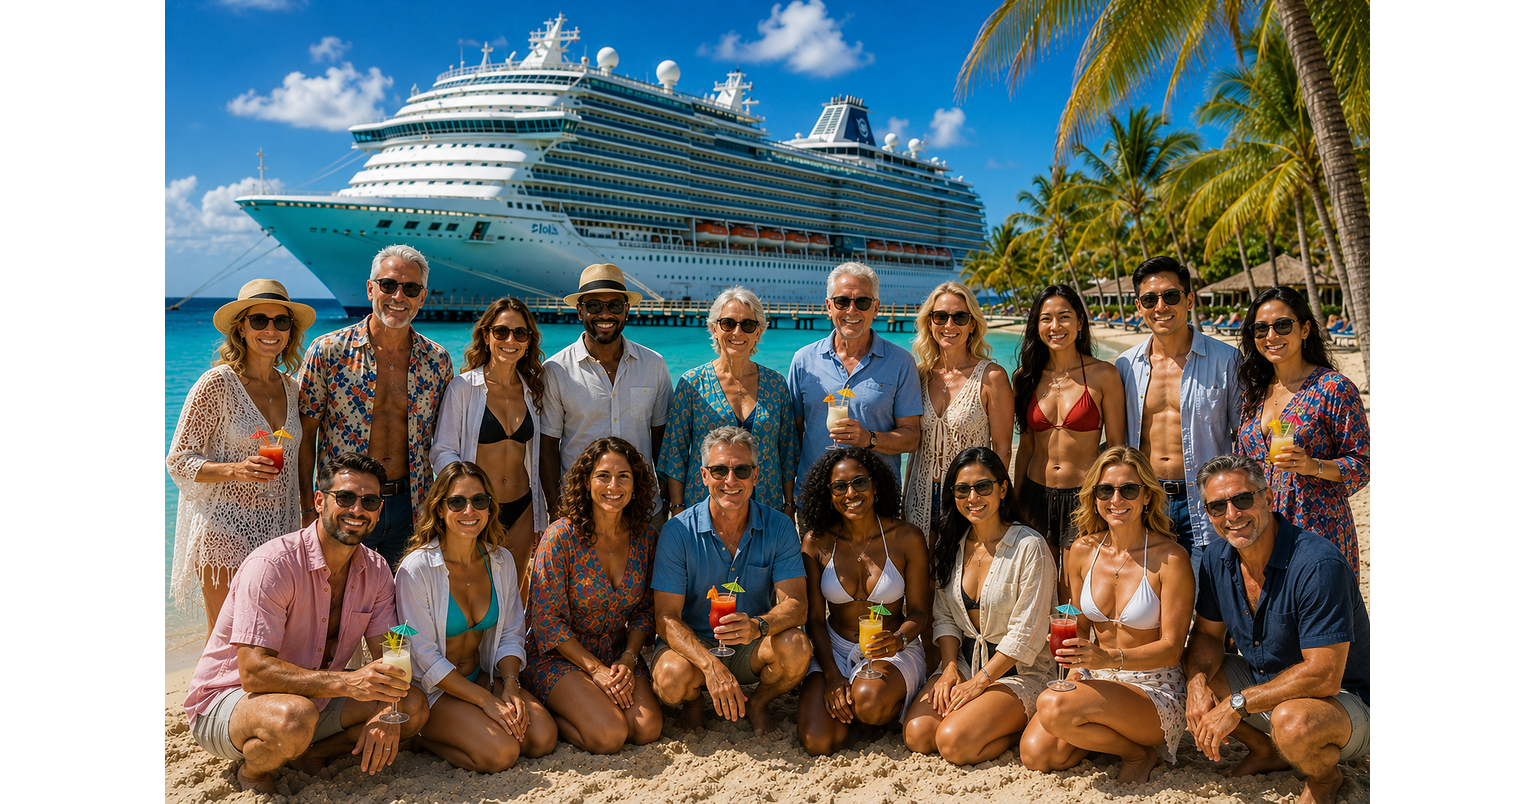
Epix Cruise and Travel is expanding its group-cruise services beyond corporate retreats to include family reunions, social groups, clubs, alumni groups, and fitness-focused travel. The move follows record global ocean-cruise passenger volume of 37.2 million in 2025, up 7.5% year over year, with industry forecasts exceeding 38 million passengers in 2026. The announcement is a business-scope expansion for a private travel company and is unlikely to materially affect public markets.
Analysis
This is not independently investable company news, but it modestly reinforces a favorable mix signal for listed cruise operators: group bookings generally improve load-factor visibility, reduce per-cabin acquisition cost, and support onboard spend through coordinated excursions, beverage packages, and event purchases. The largest read-through is to CCL, RCL, and NCLH, though the incremental volume implied by one small agency is immaterial relative to their capacity.
The more relevant second-order issue is distribution economics. A broader reliance on advisors and group organizers can lower direct-booking mix and raise commission expense, partially offsetting revenue-management gains; this matters most for NCLH, which has less scale to absorb fixed marketing and ship-deployment costs. Private-destination investment favors RCL and CCL if it converts group demand into higher onboard/shore monetization, while destination congestion or weather disruptions could impair the premium experience those assets are intended to create.
Over the next 1-3 months, investor focus should remain on forward booking curves, net yields, and fuel costs rather than anecdotal agency expansion. Over 6-18 months, the key risk is that industry capacity additions outpace discretionary leisure demand, forcing promotional pricing and reversing recent yield strength. A sustained deterioration in booked occupancy, lower net-yield guidance, or rising cancellation rates would falsify the constructive sector view.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No standalone trade on this release; treat it as a low-signal confirmation of group-cruise demand rather than a catalyst.
- Maintain a watchlist preference for RCL over NCLH for the next 6-12 months: RCL's private-destination ecosystem and higher-margin premium mix offer better monetization of group travel. Reassess if RCL guides to net-yield growth below capacity growth or if valuation premium expands materially versus CCL.
- For a sector expression only after verified booking data, consider long RCL / short NCLH over 3-6 months if both report stable occupancy but NCLH shows greater promotional intensity or weaker net-yield guidance; exit if NCLH closes the yield-growth gap for two consecutive reporting periods.
- Monitor CCL, RCL, and NCLH quarterly disclosures for group booking mix, onboard revenue per passenger cruise day, and commission/marketing expense. A rising commission ratio without corresponding net-yield growth would be a negative distribution-economics signal.
More News
- Oracle Japan shares surge 7% after record fiscal first quarter, bucking selloff of U.S. parent
- Akamai secures $11.6B cloud deal with Anthropic for AI workloads
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Here’s the Tesla Semi… again
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly
- New York sues Polymarket over allegations of illegal gambling operations
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Track Guidance Changes Across a Coverage List With AI
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?