
King Borris - Building Influence, Creating Impact, and Redefining the Comeback
Source: PR Newswire
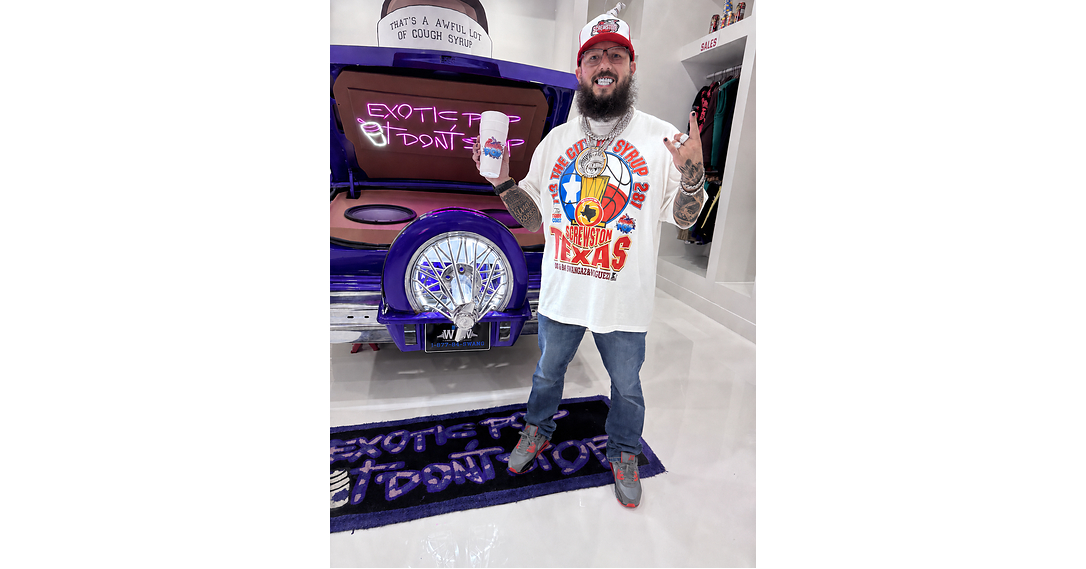
The article is a promotional/biographical announcement describing Houston entrepreneur King Borris expanding into the KB Network, including KB Media, KB Entertainment, KB Merch, KB University, and the KB Experiment podcast. It highlights his claimed reach of over 1 million followers and “millions of views” from social content, and positions the network as a strategy-led service and education offering for entrepreneurs and creators. No financial figures, earnings, guidance, or market-moving economic/regulatory developments are provided.
Analysis
This reads like founder-brand marketing, not a monetizable public-market catalyst. The only investable insight is that businesses built around a single personality tend to have weak durability, low operating leverage, and high key-person risk unless they show recurring revenue, contracted clients, or proprietary distribution. In practice, that means any value here accrues to the founder’s private ecosystem first; public equity holders have no visible claim on the economics.
The second-order issue is competitive: creator-agency and local PR businesses are highly substitutable, so margins compress quickly when the founder is not the bottleneck. If FOFA/NWCN are intended to be vehicles tied to this narrative, the market should demand proof of retention, client concentration, and cash conversion before assigning any multiple expansion. Without that, the stock reaction should fade within days; the real test is the next 1-2 quarters of bookings and repeat revenue.
Contrarian take: consensus often overvalues “network” stories because they sound scalable, but most of these models are labor-intensive and founder-dependent. The upside case only works if the platform becomes a low-CAC funnel into paid education/media/community offerings, with meaningful gross margin and repeat purchase behavior over 6-18 months. What would falsify the bearish view is audited evidence of recurring clients, rising ARPU, and a second operator taking over distribution without loss of engagement.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No immediate position in FOFA/NWCN on this release; treat it as non-fundamental until there is verifiable revenue, client-retention, or cash-flow disclosure over the next 1-2 quarters.
- Set an alert for any 10%+ sympathy move in creator-economy or local media-adjacent names over the next 1-3 sessions; fade the move if it is not accompanied by hard KPIs or a new distribution partnership.
- If FOFA/NWCN are public comps to this kind of founder-led agency model, only revisit on evidence of recurring revenue and low client concentration; otherwise prefer to stay short-duration and avoid multiple expansion bets.
- Watch for a structural tell over 6-18 months: if the business can add an operator-led sales engine and subscription-like products, the thesis shifts from personality premium to scalable media platform.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Bank of America is bullish on these top stocks ahead of earnings
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- AI's Supercharging a Scam Economy Bigger Than the Cocaine Trade
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant