
Medtronic Announces Strategic Investment in Pi-Cardia to Accelerate Innovation for Complex TAVR
Source: PR Newswire
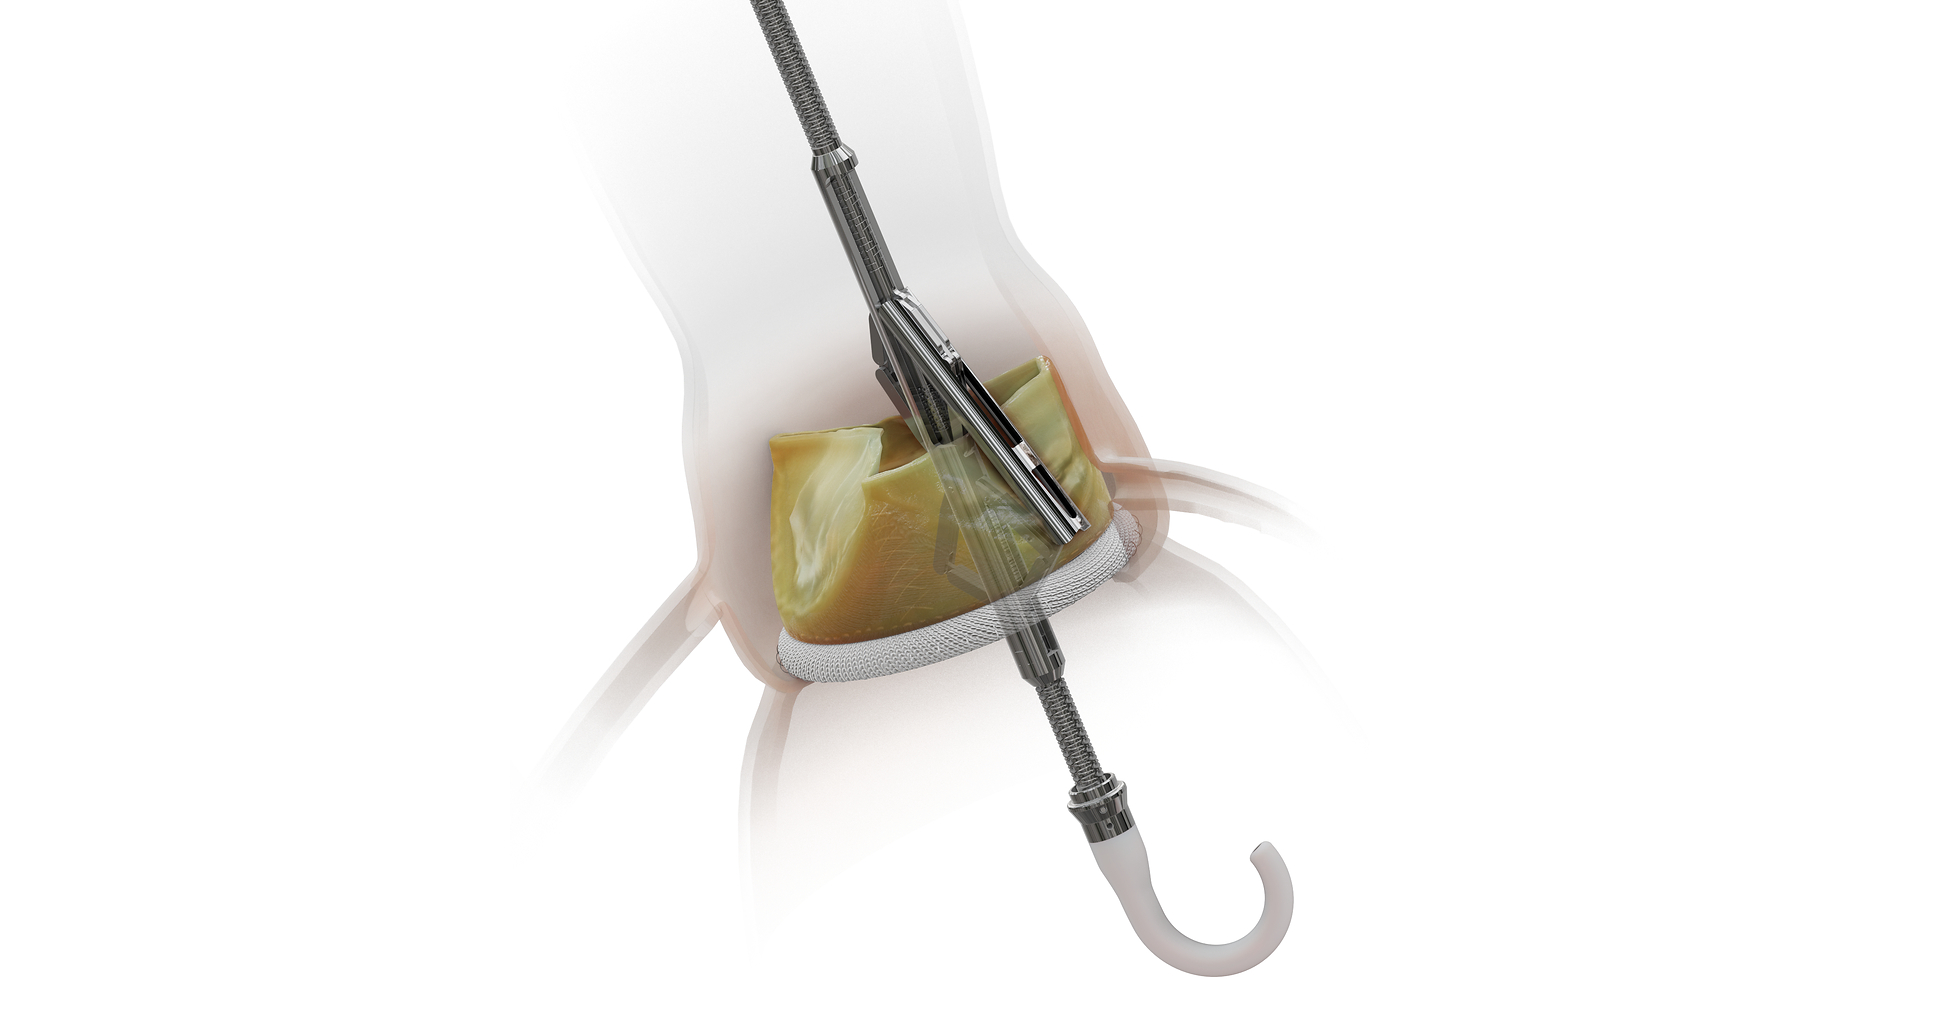
Medtronic (MDT) announced a strategic investment in Pi-Cardia, with funding of up to $80M, to strengthen its structural heart portfolio around Pi-Cardia’s FDA-cleared ShortCut™ leaflet modification technology for valve-in-valve TAVR. Medtronic is expected to become the exclusive global commercial distributor in 2027, and it holds an option to acquire Pi-Cardia for up to $210M upfront (plus potential earn-outs) upon milestone achievement, subject to regulatory approvals. The deal is designed to support adoption of a technology intended to preserve coronary access in complex TAVR patients.
Analysis
This is more valuable as an option on future ecosystem control than as an earnings event. The economics are modest today, but Medtronic is buying a potential workflow moat around complex TAVR cases, which matters because the vendor that owns the adjunct procedure can raise switching costs and deepen physician dependence over time. If adoption broadens, the real upside is not the small upfront investment — it is higher share of wallet in a market where procedural complexity tends to favor integrated platforms and sticky training effects.
The second-order read-through is slightly negative for Edwards Lifesciences and, to a lesser extent, Abbott: not because they lose volume immediately, but because Medtronic is addressing a capability gap that previously made it easier for rivals to argue best-in-class procedural completeness. That matters most in 12-24 months, when commercial access and physician familiarity can turn a niche tool into a standard accessory. In the near term, however, this should not move the sector materially; the rollout path and reimbursement/learning curve are too long-dated for a large rerating today.
The key risk is execution: if clinical utility does not translate into clear procedural time savings, coronary-access preservation, or reimbursement support, the investment becomes stranded option value. The thesis is falsified if by 2027 the distributor relationship is delayed, if adoption remains confined to referral centers, or if MDT’s structural heart growth does not inflect despite broader TAVR expansion. The market is likely to overreact to the narrative and underreact to the timing, so this is a medium-horizon relative-value story, not a catalyst-driven earnings trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Overweight MDT on pullbacks for a 6-12 month horizon; treat this as a strategic-option catalyst rather than an immediate EPS driver. Risk/reward is attractive if structural heart re-rates on portfolio completeness, but size modestly because monetization is delayed.
- Pair long MDT / short EW for a 3-12 month structural-heart relative value trade if you want to express the view that Medtronic is closing the product-gap narrative. Falsify if EW shows accelerating complex-case share or MDT structural heart growth stays flat.
- Do not chase the headline move intraday; wait for any weakness over the next 1-3 sessions. The expected fundamental contribution is too small to justify paying up on day one.
- Set a watch item on MDT structural heart order growth and gross margin commentary over the next 2 earnings prints; if no evidence of mix or adoption lift appears, take profits on any long exposure.
- No standalone options trade is compelling here unless there is an unrelated selloff; the event is too long-dated for clean gamma capture.
More News
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- FDA approves Enspryng for thyroid eye disease treatment
- Giant Taiwanese chipmaker TSMC confirms it’s in talks with Elon Musk to join ‘Terafab’ complex in Texas: ‘The AI market continues to be very strong’
- The Tesla Roadster 2 Is Here—and It Flies
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Is an AI Investment Research Platform?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?