
VIO Med Spa Expands Dallas Footprint as Former Meta Executive Acquires Two Locations and Signs for Prosper
Source: PR Newswire
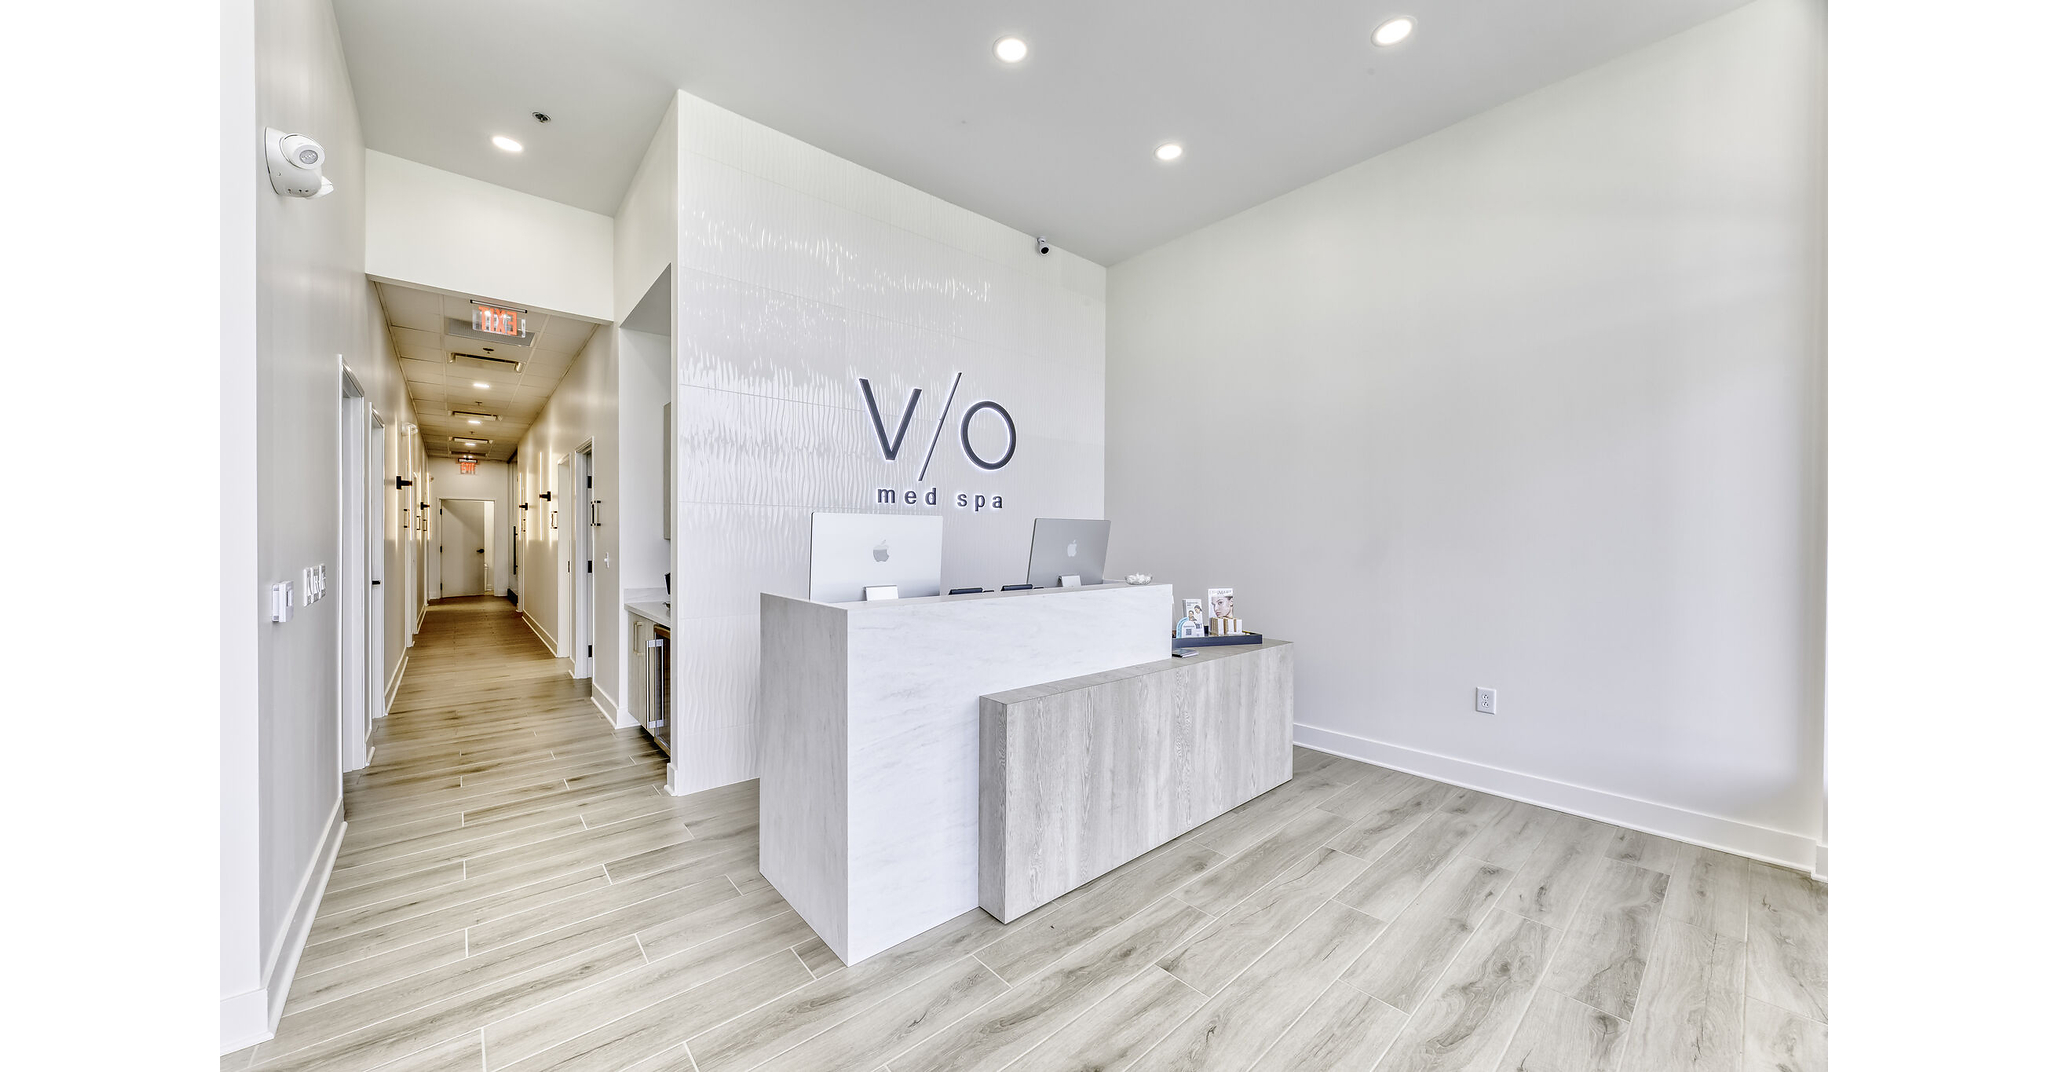
VIO Med Spa expanded its North Texas footprint via Joseph Luchenta, a former Meta/McKinsey executive, acquiring two existing locations in Richardson and McKinney and securing development rights plus an agreement to open a new site in fast-growing Prosper. The move supports VIO’s physician-guided, advanced non-invasive aesthetics and wellness model, with Luchenta taking ownership in Q2 2026 and targeting operational strengthening over the next 18–24 months before Prosper development.
Analysis
This is more a validation of a resilient discretionary niche than a market-moving event. The economic mechanism is that affluent consumers are still spending on recurring, high-margin self-pay services even with broader consumer normalization, which supports franchise asset values and keeps the unit economics of physician-adjacent wellness concepts attractive to private capital. The immediate read-through for public markets is weak; this does not change earnings power for META, and the former executive angle is more signaling than fundamental.
The second-order implication is competitive pressure on local dermatology and plastic surgery practices, which can lose lower-acuity cosmetic demand to faster, more convenient chain formats. If this model keeps scaling in fast-growing suburban corridors, the real winners are likely equipment and consumables vendors with recurring usage exposure, while single-location independents face margin pressure from rising marketing costs and higher labor intensity. Over 6-18 months, the risk is that the category becomes overcrowded and CAC rises faster than ticket prices, compressing franchise-level IRRs.
Contrarian takeaway: the market may be overreading the growth narrative from a single buy-and-build transaction. Franchise expansion stories tend to look strongest at the point of unit acquisition, but the actual test is same-store comp durability and provider retention over 2-4 quarters. A reversal would come from any slowdown in discretionary spend, weaker suburban housing/wealth effects, or evidence that med-spa openings are cannibalizing each other faster than new demand is created.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No direct equity trade: treat this as a watch item, not a conviction signal. Wait for sector-wide data on same-store sales, CAC, and provider churn before expressing a view.
- If you want a public-market proxy, use a small tactical long in XLY versus a short in a consumer-discretionary basket with higher ticket pressure over the next 3-6 months only if broader high-end services data stay firm; otherwise stay flat.
- Monitor META as a talent-allocation data point only, not as a trade. There is no identifiable earnings linkage; any position should be based on core ad/AI fundamentals, not this executive move.
- Set an alert on med-spa operator disclosures and franchise filings over the next 1-2 quarters: if new unit economics show CAC inflation or sub-expected ramp rates, fade the roll-up narrative in private consumer services.
- If you need exposure to the theme, prefer a basket of recurring-revenue health/wellness enablers over single-brand franchise stories; the risk/reward is better when the underlying spend is validated across multiple operators.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- TSMC chip capacity is ‘fierce’ battleground for AI customers, amid record quarter
- Factbox-CoreWeave’s AI contracts and the lenders financing its build-out
- Apple and Meta team up to make Muse AI model run on Mac computers
- Nvidia’s European spending spree is about much more than Europe
- Anthropic taps nonprofits METR and SecureBio to help assess risks and safety practices
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research