
Firehawk Defense Tops $1.4 Billion Valuation: NYSE Content Update
Source: PR Newswire
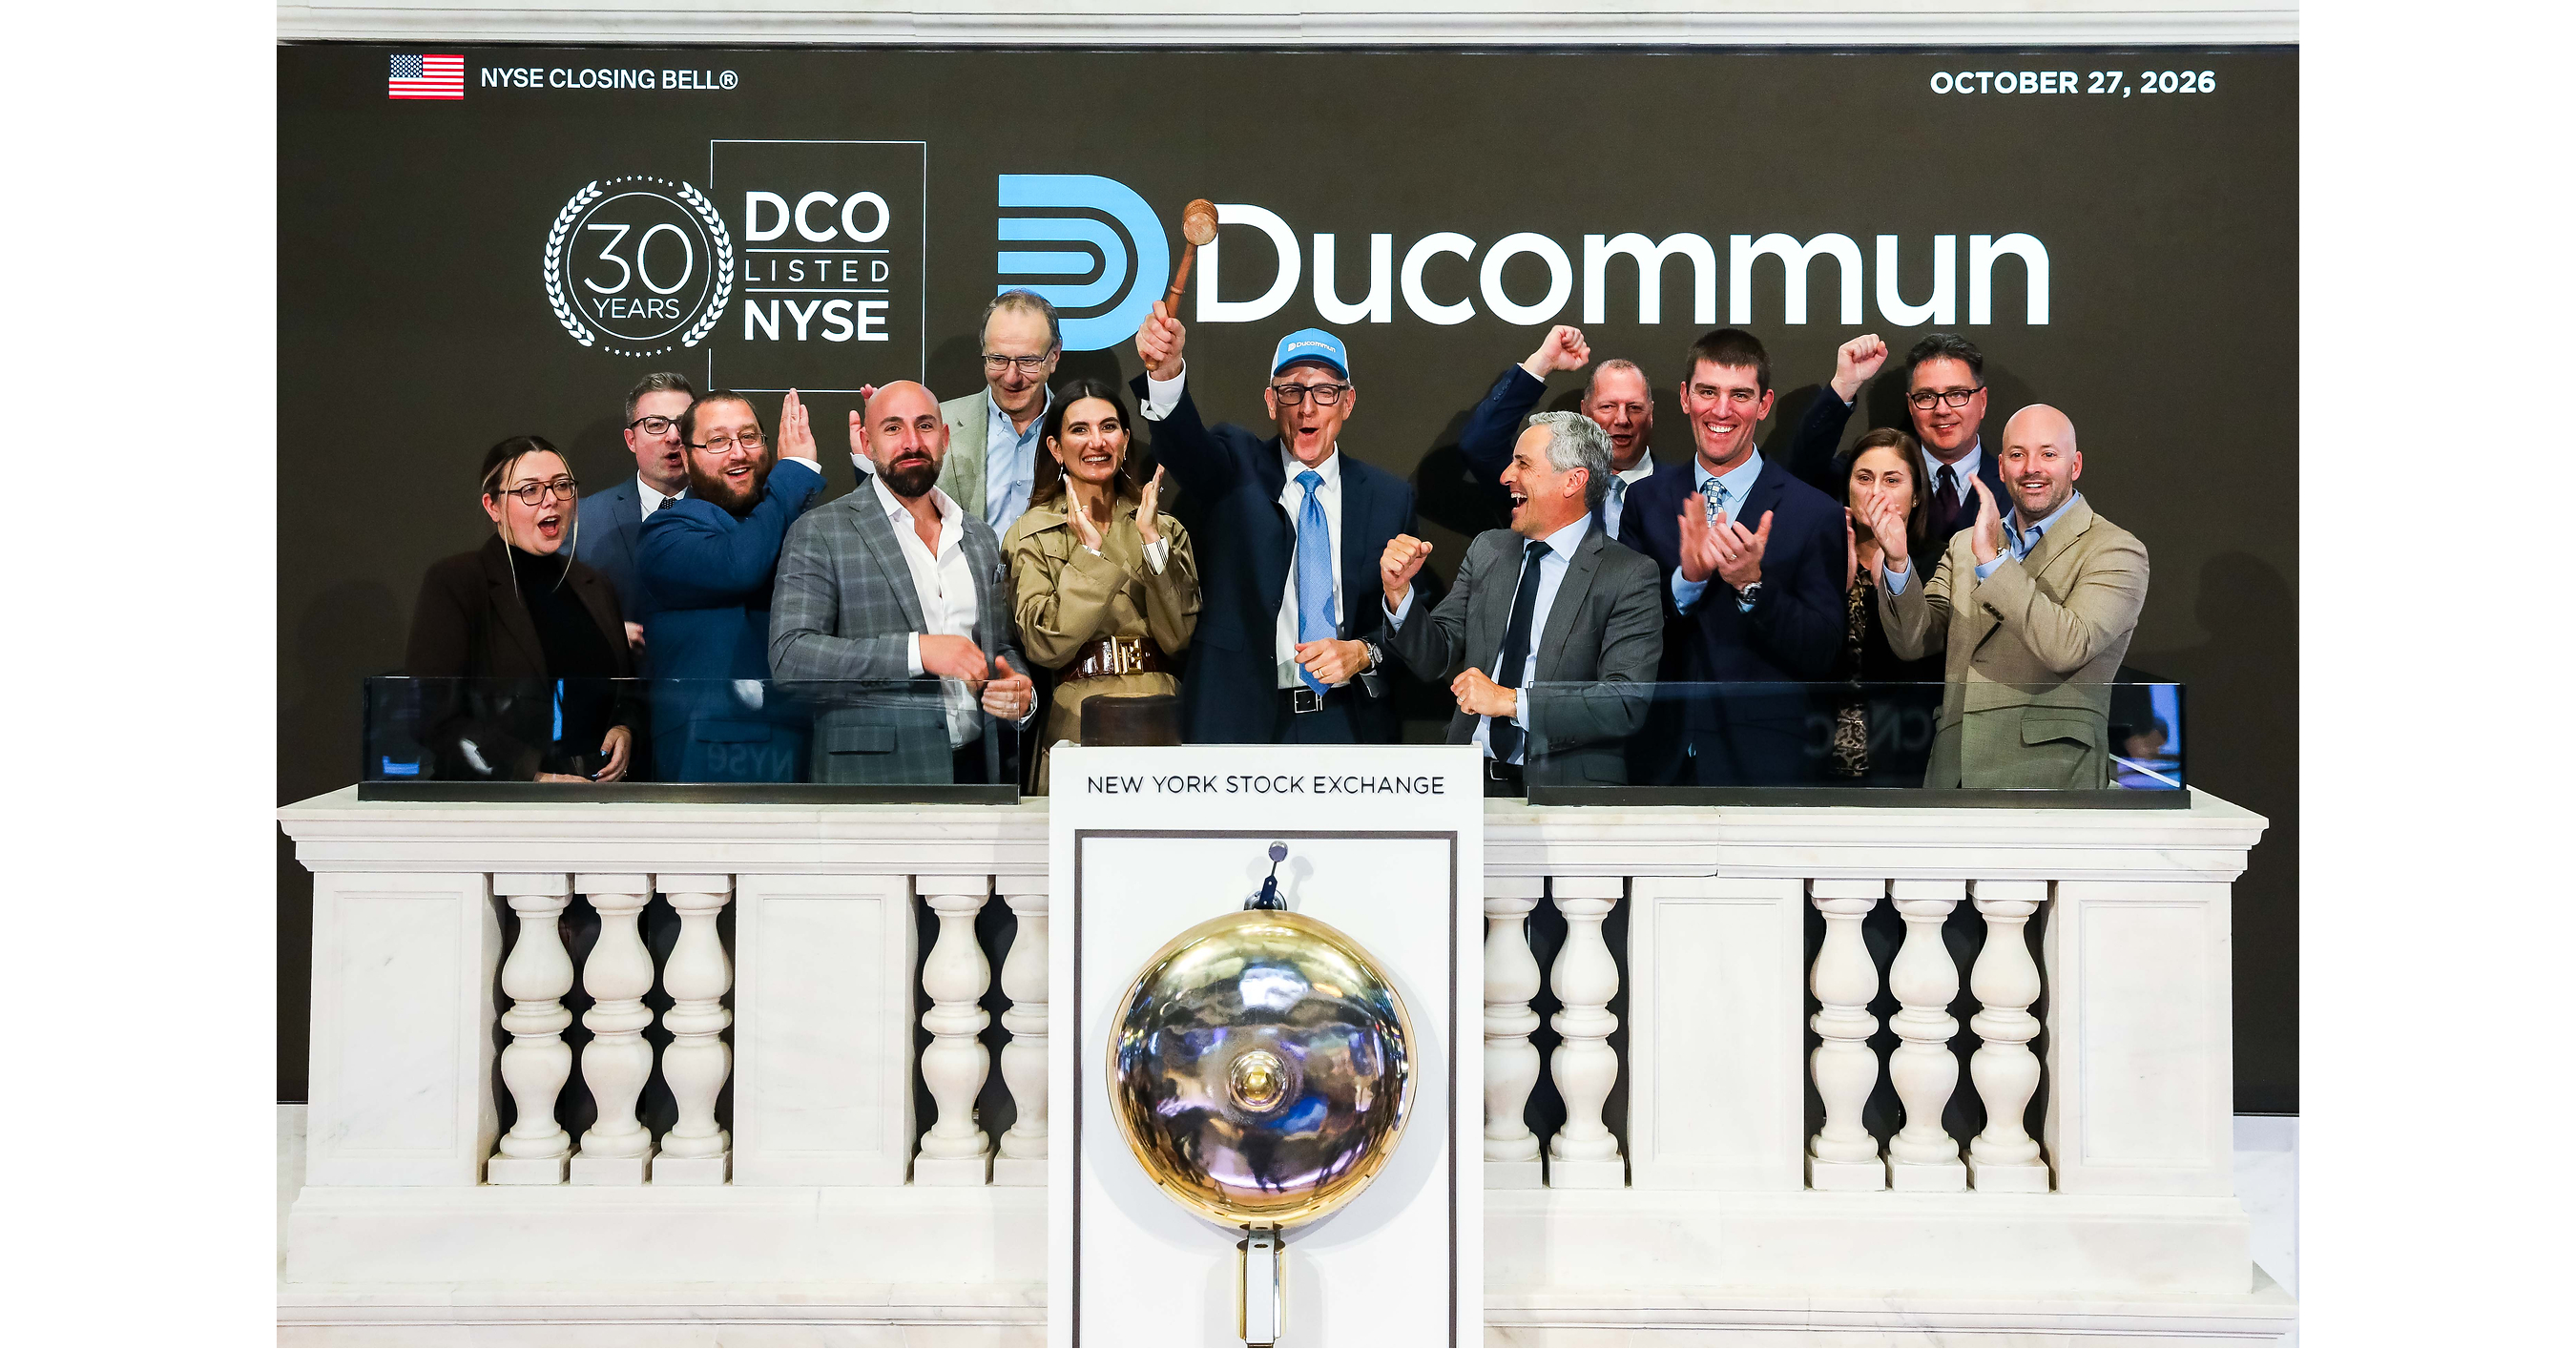
Firehawk Defense announced a $150 million funding round and plans to produce over 100,000 artillery motors next year, targeting status as the largest U.S. producer by the end of 2027; proceeds will expand facilities in Oklahoma and Mississippi. Hex raised its valuation to $1.2 billion, launched Hex 4.0, and said it had its best revenue quarter. BigBear.ai reported 31% year-over-year revenue growth and raised its 2026 revenue guidance to $150 million-$165 million; it is scheduled to report Q3 earnings after Tuesday's close.
Analysis
The defense read-through is a potential easing of a munitions-production bottleneck, not evidence that procurement dollars or orders have already shifted. If Firehawk converts its expansion into qualified, on-time deliveries, it could improve throughput for downstream ammunition programs and pressure incumbent motor suppliers; the key checks are funded contracts, qualification milestones, and realized output—not announced capacity. That is a months-to-years thesis, while the private funding headline itself has limited direct public-equity exposure.
For BBAI, the raised outlook is a near-term sentiment support, but the investable question is whether growth converts to durable, cash-generative work rather than low-quality or lumpy project revenue. The advisory’s earnings timing is ambiguous against its publication date; verify the actual release and call before treating this as a live catalyst. Over 1–3 months, watch revenue versus the raised range, bookings/backlog conversion, and cash use. Over 6–18 months, execution and contract economics matter more than headline growth. A miss on those measures could unwind the optimism quickly.
Hex’s agent-oriented product claims are a competitive signal, not proof of customer adoption. The second-order risk is faster feature commoditization and pricing pressure across enterprise analytics software; validate through customer traction and retention before extrapolating from a record quarter. BXSL’s anniversary is not a credit or earnings catalyst. Overall, the advisory is more useful as a watchlist than a broad risk-on signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Ticker Sentiment
Key Decisions for Investors
- BBAI: Do not chase the guidance headline before confirming whether earnings have already been released. If the stock gaps higher, wait for the call and assess backlog conversion, cash flow, and contract economics; a revenue or outlook shortfall, or weaker cash conversion, would falsify the constructive read.
- Firehawk: Treat the capacity announcement as a defense-supply-chain watch item, not a public-equity trade. Revisit only after evidence of funded procurement, successful qualification, and delivered volume; announced capacity without those milestones would weaken the thesis.
- Enterprise software: Monitor Hex customer adoption and retention as indicators of whether agent features create pricing pressure for established vendors; no position is warranted from the product announcement alone.
- BXSL: No trade from the anniversary item; reassess on credit-quality, NAV, funding-cost, or distribution disclosures rather than event publicity.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Budget 2026 speech
- SK Hynix says the memory-chip shortage will last until 2030—and more than half its production is booked for the next two years
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong