
Warrior Met Coal: A Volume Story Still Priced Like A Coal Price Bet
Source: seekingalpha.com
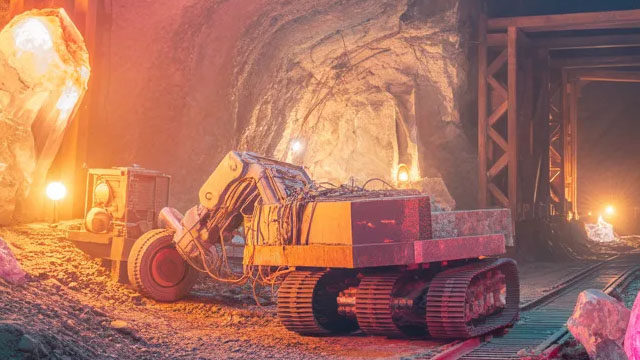
Warrior Met Coal's Blue Creek Mine ramp helped drive record Q2 sales of 3.7 million short tons while reducing unit costs to $92.53 per ton. The company is increasingly generating earnings growth from contracted volume expansion and cost reductions rather than coking-coal price exposure, improving visibility versus peers. Forward valuation multiples are expected to compress materially as the additional production supports earnings growth.
Analysis
HCC is shifting from a pure met-coal beta into an execution-and-throughput story, which should reduce the earnings multiple discount typically assigned to single-asset Appalachian producers. If incremental tons continue to absorb fixed costs, EBITDA can rise even in a flat-to-down benchmark-price environment; that operating leverage is more valuable than headline volume growth because it improves free-cash-flow resilience through the cycle. The market will likely wait for two additional quarters of evidence that ramp productivity, quality yields, and logistics performance are durable before capitalizing this at a higher multiple.
The key second-order risk is that new supply arrives into a met-coal market already exposed to weak ex-China steel demand and potential Chinese import-policy changes. HCC's contract coverage cushions near-term realized pricing, but it also limits upside participation if premium hard-coking-coal prices rebound sharply; more spot-exposed producers such as AMR would outperform in that scenario. Conversely, should benchmark prices decline, HCC's contracted book and falling unit costs make it a relative winner versus higher-cost U.S. peers and Australian producers facing freight and currency volatility.
Near-term catalysts are quarterly cash-cost progression, shipment realization versus mine plans, and confirmation that capital spending is not creeping above the ramp budget. The contrarian point is that investors may be treating the volume ramp as already de-risked: underground mine ramps can suffer from development delays, labor availability, methane interruptions, and lower-than-modeled recovery rates. A sustained reversal in cost improvement or a cut to annual shipment guidance would undermine the rerating thesis faster than a modest decline in met-coal benchmarks.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Accumulate HCC on broad met-coal weakness over the next 1-3 months rather than chase a post-results move; underwrite the position to execution-driven EBITDA growth rather than a commodity-price recovery. Target a 15-25% total-return opportunity over 6-12 months if unit-cost reduction and shipment cadence remain intact; exit if management cuts volume guidance or quarterly cash costs reverse materially for two consecutive periods.
- Use a relative-value structure: long HCC / short AMR in equal beta-adjusted dollar amounts for 3-6 months. The trade expresses HCC's superior contracted-volume and cost-down visibility while reducing exposure to benchmark met-coal prices; close if premium hard-coking-coal prices rally sharply and AMR's spot leverage begins to dominate.
- Monitor quarterly operating disclosures before increasing exposure: realized price versus benchmark, cash cost per ton, Blue Creek recovery/yield, development footage, and capex-to-plan. Treat any unexplained capex inflation or shipment shortfall as an execution alert, not a buying opportunity.
- Do not add a broad coal-sector long solely on HCC's setup. A weaker global steel cycle would likely pressure CNR, AMR and met-coal ETFs/proxies despite HCC's relative advantages; retain commodity hedges or maintain the pair rather than taking unhedged sector beta.
More News
- Oil gains over 1% as Trump rejects Iranian proposal to reopen Hormuz Strait
- Northern Star shares pop as Australian gold miner rejects $27-billion takeover proposal
- Here are the 4 big things we're watching in the stock market in the week ahead
- The U.S. may soon receive $600 million worth of Iranian oil that was seized earlier in the war, putting an ancient body of maritime law back in focus
- Paramount Warner Deal Tests Hollywood’s Future
- Trump Rejects Iran Plan to Reopen Hormuz