
Chromalloy and Lufthansa Technik Achieve Fifth V2500 Select PMA Approval with New High Pressure Turbine Stage 1 Blade
Source: Newswire
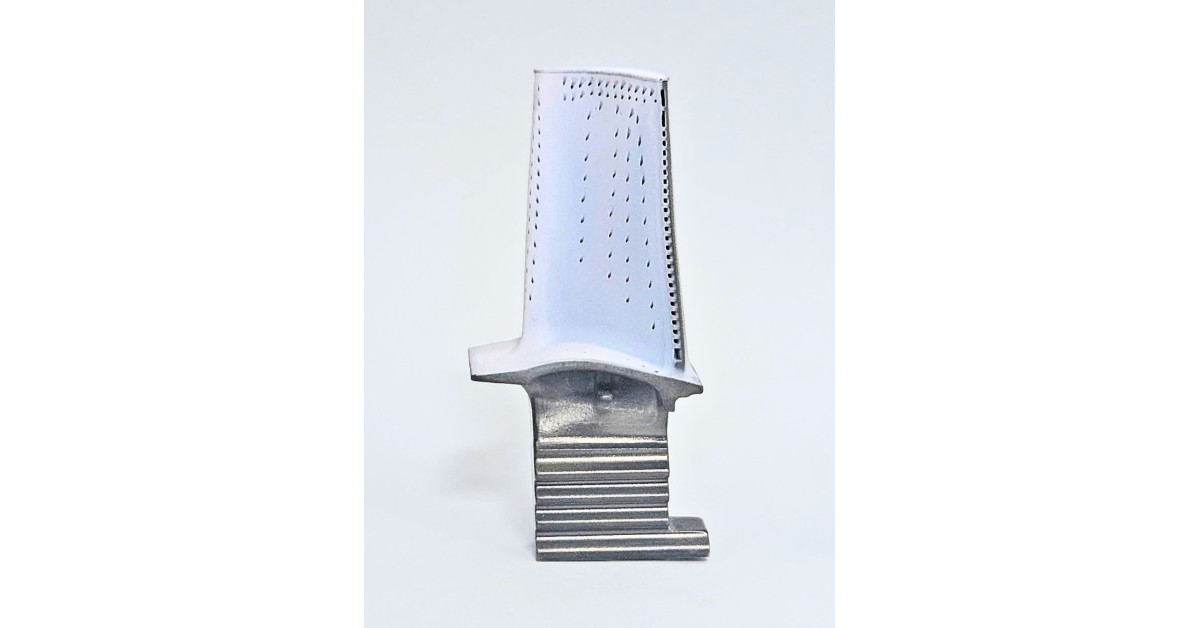
Chromalloy and Lufthansa Technik received FAA certification for a fifth V2500 Select engine PMA component: a High Pressure Turbine Stage 1 blade. Chromalloy invested more than $100 million in the blade's development, certification, and Florida-based production capabilities, including new anti-corrosion and multi-layer thermal-barrier coatings. Production is ramping through 2026 and into 2027, with initial shipments to Lufthansa Technik expected shortly; additional midlife-engine parts are expected to enter FAA review later this year.
Analysis
The economic value accrues primarily through aftermarket price competition rather than new-engine demand. FAA-approved alternatives for a high-value, life-limited hot-section component can pressure proprietary spare-parts pricing and strengthen Lufthansa Technik's ability to win V2500 shop visits on total-cost-of-ownership; the most exposed public proxy is RTX, whose Pratt & Whitney business participates in the V2500 program. The near-term earnings effect on RTX is immaterial given its scale, but repeated PMA approvals can matter at the margin because OEM aftermarket profitability depends disproportionately on exclusive material content.
The $100M-plus investment is a signal of a capacity moat, not proof of attractive returns. Qualification costs, airline adoption cycles, inventory stocking, and repair-network incorporation mean meaningful volume is more likely a 12-36 month outcome than a 2026 catalyst; initial production ramp could also be cash consumptive. The key verification points are airline/MRO adoption beyond the launch channel, realized shop-visit penetration, and whether part pricing remains sufficiently below OEM material to induce switching without eroding Chromalloy's own return on invested capital.
A second-order beneficiary is Deutsche Lufthansa (LHA.DE), but only modestly: Lufthansa Technik can use alternative material to defend external MRO margins and improve bid competitiveness, while its airline parent benefits indirectly from lower maintenance cost on remaining V2500-powered A320ceo operations. The contrarian view is that the addressable market is structurally finite: V2500 fleet retirements and A320neo replacement progressively shrink demand over the next decade, so this is a harvest-market share story rather than a durable aerospace growth inflection. No broad aerospace-sector trade is warranted from a private-company press release alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- Maintain a 6-12 month watch on RTX aftermarket pricing and Pratt & Whitney segment margin commentary; consider a tactical short only if management cites V2500 spare-part price pressure or reduced OEM material share, as this certification alone is not material enough to support a position.
- Monitor LHA.DE through the next two earnings cycles for Lufthansa Technik external-revenue growth and margin expansion versus airline maintenance-cost trends. A long is actionable only if Technik margin improvement appears without offsetting fleet-transition or airline-demand weakness.
- Do not extrapolate this into a long on broad aerospace aftermarket ETFs such as ITA or XAR: the relevant exposure is concentrated in a mature V2500 installed base, while listed OEM and MRO constituents have limited direct sensitivity.
- Set an adoption alert for additional FAA approvals and disclosed multi-airline contracts over the next 6-18 months. Multiple components adopted across the engine overhaul bill of materials would increase the probability of measurable OEM aftermarket share loss; absent that evidence, treat the development as competitively relevant but financially immaterial.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Oil falls on increased Gulf supply and hopes for US-Iran talks
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Latest Oil Market News and Analysis for Sept. 23