
BOXABL Inc. Launches Expansion of Project Development Capabilities, Connecting Manufacturing and Real Estate Development
Source: PR Newswire
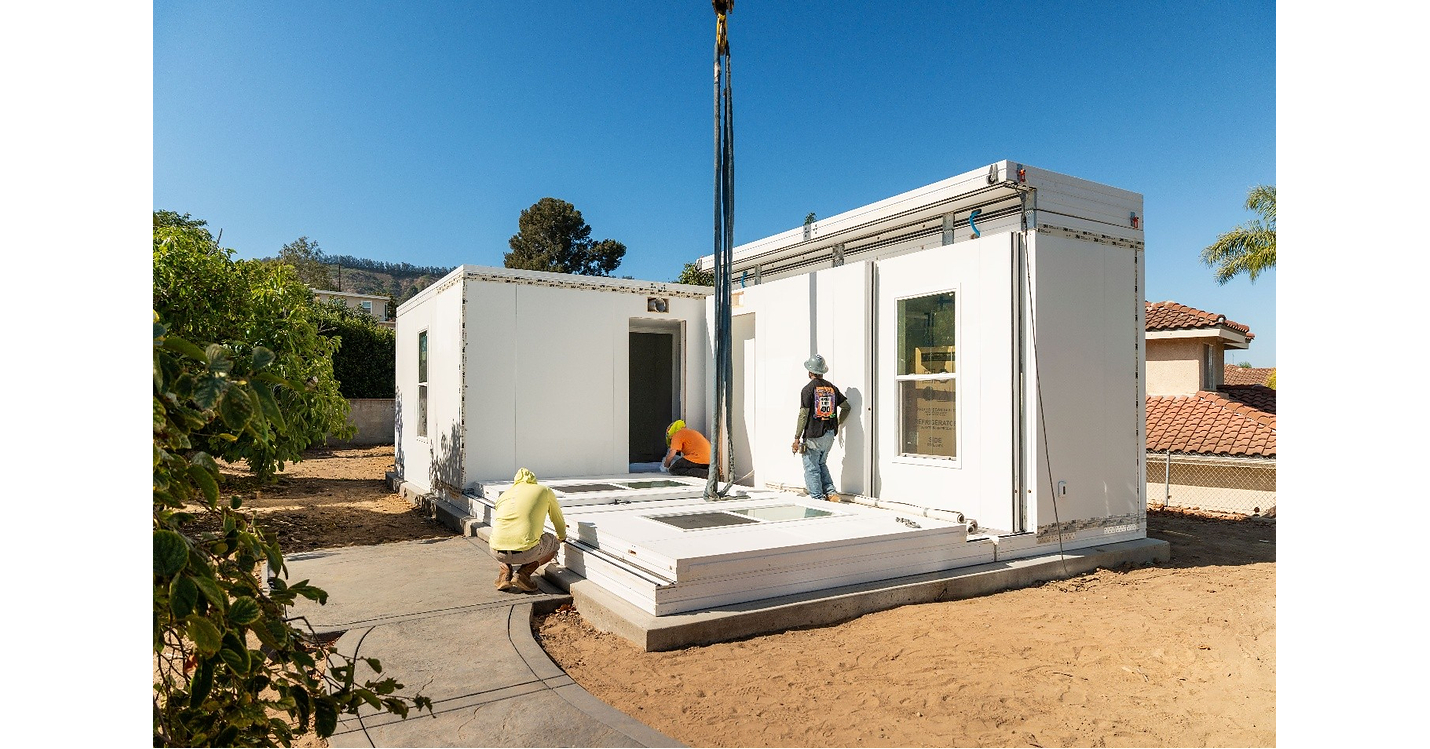
BOXABL announced an expansion of its project development capabilities, starting with a licensed general contractor in California, shifting from managing third-party site work to owning the full project end-to-end (factory through finished installation). The company says the change is designed to remove a cost/coordination layer, enable more predictable bundled pricing, and improve quality control/warranty alignment. BOXABL’s developer arm targets both homeowners (streamlined permitting-to-install path) and large-scale customers via full-service delivery or RFP-led bids, with further state expansion expected as demand warrants.
Analysis
This is strategically positive for BXBL only if the company can convert a sales-function announcement into repeatable gross profit per project. The immediate market read will likely be “more control = better economics,” but the more important second-order effect is that BXBL is moving from a relatively clean manufacturing story into a higher-friction services and project-management stack, which usually means more working capital, more liability, and less visible margin quality. In the near term, the stock can trade on narrative expansion; over 6-18 months, the real question is whether attached site work improves unit economics or simply inflates revenue with lower incremental returns.
The competitive implication is that BXBL is trying to win by reducing coordination friction, which matters most in municipal, developer, and multi-unit bids where execution risk often kills modular adoption. That could pressure smaller local contractors and some traditional GC partners, but the larger battleground is with established manufactured-housing and modular peers such as SKY, CVCO, and broader housing ETFs like XHB/ITB: if BXBL can bid turnkey, it may improve win rates even without superior product, because procurement teams value one throat to choke. The catch is that turnkey capability tends to compress defensibility unless the company can prove a cost curve advantage at scale.
The contrarian view is that investors may be overvaluing the “vertical integration” label. For a young public company, adding contracting can surface hidden risks: state-by-state licensing delays, labor coordination, warranty disputes, and delayed cash conversion, all of which can overwhelm the advertised savings. The first falsifier is not the press release but the next 1-2 quarters of disclosure: if gross margin deteriorates, SG&A rises, or project backlog fails to convert into cash, the market should re-rate this as a services-heavy execution risk story rather than a scalable platform.
I’d treat this as an alert rather than a conviction buy. The upside path is a credible multi-unit win or municipal award over the next 1-3 months; the downside path is immediate if management leans on non-core revenue while operating losses widen. For now, the best trade is likely to wait for proof points rather than pay for the option premium embedded in a small-cap narrative stock.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No-action / watchlist on BXBL for now: wait for evidence in the next quarterly filing that turnkey projects improve contribution margin and cash conversion; if SG&A expands faster than gross profit, fade any post-announcement strength.
- Set an event-driven alert on BXBL for the next 1-2 contract wins or state licensing updates; initiate only if management shows repeatable multi-unit backlog conversion rather than one-off PR-driven pipeline claims.
- Relative-value idea: long XHB or ITB versus BXBL if BXBL rallies on the headline, using the ETF as a cleaner housing beta expression and BXBL as the idiosyncratic execution-risk leg.
- Pair-trade watch: long SKY/CVCO on any sector weakness, short BXBL on strength, if subsequent disclosures show BXBL’s ‘full-service’ model is adding revenue but not margin; invalidate the short if BXBL reports better-than-expected project-level gross profit.
- For risk control, avoid chasing BXBL common into this announcement; if a trade is desired, use a small-defined-risk put spread only after borrow/liquidity checks and only if the stock fails to hold post-news gains over 3-5 trading days.
More News
- Cata-Kor Enters Physical Retail with Target Launch, Bringing Its NAD⁺ Longevity Line to Stores Nationwide
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Stocks saw new highs and big declines: How the volatile AI trade moved last week's market
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant