
CordenPharma Appoints Dr. Jean-Luc Herbeaux as Chief Executive Officer to Lead Next Phase of Growth
Source: PR Newswire
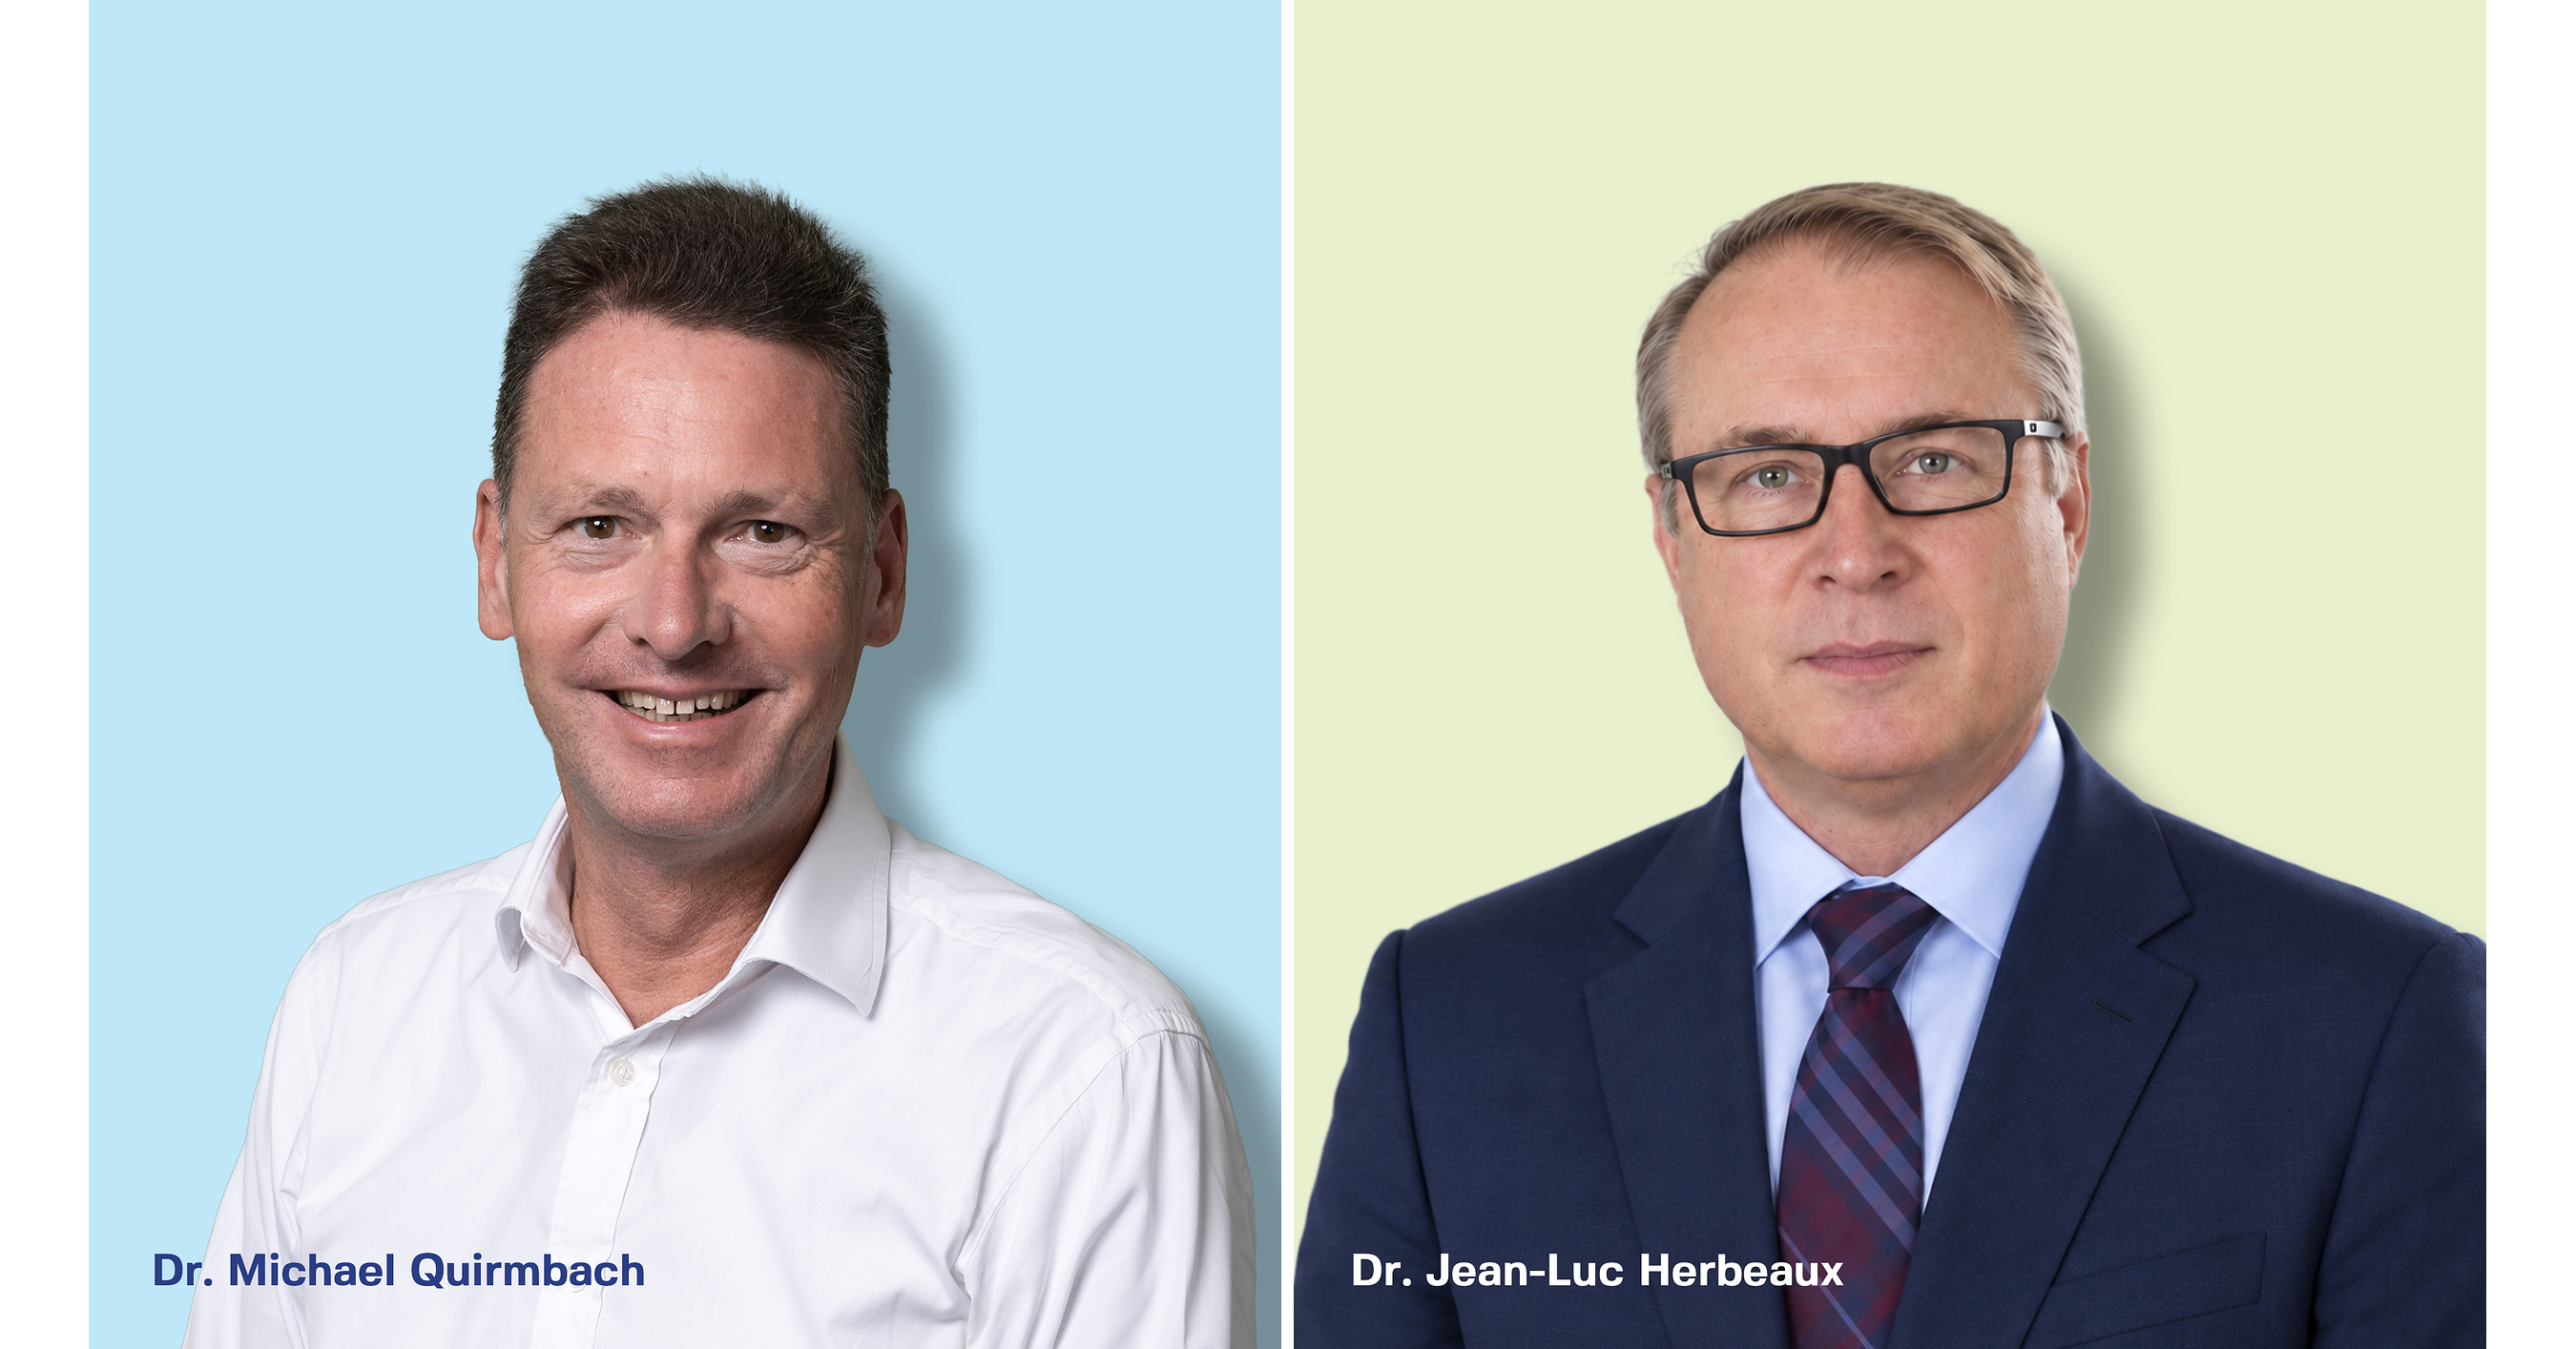
CordenPharma appointed former Hovione CEO Dr. Jean-Luc Herbeaux as CEO effective 1 October 2026, while outgoing CEO Dr. Michael Quirmbach will remain a board member and senior adviser. The planned succession follows major expansion, including the acquisition of peptide CDMO AmbioPharm; revenue grew from €245 million in 2014 to more than €1 billion, while FY2025 sales were €960 million. Herbeaux will focus on executing growth plans, expanding capacity and strengthening CordenPharma's global CDMO platform.
Analysis
This is not a direct listed-equity catalyst: CordenPharma is privately held, and the incoming executive’s departure from Hovione removes a proven operator from a competitor rather than changing EVK’s reported earnings outlook. For Evonik, the relevant channel is its Health Care CDMO franchise: a more execution-focused Corden could intensify competition for complex-modality contracts, particularly where customers value integrated development-to-commercial supply. The near-term financial effect on EVK should be immaterial versus its much larger nutrition, specialty-additives and materials exposures.
The more investable read is that sponsor-backed CDMO capacity continues to consolidate around peptides, oligonucleotides and lipid-delivery capabilities. This raises the hurdle for subscale public peers and may increase pricing pressure for standardized API work, while favoring scaled, differentiated operators such as Lonza (LONN.SW) and Thermo Fisher (TMO) that can cross-sell analytical, development and commercial services. Over 6-18 months, successful integration and capacity utilization at private competitors could reduce scarcity premiums in select outsourced modalities rather than expand industry-wide margins.
Consensus should not treat an executive appointment as confirmation that incremental capacity will earn attractive returns. The key unknown is utilization of recently added assets and the cadence of customer program conversions; capital-heavy CDMO expansions can dilute returns materially if biotech funding or late-stage trial progression weakens. A visible increase in industry lead times, commercial-slot pricing, or competitor backlog would validate a tighter-capacity thesis; absent those indicators, there is no standalone EVK trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No directional EVK position on this item; maintain EVK as a watch name only. Reassess if management discloses Health Care order-book acceleration or margin guidance changes, as that is the only credible public-market transmission mechanism.
- For a 6-12 month quality-CDMO expression, prefer a modest long LONN.SW versus short a broad European chemicals basket (EXV1/sector proxy), not EVK outright; thesis is differentiated pharma-services earnings resilience. Exit if Lonza reports declining biopharma backlog or cuts medium-term margin targets.
- Monitor private-CDMO capacity announcements, peptide/LNP lead times, and utilization disclosures from LONN.SW and TMO over the next two quarters. If capacity additions coincide with falling pricing or weaker book-to-bill, avoid CDMO multiple expansion and consider reducing exposure to high-multiple outsourced-services names.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- Factbox-Private equity, foreign investors fuel Aussie M&A activity in 2026
- Is Amazon Stock a Buy After Its Best Quarter in Years?
- Australia’s Reliance Worldwide agrees to Brookfield’s $2.9 billion buyout bid
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Track Guidance Changes Across a Coverage List With AI
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?