
Tractian's $130M Series D Values the Company at $1.4B to Scale Physical AI for Asset-Heavy Industries
Source: PR Newswire
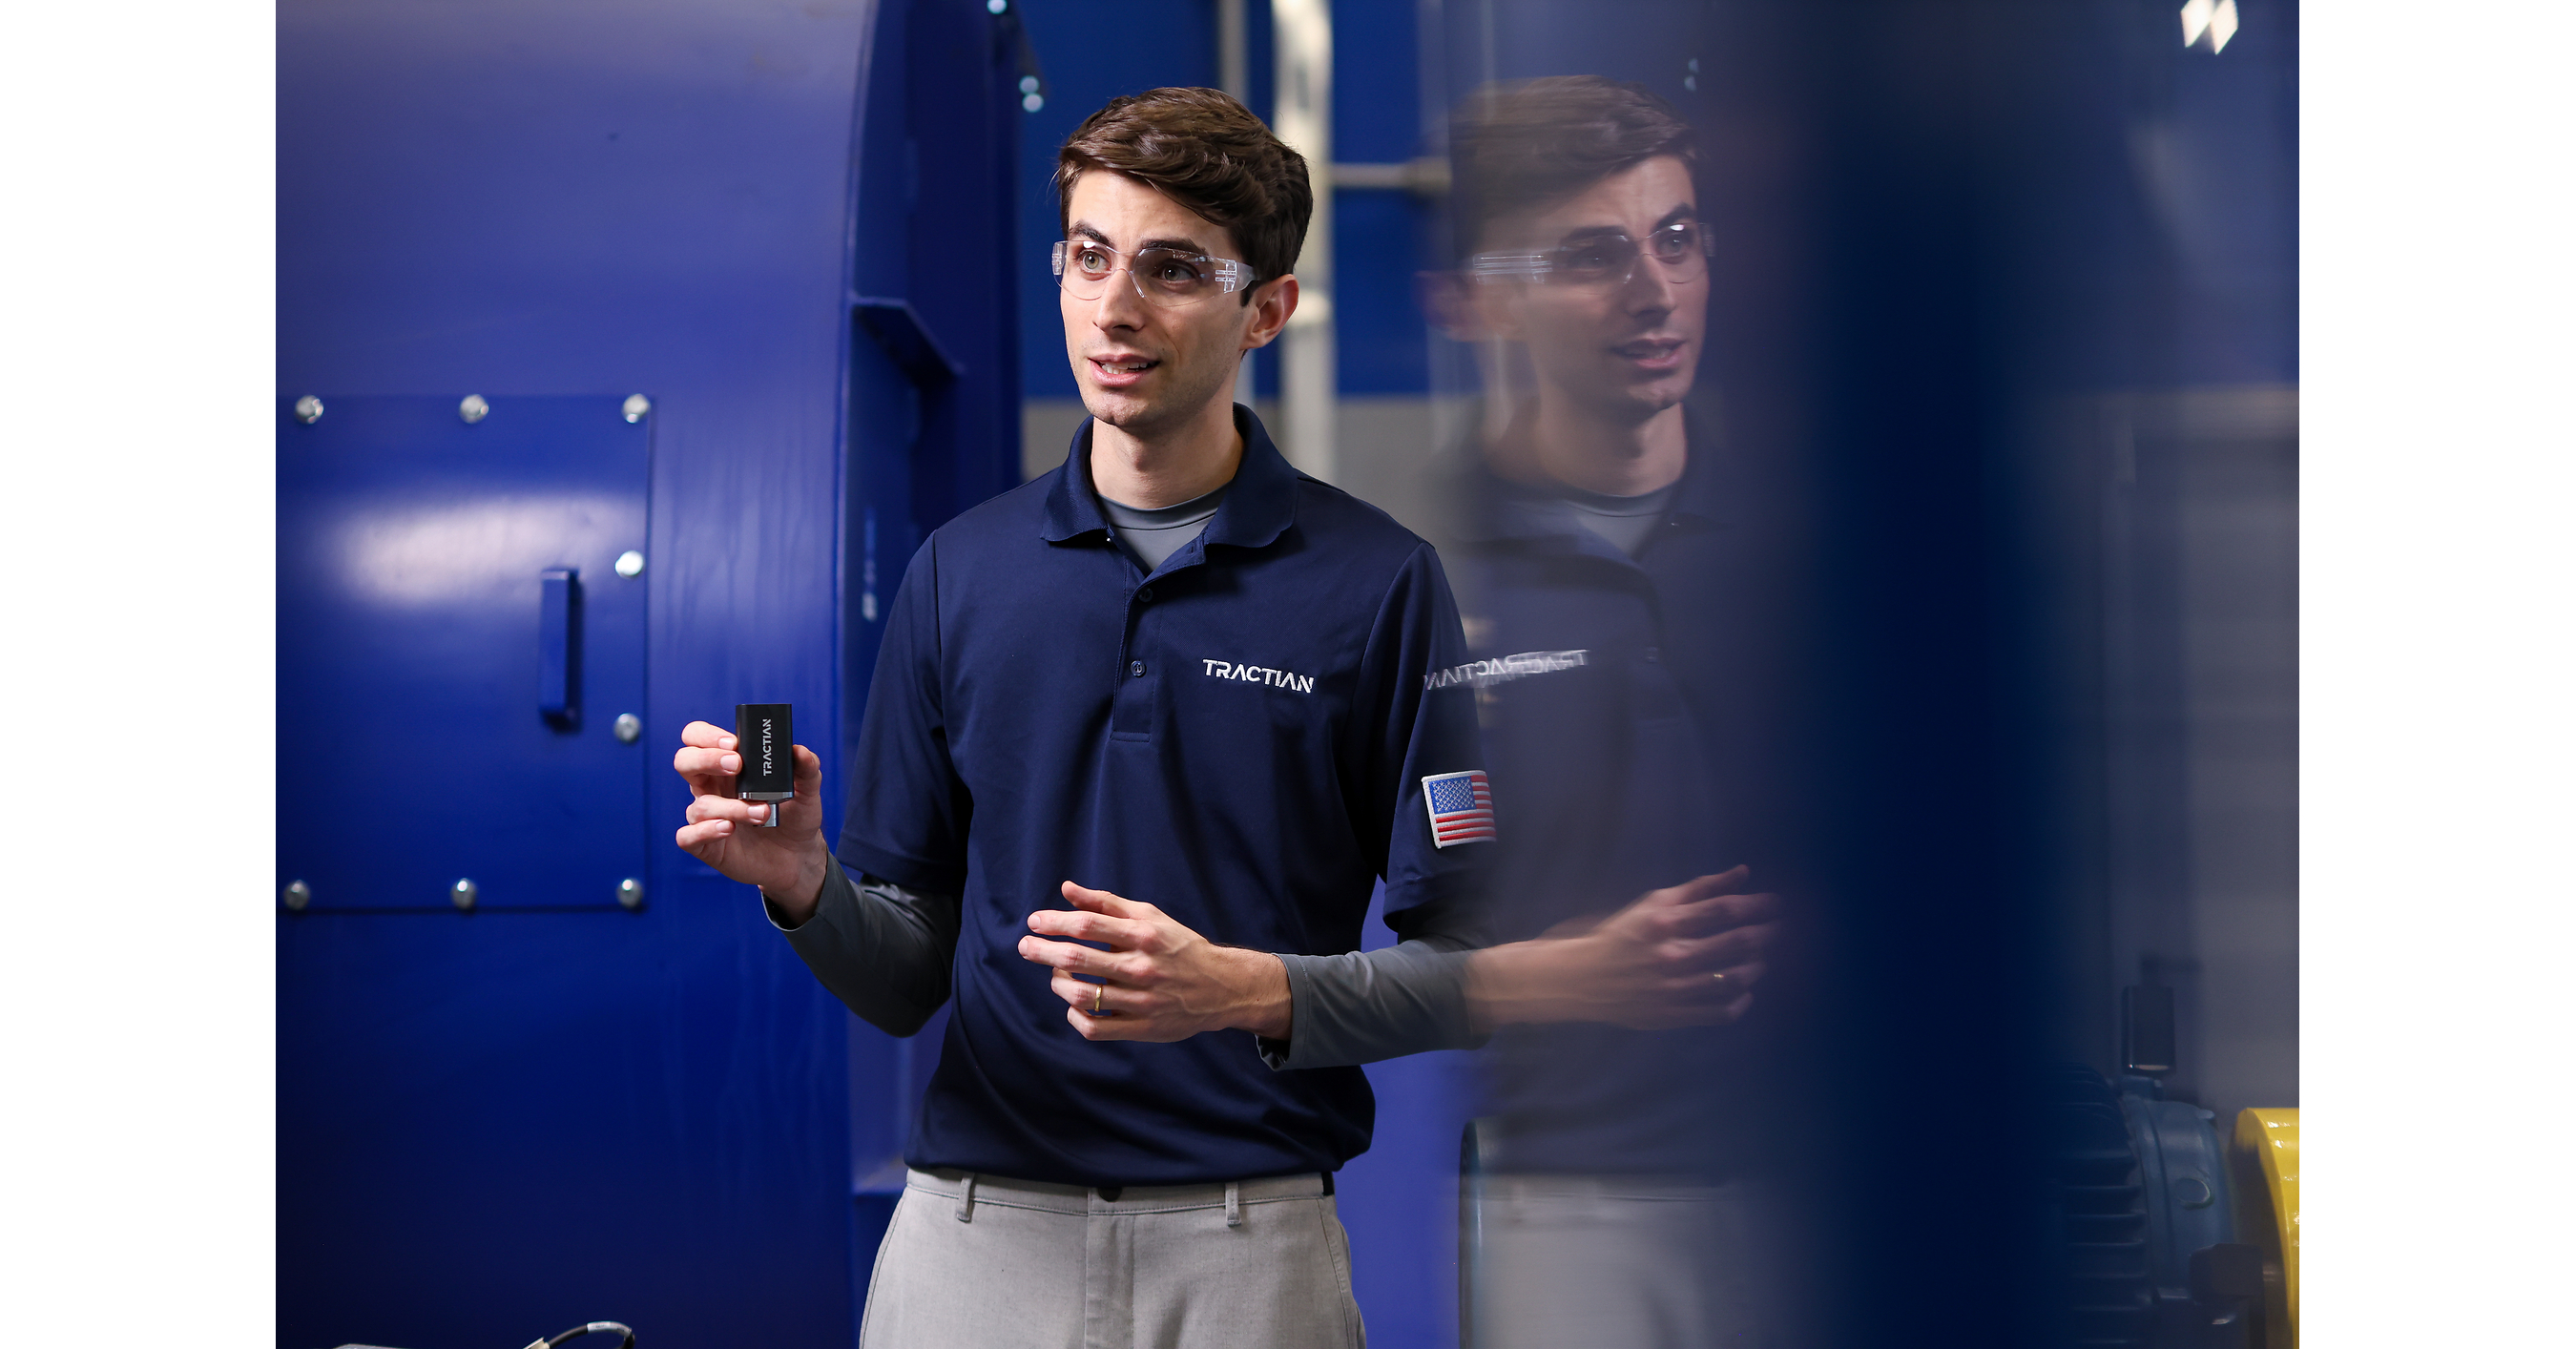
Tractian raised $130 million in a Series D led by Sapphire Ventures and co-led by M&G's Catalyst, valuing the company at $1.4 billion. The funding will support expansion of its AI-powered industrial asset-health platform, which is used across more than 2,000 critical facilities worldwide. The company cites unplanned downtime costs of roughly 11% of annual revenue for the world's 500 largest industrial companies, or about $1.4 trillion annually.
Analysis
The round is a validation signal for industrial predictive maintenance, not evidence of near-term earnings upside for the named public-company customers. References to Eli Lilly, McKesson, Whirlpool, Coca-Cola, Cummins and Embraer establish neither contract size nor realized savings; any equity read-through is negligible absent disclosure of deployment scope, pricing and downtime reduction. M&G Catalyst’s participation likewise does not establish a material earnings contribution to M&G plc.
The strategic prize is turning sensor alerts into technician actions. If the system works across equipment types, it can reduce unplanned downtime and preserve scarce maintenance know-how; customers may capture most of that value through avoided losses, while vendors compete for recurring software and sensor revenue. Tractian’s claimed data advantage is conditional: it must produce better outcomes across varied sites, not merely accumulate machine signals. Incumbents such as Siemens, ABB, Emerson and PTC can counter with installed-base access, controls integration and service relationships; an independent platform’s cross-vendor neutrality is its counterweight.
Near term, this is private-market sentiment, not a listed catalyst. Over 1–3 months, verify customer deployments and quantified outcomes; over 6–18 months, watch whether integrations expand from pilots to paid, multi-site rollouts. Key reversal risks are false alerts, difficult integrations, cybersecurity concerns, slow industrial procurement, and savings that fail to exceed sensor and software costs. The $1.4bn private valuation cannot be assessed without revenue, growth, dilution and round terms; the release’s scale and AI claims are company assertions, not independently verified economics.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.65
Ticker Sentiment
Key Decisions for Investors
- No trade in CMI, EMBJ, KO, LLY, MCK or WHR on customer mentions alone. Treat these as potential operational users, not demonstrated beneficiaries; revisit only with disclosed deployment breadth or measurable uptime, maintenance-cost or yield improvements.
- Place Siemens, ABB, Emerson and PTC on a competitive watchlist rather than taking a directional position: evidence that Tractian converts pilots into multi-site contracts would strengthen the independent-platform thesis; bundled incumbent offerings or weak renewal/expansion data would weaken it.
- Set a diligence alert for independent customer evidence: paid sites, contract expansion, retention, time-to-value, quantified downtime reduction, and sensor/software costs. Without these, do not extrapolate the financing valuation into public-company revenue or comparable multiples.
- For M&G plc, do not infer material listed-company exposure from Catalyst’s participation; verify the investment vehicle and financial contribution before considering any read-through.
More News
- Pepsi renews contract with Taco Bell days after KFC switches to Coke in the U.S.
- US tech stocks tumble as investors fret over AI spending
- Asian shares wobble as tech rout boosts bonds, dents rate hike bets
- Asia stocks fall as AI rout batters S.Korea; Japan spooked by strong CPI
- AI debt and French bonds face a stress test — why it may not be over
- Nasdaq 100 Drops as Oil Rise Fuels Risk-Off Mood