
Midterm Elections: Rising US Diesel, Heating Oil Prices Hit Voters in Key States
Source: Bloomberg
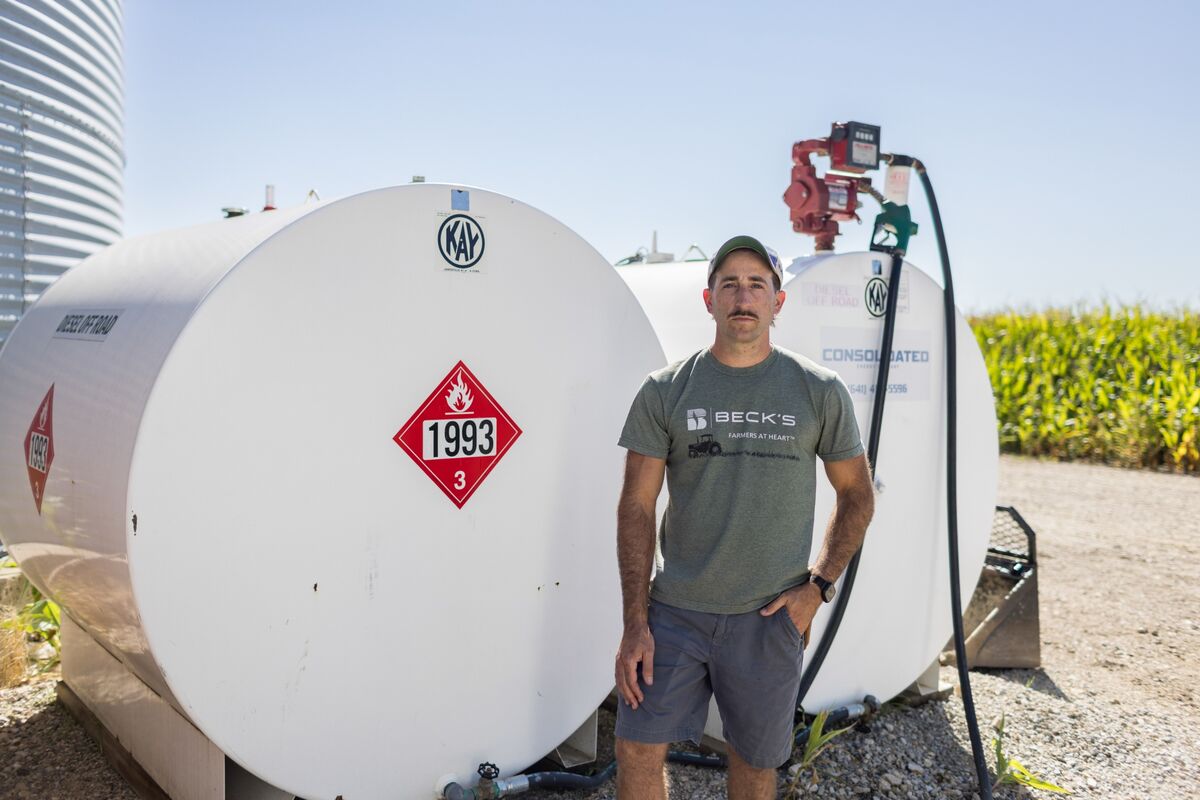
Record-high diesel prices are raising fuel costs for farmers entering the harvest period and for homeowners preparing to refill heating-oil tanks ahead of winter. Iowa farmer Kinser Jensen delayed diesel purchases after prices surged at the start of the Iran war, but faces increasing costs as harvest approaches within weeks. The price shock is particularly sensitive in key battleground states, adding pressure to farm economics and household energy budgets.
Analysis
The investable transmission is the distillate crack, not simply crude direction. VLO, MPC and DINO have disproportionate near-term upside if ULSD margins stay elevated, particularly through export exposure and refinery configurations geared toward middle distillates; the caveat is that an emergency export restriction, SPR-related policy response, or mandated inventory build could compress the crack faster than crude falls. The relevant confirmation is whether NY Harbor ULSD cracks remain above their five-year seasonal range for 2-4 weeks rather than a one-day headline spike.
Agricultural equipment is a delayed loser rather than an immediate earnings casualty. Higher fuel costs reduce farm cash flow during the period when operators make post-harvest machinery, parts and precision-ag purchasing decisions, creating downside risk to 2026 order books for DE, CNHI and AGCO if crop prices do not offset the input shock. DE is relatively insulated by parts/service and large-farm exposure, while CNHI and AGCO have greater sensitivity to lower-income farm customers and dealer inventory normalization.
The overlooked political channel is consumer heating expenditure: a sustained distillate shock acts like a geographically concentrated tax on rural households, potentially raising odds of intervention aimed at retail fuel prices rather than producer economics. That makes pure refinery longs vulnerable to policy headlines even if fundamentals remain constructive. Consensus may also be too linear on refiners: a sharp crude rally can destroy demand and working capital, while a widening diesel-gasoline spread is the cleaner signal of refinery earnings upside.
Over a 1-3 month horizon, monitor USDA farm-income revisions, used-equipment auction prices, dealer inventory commentary and ULSD implied volatility. A meaningful decline in diesel cracks, a ceasefire-driven normalization in shipping/insurance costs, or resilient North American equipment orders would falsify the bearish equipment leg; an export-control announcement would invalidate the refinery leg immediately.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately negative
Sentiment Score
-0.48
Key Decisions for Investors
- Initiate a 1-3 month pair trade: long VLO or MPC / short CNHI, sized beta-neutral. The thesis is a sustained distillate-margin windfall versus delayed pressure on lower-end farm equipment demand; target a 10-15% relative return, and exit if the ULSD crack falls back inside its seasonal average for two consecutive weeks.
- Prefer DINO over broad XLE for tactical distillate exposure only if its diesel crack exposure is confirmed in upcoming operating data. Use a 5-7% stop because DINO carries greater execution and regional-margin risk than VLO/MPC, but offers higher earnings torque if inland diesel differentials widen.
- Buy 3-month VLO or MPC call spreads rather than outright shares if implied volatility remains below the post-shock range; cap premium at approximately 1% of portfolio NAV. This limits downside from a rapid geopolitical de-escalation or fuel-export intervention while retaining crack-spread upside.
- Place an earnings watch, not a directional short, on DE: downgrade to an active short only if dealer commentary shows rising used-equipment inventory or if 2026 North American large-ag order guidance is cut. Fuel costs alone are insufficient to overcome DE's higher-margin aftermarket and replacement-cycle support.
- Avoid broad long crude as the primary expression. A crude rally without a widening diesel-gasoline spread benefits integrated producers more ambiguously and increases demand-destruction risk; use ULSD futures or refinery equities to isolate the relevant exposure.
More News
- LNG Buyers Turn to US as Hormuz Crisis Forces Supply Rethink
- Yield on 10-year Treasury hovers above 5% as investors await Fed decision
- Trump may insist war in Iran is ‘small potatoes’—but it’s costing $3 billion a month, with $38 billion already spent, reports budget watchdog
- Citi sees oil prices supported by geopolitical risks and demand
- EU Proposes Canada to Become First ‘Associate Member’; Fed Decision on Deck
- Workers at German auto supplier Bosch call for EU action to stem job losses