
TCL Solar C2 back-contact panels arrive in Europe, open for order
Source: PR Newswire
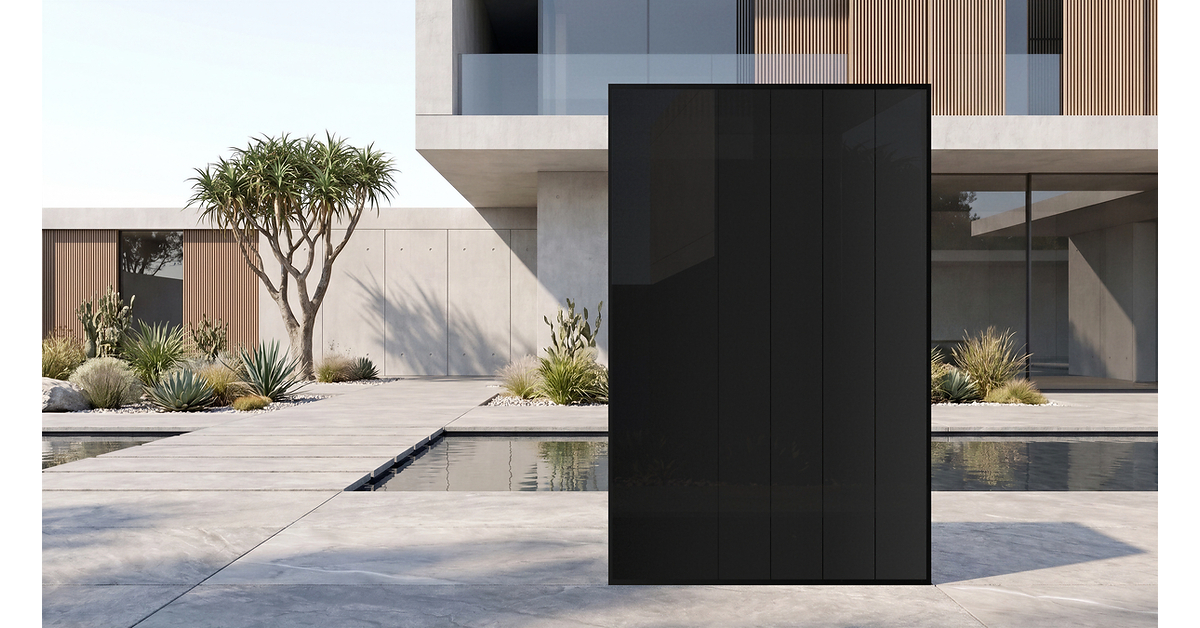
TCL SunPower Global has begun European deliveries and opened orders for its TCL Solar C2 back-contact panel range, starting in the UK this week. The residential C2 S Black delivers up to 495W at 23.8% efficiency, while commercial and utility-scale C2 L variants reach 670W and 24.8% efficiency with up to 85% bifaciality. TCL says the platform provides more than 5% higher usable power density than comparable front-contact designs, alongside annual degradation below 0.35% and warranties of up to 25 years for the product and 30 years for power output.
Analysis
This is strategically more relevant to SPWR’s channel economics than to near-term consolidated earnings: a differentiated module can raise installer attachment to the SunPower ecosystem and improve distributor mindshare, but European module procurement remains dominated by bankability, delivered €/W, credit terms and warranty enforceability. The claimed efficiency and degradation advantages matter only if they reduce balance-of-system and rooftop-area costs enough to offset a likely premium; independent IEC certification, delivered pricing and early field-performance data are the missing variables.
Near term (days to 1 month), the press release is unlikely to change valuation without disclosed European purchase orders, distributor inventory commitments, or gross-margin guidance. Over 1-3 months, watch whether the launch pulls demand from premium back-contact peers such as MAXN and REC’s private-market offering, while exerting little pressure on Chinese commodity-module vendors including JKS, CSIQ and FSLR, whose utility-scale competitiveness is principally cost and financing driven. A more meaningful second-order risk is channel conflict: premium TCL-branded hardware could dilute SunPower’s system differentiation unless battery, financing and installer-service attach rates rise concurrently.
The structural upside over 6-18 months is that acquired back-contact manufacturing could give TCL/SPWR a credible premium-product supply base while European rooftop constraints favor watts per square meter. The contrarian view is that European oversupply and falling module prices make technology premiums harder—not easier—to monetize; higher-efficiency products may accelerate ASP compression if TCL uses them to buy distribution. Thesis is falsified by weak sell-through despite broad availability, warranty-reserve increases, or no improvement in SPWR’s gross margin and European channel metrics by the next two reporting cycles.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Ticker Sentiment
Key Decisions for Investors
- No standalone directional SPWR trade on this release. Set an alert for disclosed European orders, distributor inventory terms, independently verified certifications, and realized module ASP/gross margin; absent these, the announcement is a product-marketing catalyst rather than an earnings catalyst.
- For a 3-6 month relative-value watch, consider long SPWR only against short MAXN after evidence of European premium-channel sell-through. The mechanism is share capture in constrained rooftop installations; exit if SPWR does not show sequential European revenue or margin improvement within two earnings reports.
- Avoid using JKS or CSIQ as direct shorts against this launch: their exposure is weighted toward cost-sensitive utility and global markets, where a premium back-contact offering is not a clean substitute. A European module-price decline remains the larger risk to all manufacturers.
- For existing SPWR exposure, cap sizing until balance-sheet and warranty obligations are clear. A 10-15% move on order headlines is plausible in a low-liquidity solar-equity tape, but durable upside requires verified gross-margin expansion rather than shipment announcements.
More News
- China's AI chip blitz arms Xi with a message for Trump: 'You can't choke us off'
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- US aviation sanctions disrupt Iran flights, push travellers overland
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
- Why Trump banning diesel exports would upset the U.S. oil sector and upend global fuel markets — ‘the cure would be far worse than the disease’
- Meta's standoff with Amazon over Muse could be a sign of things to come
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?
- What Is a Financial Ontology?