
Hemlo Mining Corp. Announces Refined Porphyry Model Supporting District-Scale Potential Across its 45,000-Hectare Land Package
Source: PR Newswire
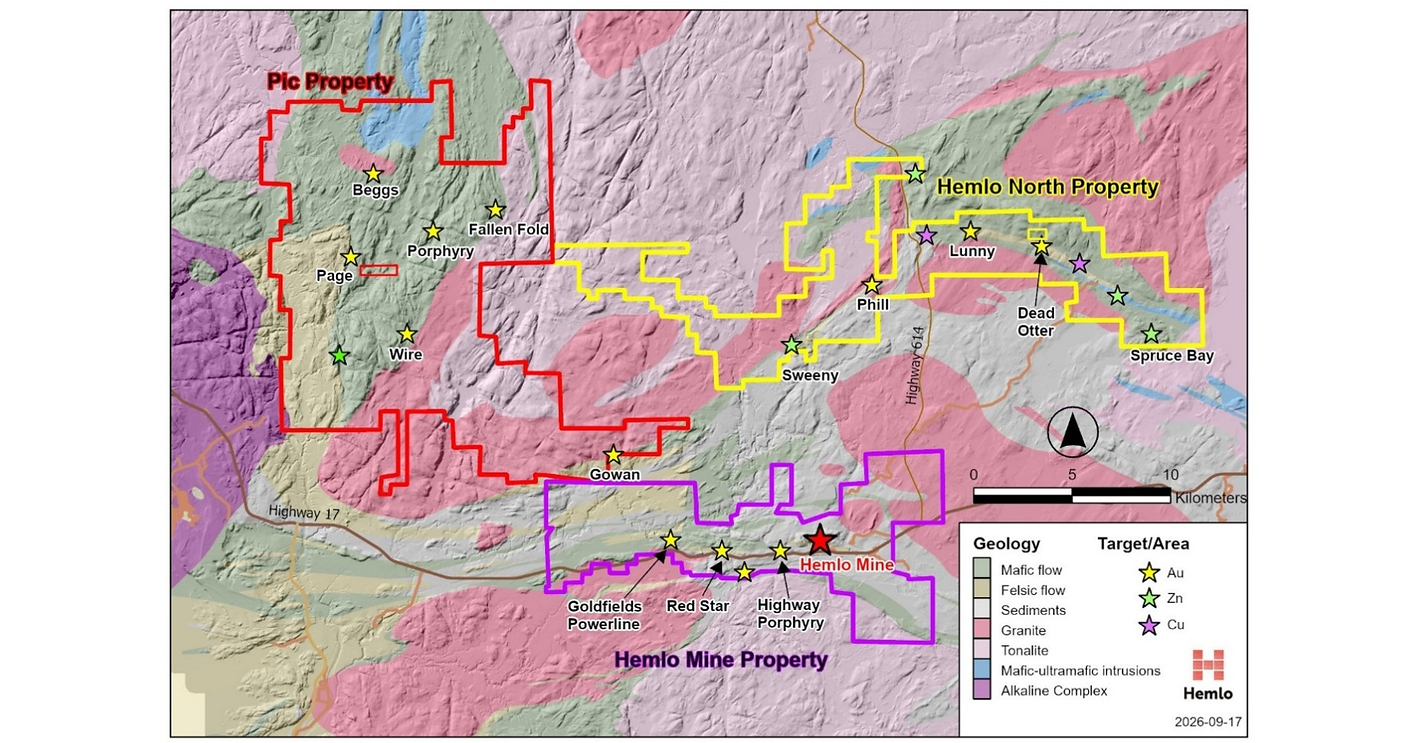
Hemlo Mining unveiled a revised porphyry-epithermal gold-molybdenum exploration model for its approximately 45,000-hectare Hemlo land package, targeting potential district-scale mineralized systems beyond the 25-million-ounce Hemlo mine. Its priority Pic Property contains historical results including 133.2 g/t gold over 2.0 m at Super G and 2.6 g/t over 18.7 m at Wire, although these data have not been independently verified. Fieldwork begins in September 2026, airborne geophysics is planned for late 2026, and initial drill testing is targeted for 2027.
Analysis
HMMC is attempting to convert a single-asset producer valuation into a district-scale exploration multiple, but the market should assign little NAV today: no current-resource estimate, verified drilling, or defined budget accompanies the regional thesis. The near-term value is optionality rather than cash-flow change; a successful reinterpretation could extend mine-life assumptions and reduce the terminal-value discount embedded in an aging operating asset, while a failed validation exercise leaves operating execution as the only support for equity value.
The most important distinction is between high-grade, narrow historical showings and an economic bulk-tonnage system. The revised model increases target generation efficiency if correct, but it also raises the risk that management markets visually compelling surface evidence without demonstrating continuity, metallurgy, strip ratio, or mineable widths. The molybdenum association is not necessarily additive: unless recoverable grades and processing compatibility are established, it may introduce metallurgical complexity rather than by-product credits.
Immediate upside could come from pending regional assays and airborne-survey target definition over the next 1-3 months, but the decisive catalyst is first modern drill data in 2027. Liquidity is likely limited for a small Canadian issuer, making any press-release-driven move vulnerable to reversal absent independently verifiable results. A weaker gold price, dilution to fund drilling, or failure to replicate historical intercepts under current QA/QC would compress the exploration premium rapidly.
Contrarian view: the promotional framing may be underestimating the time and capital needed to turn a geological analogy into ounces, but the market may also be underpricing near-mine upside if western extensions can be tied into existing infrastructure. That latter outcome is materially more valuable per discovered ounce than a remote standalone discovery because permitting, access, and processing-capex requirements could be lower; it requires continuity evidence, not simply analogous alteration signatures.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.34
Ticker Sentiment
Key Decisions for Investors
- No new core position in HMMC before independently reported, modern drill assays; treat upcoming field, geophysics, and historical-data validation updates as liquidity events rather than fundamental catalysts.
- For a high-risk exploration sleeve, consider a starter HMMC position only after the first verified results demonstrate repeatable mineralization over economic widths; cap exposure at 25-50 bps of NAV given binary 2027 drilling risk and likely financing dilution.
- Use a catalyst ladder: add only if pending assays validate target vectors, then reassess after airborne geophysics identifies coherent drill targets; exit if the company delays 2027 drilling, materially expands its financing need, or reports non-continuous/narrow mineralization.
- Monitor gold-price sensitivity through GDX/GDXJ rather than assuming HMMC-specific news will dominate. A sustained gold correction can overwhelm exploration optionality and create a better entry point before drilling; conversely, a gold rally may inflate HMMC ahead of evidence, favoring profit-taking into promotional strength.
More News
- Oil falls on increased Gulf supply and hopes for US-Iran talks
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- Latest Oil Market News and Analysis for Sept. 23
- Bank of America says Brent crude oil could top $150 a barrel if Iran war disruptions persist
- Paramount will need to release way more movies to make this merger work
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: AI-Powered Report Editing, Investor Relations, and Enhanced Search
- Automating Financial Model Updates: A Source-Controlled Workflow