
Polish Debt Collector Kruk Eyes US, UK as Europe Loses Momentum
Source: Bloomberg
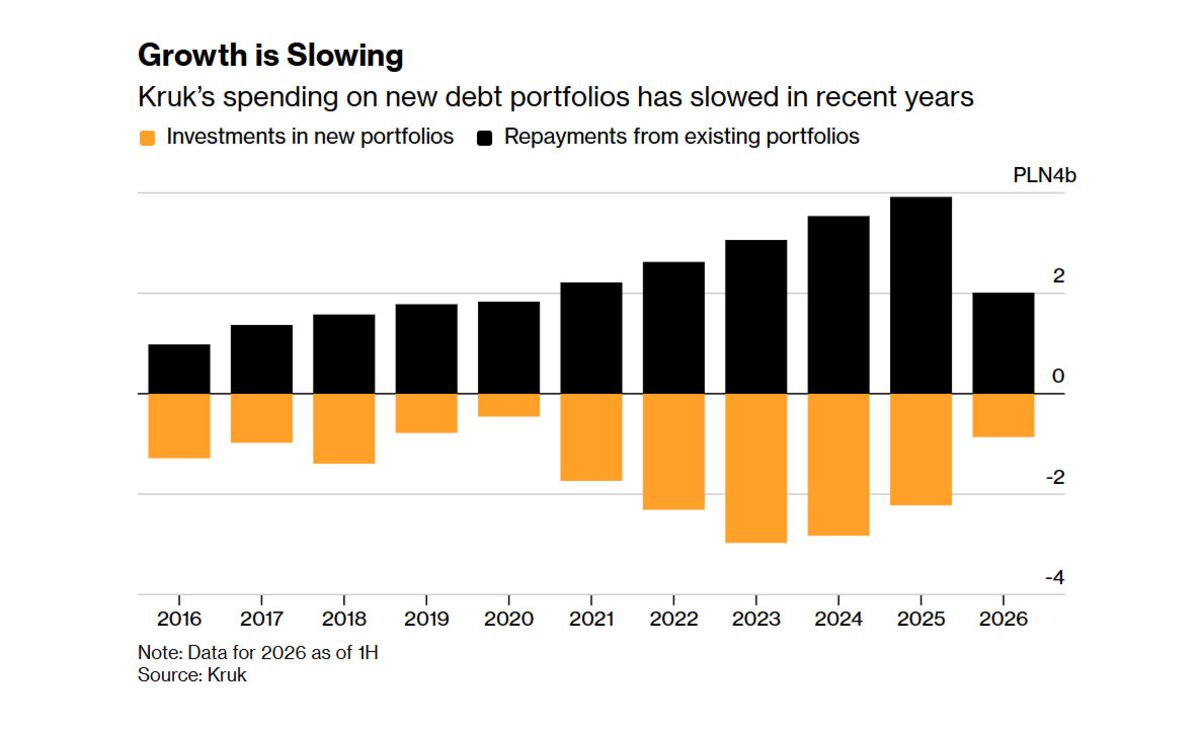
Kruk SA is pursuing US and UK expansion as growth in continental Europe loses momentum, CEO Piotr Krupa said. The Polish debt collector is considering direct purchases of debt portfolios and opportunistic acquisitions of profitable competitors in both markets; no deal or financial terms were disclosed. Founder Krupa owns an 8.7% stake.
Analysis
Kruk’s proposed move is an option on growth, not yet evidence of a new earnings engine. The key economic question is whether it can source portfolios at prices that preserve collections returns after local servicing costs, funding, and compliance—not whether it can enter the markets. US and UK incumbents such as PRA Group and Encore Capital have local scale and data advantages; bidding against them could compress returns. Acquiring a profitable operator may accelerate access to those capabilities, but introduces integration and valuation risk. A failed or overpriced entry could also divert capital from Kruk’s established European operations just as their momentum is weakening.
Near term, the announcement may support sentiment, but no deal terms or return hurdles are provided to underwrite a re-rating. Over 1–3 months, watch for a named target, portfolio purchase price, funding source, and expected collection yield. Over 6–18 months, the test is contribution to collections and cash generation without weakening leverage or returns on invested capital. UK FCA requirements and fragmented US state-level rules make execution and compliance costs material risks. The contrarian point: geographic diversification may look attractive precisely when Europe slows, but entering competitive markets at the wrong point in the credit cycle can buy volume rather than profitable growth. Falsify a constructive view if management signals large commitments without disclosed return discipline, or if subsequent reporting shows weaker cash generation, rising leverage, or disappointing acquired-portfolio collections.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No immediate trade on the announcement alone: treat KRU as a watch, since entry economics, financing, and timing are unspecified.
- Consider a staged long only after a concrete US or UK transaction is disclosed and management provides credible return, funding, and integration parameters; avoid paying for unverified expansion optionality.
- For any deal, monitor acquired-portfolio collections and cash generation against expectations, alongside leverage and returns on invested capital. Weak performance or capital deployment that pressures those measures would invalidate the expansion thesis.
- Track competitive pricing and regulatory execution in both markets; a portfolio purchase without a credible local servicing capability, or an acquisition at an aggressive valuation, raises the risk that growth dilutes returns.
More News
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
- Israel’s economy prospers despite years of war, but prices worry voters
- Verizon stock heads for worst day since 2002 as SpaceX U.S. network plans whack telcos
- Rising fuel costs slashed Delta’s profit outlook despite strong demand
- ‘I drive a Tesla’: After Elon Musk said he’d lose his job, Delta CEO Ed Bastian says there’s ‘no tit for tat’ as airline unveils earnings miss
- Why is the Chinese stock market missing the AI rally
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI
- How to Track Earnings Call Sentiment Across Companies