
SI Group Announces CEO Leadership Transition
Source: PR Newswire
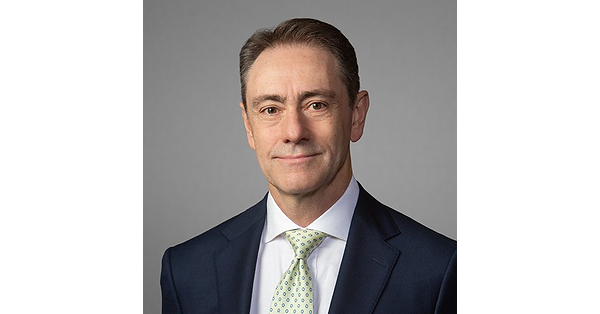
SI Group appointed Marcello Boldrini CEO effective October 19, 2026, succeeding David Bradley, who had led the company since 2019. Boldrini previously led Kraton Corporation and oversaw transformation initiatives that generated more than $100 million in annual EBITDA improvements there. SI Group’s board cited the company’s successful 2025 recapitalization as strengthening its financial position; no new financial guidance or operating targets were announced.
Analysis
This is a governance and execution watch item, not a clean public-equity catalyst: SI Group is not represented in the supplied ticker mapping, and the article provides no operating targets or recapitalization terms. A CEO with a transformation-office track record raises the possibility of tighter cost control, plant productivity work, portfolio pruning, and working-capital discipline over the next 6–18 months. Those levers could improve SI Group’s competitive position, but the cited EBITDA improvement at a different business is not evidence of transferable results; verify any benefits in SI Group’s own operating data. Near term, leadership handoff creates modest execution risk in a process-sensitive business: customer qualification and reliable supply matter, so disruption could create openings for competing specialty-chemical suppliers. The 2025 recapitalization may reduce financial fragility, but without terms we cannot assess leverage, covenants, or investment capacity. The contrarian read is that a transformation-oriented appointment may signal a need for further remediation rather than imminent growth. No direct read-through to Ashland (ASH): the article only cites Boldrini’s earlier employment there, with no current relationship or Ashland-specific change. Falsifiers of the operational-upside thesis include no measurable improvement in service reliability, costs, or working capital over coming quarters, or evidence that savings require cuts that impair customer retention.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No immediate ASH position: the supplied identity mapping is Ashland Inc., and the article establishes no current Ashland exposure to SI Group or change in Ashland fundamentals.
- Treat this as a watch item for publicly traded specialty-chemical competitors rather than a trade. Look for evidence of customer qualification wins, order transfers, or improved utilization before taking a relative-value position.
- Over the next 1–3 months, seek SI Group-specific updates on leadership appointments, plant reliability, customer retention, and capital allocation; verify recapitalization terms before drawing conclusions about balance-sheet risk.
- Reassess the transformation thesis over 6–18 months against disclosed operating metrics. If execution improves without service deterioration, competitors may face incremental pricing or share pressure; if customer disruption or underinvestment emerges, the disruption risk may outweigh prospective cost savings.
More News
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Walmart’s Flipkart is quietly building a food delivery challenger in India
- Credit stress is threatening to unwind the AI bull. All eyes are on Oracle to hold the line
- LightStream stops accepting loan applications. Try these 6 lenders instead
- Ciena EVP DiPerna sells $308,865 in CIEN stock
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI in Asset Management: 2026 Statistics That Hold Up
- What is Broker Research and RMS Systems (And How to Actually Use Them)