
Purina Opens New Pet Food Factory in Ohio, Its First Built from the Ground Up in More Than 50 Years
Source: PR Newswire
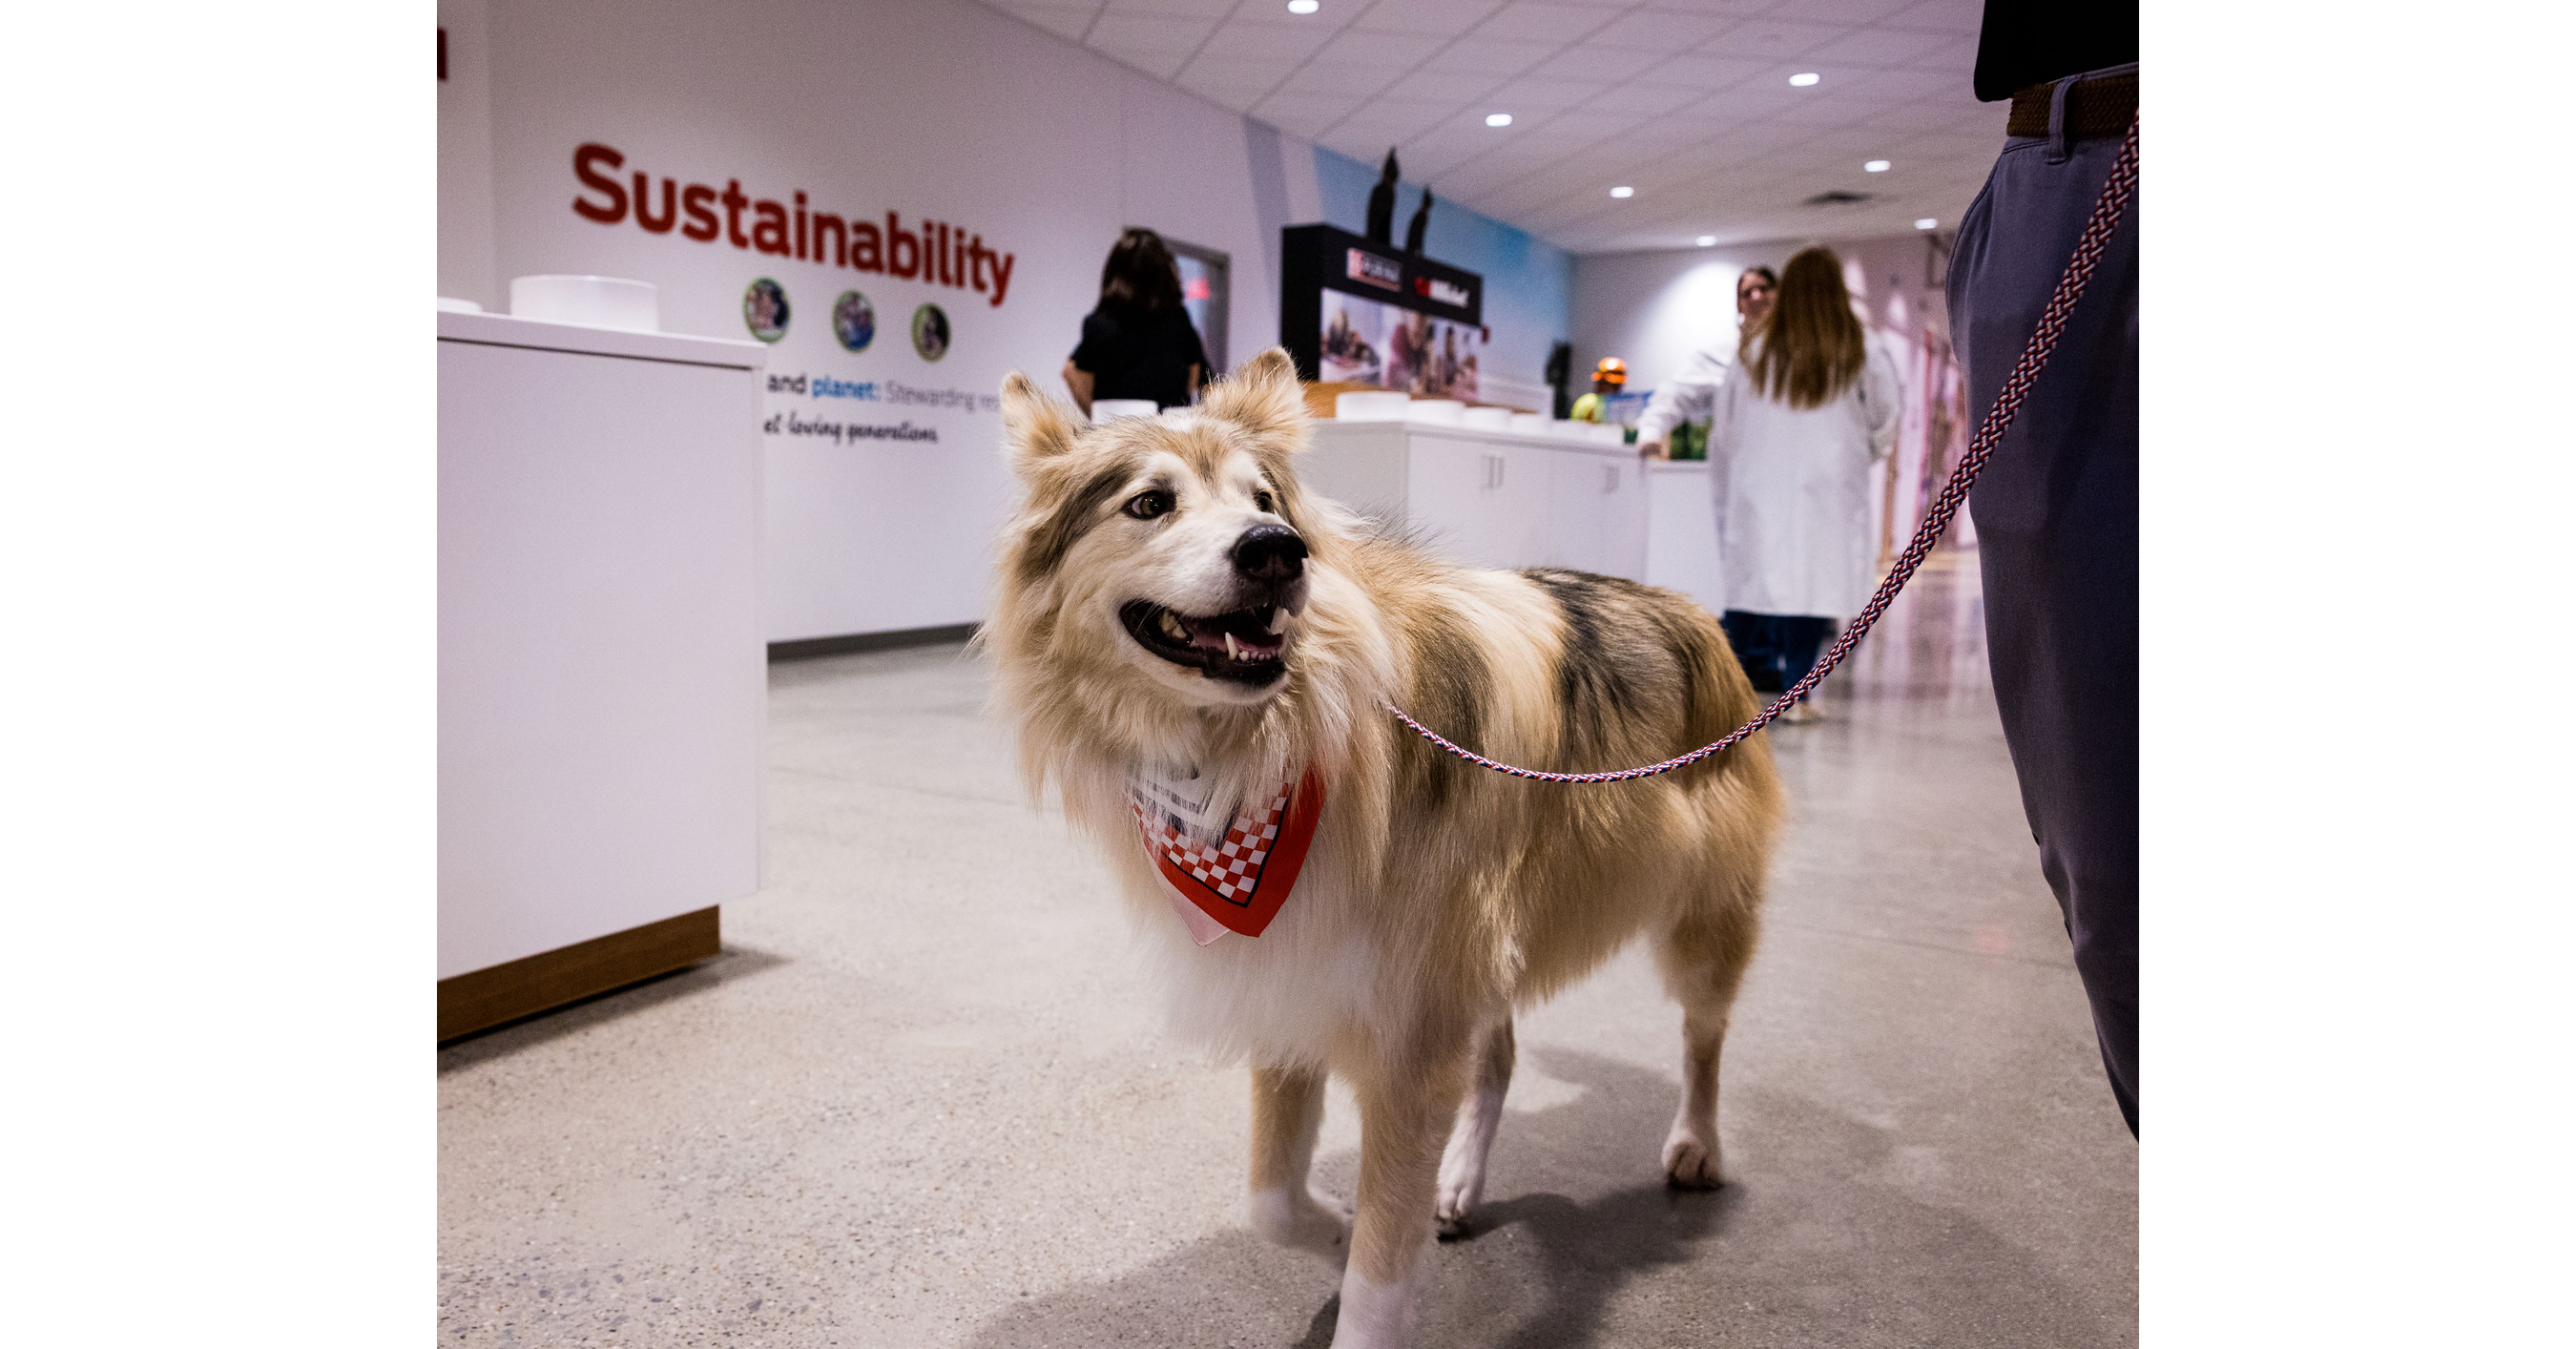
Purina officially opened its new Batavia, Ohio pet food facility, a $550M+ investment and its largest Purina manufacturing build since 1975. The 1.3M sq-ft plant is already producing brands (Pro Plan, ONE, Dog Chow), employs 430+ associates with plans to exceed 500, and targets feeding ~8 million pets annually. The factory’s “digital manufacturing tools, robotics and automation” and expanded capacity to meet ongoing consumer demand are framed as a long-term growth and efficiency step, with two additional $30,000 Purina Foundation grants announced during the event.
Analysis
Treat this as a long-duration operating efficiency signal, not a near-term EPS event. In a category with sticky demand and high brand inertia, the economic value is fewer stockouts, lower unit labor, and better SKU flexibility; that tends to protect shelf share and gross margin more than it creates incremental volume. For NSRGY, the real upside is a harder-to-displace pet franchise if trade-down or private-label pressure builds over the next 6-18 months.
The second-order winners are automation, packaging, and warehouse vendors that participate in these builds; the losers are smaller pet-food suppliers and any contract manufacturer without scale. Public proxies most exposed to a more efficient Purina are premium pet challengers like FRPT and, more indirectly, pet retailers such as WOOF/PETS if Purina uses the extra capacity to support tighter fill rates and heavier promotion. This should not be read as a growth re-rating for NSRGY; the more realistic effect is modest margin defense and stronger supply-chain resiliency.
Contrarian view: the spend may be defensive replacement of aging capacity rather than a signal of accelerating end-demand. If pet category volumes soften or input costs rise, utilization risk can dilute the payback and turn a strategic headline into a balance-sheet story. Falsifier: if the next 1-3 quarterly prints show no uplift in pet-care segment margin, service levels, or promotional flexibility, the market should fade the enthusiasm.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- No immediate standalone trade in NSRGY on this release; treat as a watch item and only add on pullbacks if pet-care segment margin expands by >50 bps over the next 2 quarters.
- Relative-value idea: long NSRGY / short FRPT on any premium-pet rally into the next 6-12 months; thesis is scale and automation compressing the valuation gap if Purina uses capacity to defend share.
- Watch WOOF and PETS for promotional pressure over the next 1-2 quarters; if gross margin guidance is cut, this becomes a cleaner short than chasing NSRGY higher.
- Set an alert on NSRGY next earnings: if organic pet growth slows and the new plant does not improve service metrics, fade the move rather than paying up for a capex story.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Brian Sullivan: Why the 'real' price of oil is likely $30-$40 higher than where it is now
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- What's behind the sell-off in AI neocloud stocks like CoreWeave and Nebius
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What Exactly Does Post-Training in LLMs and Finance-Focused AI Actually Mean for Asset Managers?
- What Is a Financial Ontology?