
Zhejiang aims to be highland of AI innovation
Source: PR Newswire
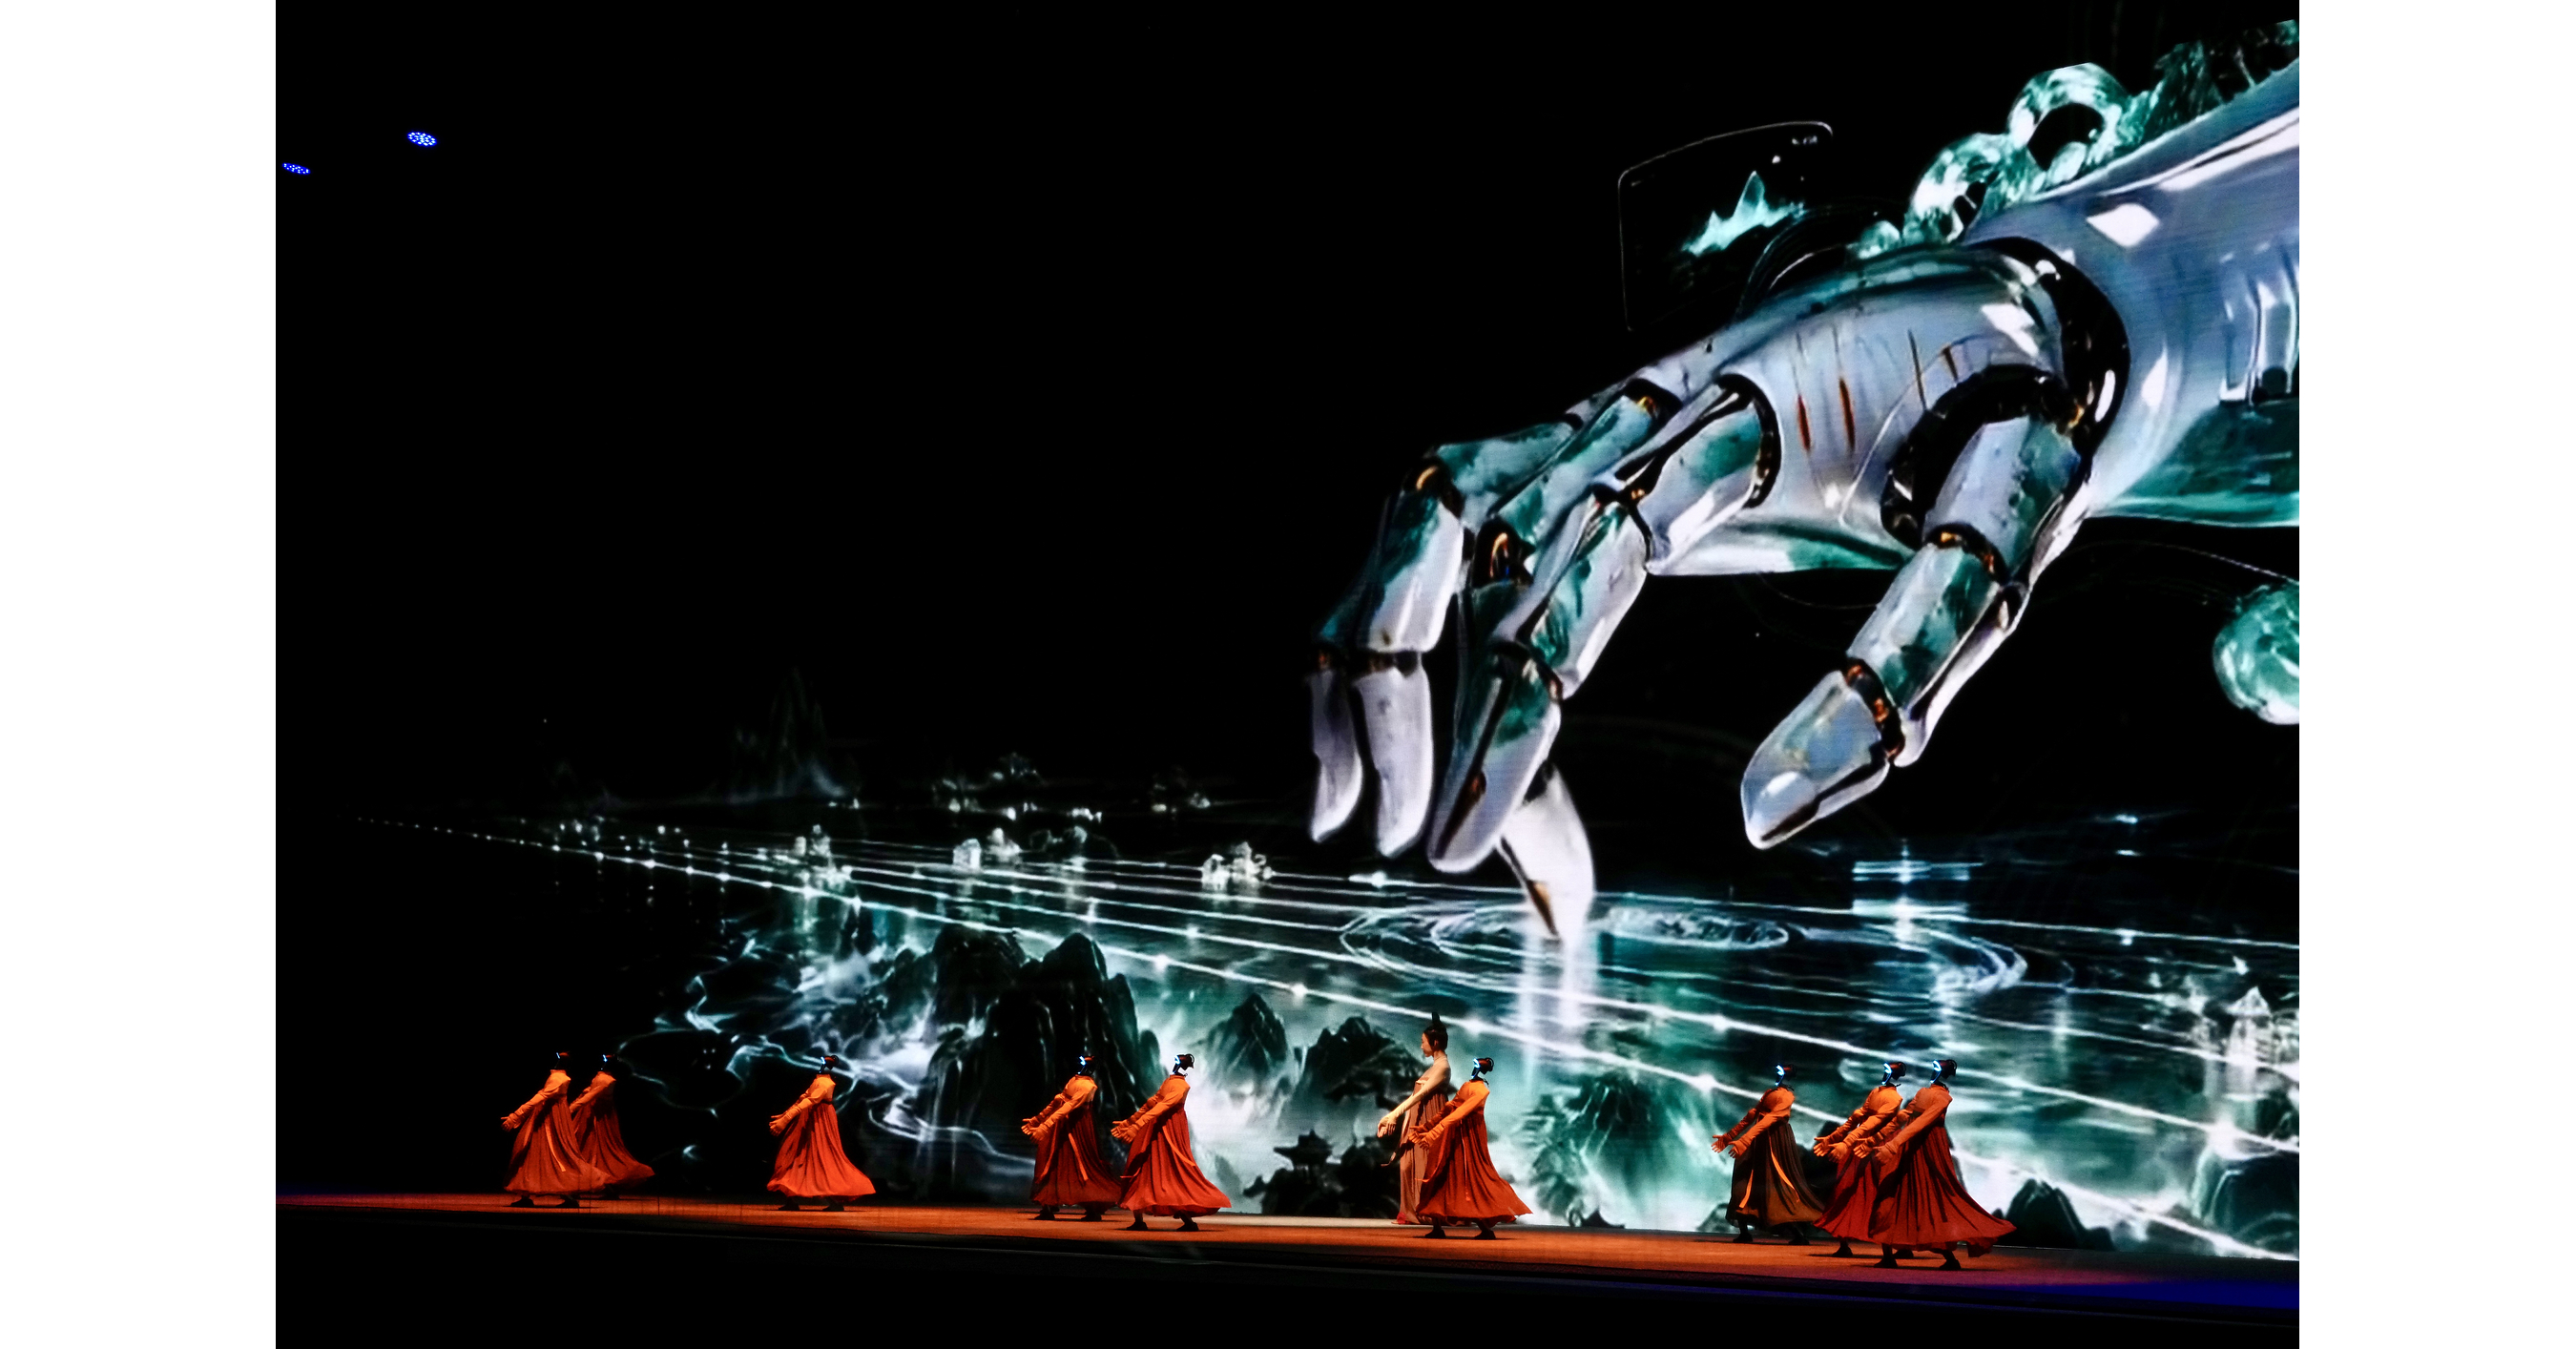
Zhejiang’s core AI industry generated 582.87 billion yuan ($87.2 billion) in revenue in the first eight months of 2026, up 26.9% year over year, as the number of core-industry enterprises reached 2,112. The province reported 197 EFLOPS of computing power at end-September, while 54 organizations received 408 million yuan in national computing-power vouchers. The report highlights Zhejiang’s AI infrastructure, open-source model ecosystem and applications, but does not cite market reactions.
Analysis
This is a policy-and-capacity signal, not evidence yet of attractive AI returns. Zhejiang’s reported industry revenue and compute capacity do not establish utilization, unit economics, or how much value accrues to listed companies; the China Mobile reference is to its Zhejiang branch, not proof of material consolidated earnings impact. Summit project signings are also not realized investment or revenue.
The second-order beneficiary may be manufacturers and merchants adopting cheap AI tools: lower design and content-production costs could support output and export competitiveness even if model providers struggle to charge. Conversely, open-source model proliferation can commoditize inference and pressure pricing; infrastructure wins only if utilization and paid workloads catch up with capacity. Domestic-chip development may gain policy support, but performance, software compatibility, and supply constraints remain key execution risks.
Near term (days), the report may reinforce sentiment toward China AI and infrastructure, but offers little basis for repricing earnings. Over 1–3 months, watch disclosed center utilization, enterprise contracts, compute pricing, and capex orders; the reported vouchers and project signings are not substitutes. Over 6–18 months, sustained adoption could benefit domestic compute/network providers and AI-enabled industrial users, while excess capacity or falling inference prices could impair returns. Contrarian read: headline growth and EFLOPS measure scale, not monetization. Without utilization and cash-flow evidence, avoid chasing broad AI exposure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- No event-driven directional position on this report alone. Treat it as a watch item for China AI infrastructure rather than an earnings catalyst.
- For a conditional relative-value expression, favor established compute/network infrastructure exposure over unproven model/application exposure only after evidence of rising paid workloads, utilization, and orders; do not assume the Zhejiang branch’s activity flows materially to China Mobile’s consolidated results.
- Track China Mobile disclosures and provincial or company-level data for data-center utilization, customer mix, compute-network revenue, and capex. A lack of improving utilization or monetization over the next 1–3 months would falsify the infrastructure-upside thesis.
- Do not capitalize the 100-billion-yuan-plus annual event signings as revenue: verify conversion into funded projects and operating contracts. A slowdown in conversion, falling compute prices without volume growth, or continued weak paid adoption would favor staying underweight speculative AI application names.
More News
- Further turmoil could be in store for tech stocks. What to watch in the week ahead
- Tech stock rout, driven by US AI fears, continues in Asian trading
- Asian Markets Tally Losses From Worsening Global Rout
- AI’s Grip on Financial Markets Was Never Clearer on the Way Down
- Elon Musk once said the Cybertruck would be Tesla’s ‘best product ever.’ Now he’s winding down production
- AI stocks hammered by midterm shock as data center buildout becomes a 'war of attrition'