
Harbinger Receives Order for 2,000 Electric Trucks from FedEx valued at over $300 Million
Source: PR Newswire
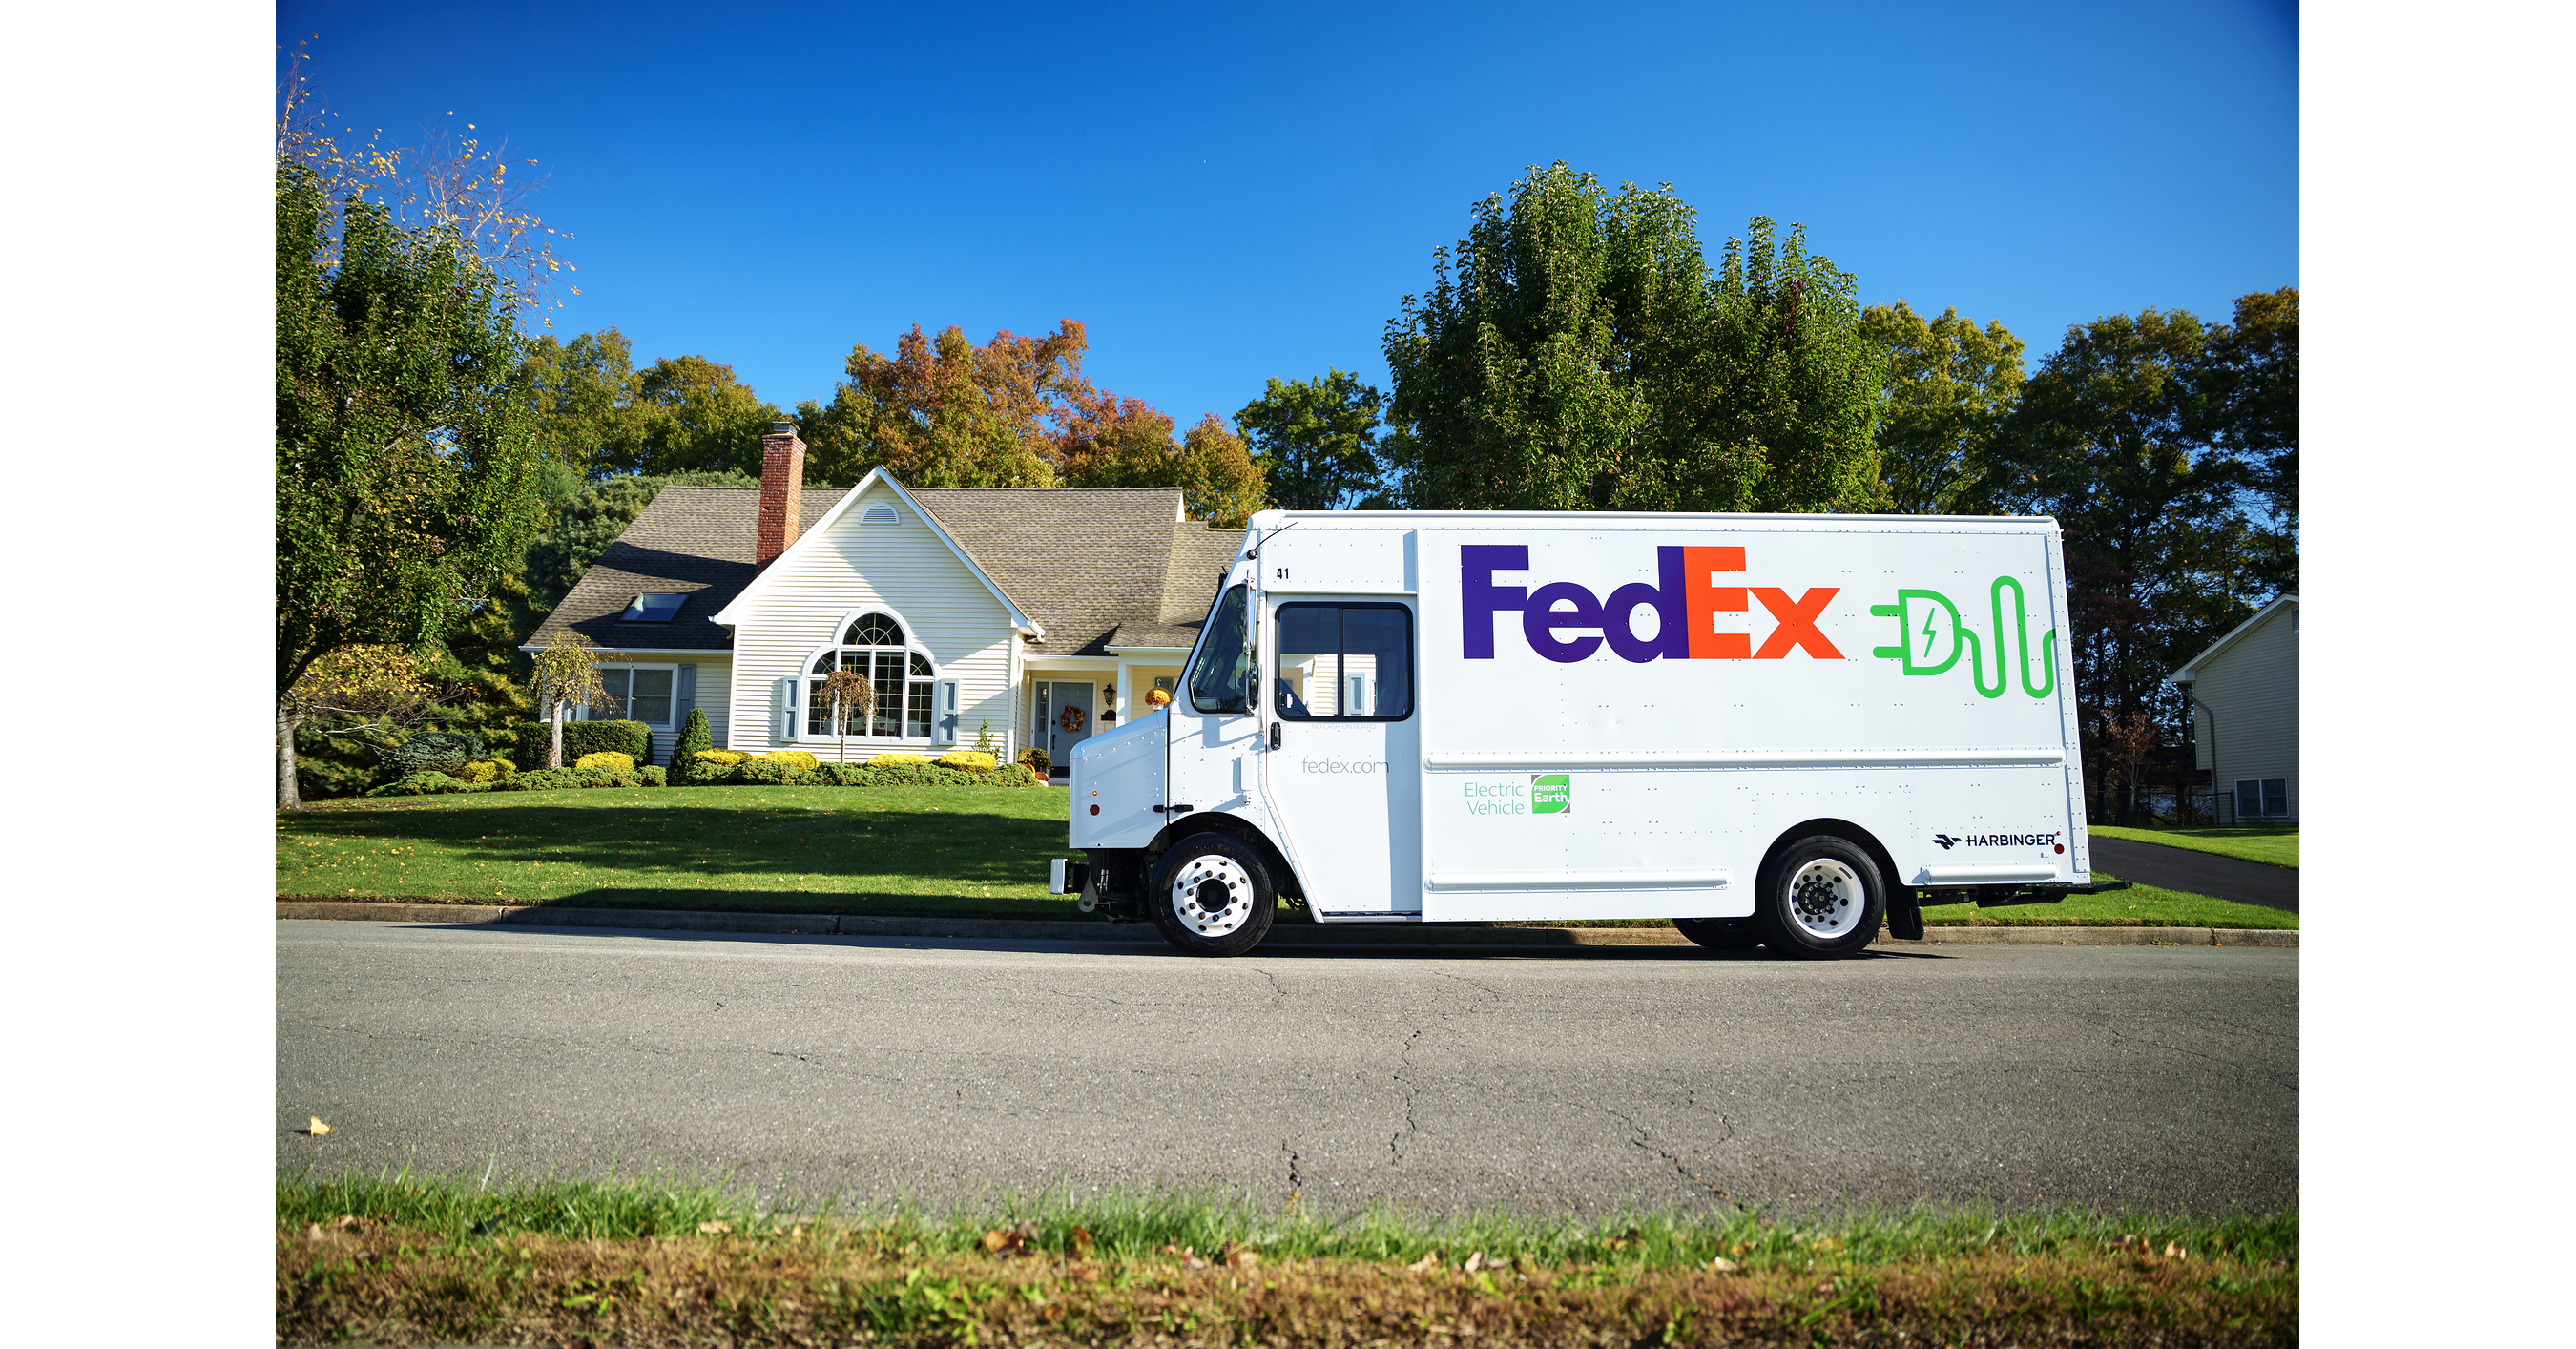
Harbinger received a binding FedEx order for 2,000 all-electric medium-duty trucks valued at more than $300 million, with deliveries across the U.S. and Canada due by the end of 2027. Harbinger plans to build and deliver the vehicles within approximately 18 months; the fleet could generate an estimated $40 million of annual diesel-fuel savings, or $800 million over a 20-year service life. Replacing the diesel vehicles is also projected to avoid more than 1.7 million tons of CO2 emissions over their operating lives, advancing FedEx's fleet-electrification strategy.
Analysis
The economic significance for FDX is less the fleet purchase than whether depot charging and route-level utilization convert a pilot into a repeatable network template. Medium-duty pickup-and-delivery routes are unusually suited to electrification because vehicles return to base, but the benefit is highly sensitive to electricity demand charges, battery availability, and winter range in Canada. If those variables are managed, lower fuel and maintenance volatility can support a modest structural reduction in last-mile cost per stop over 2028-30, strengthening FDX’s yield discipline against UPS and regional carriers.
Harbinger is private, so the direct equity read-through is limited; the more investable second-order beneficiaries are charging and power-management vendors with depot exposure, including BLNK and EVGO only if they disclose awarded infrastructure scope. The near-term risk is that a vehicle order does not equal recognized capex or operating savings: deliveries extend through 2027, and the customer has strategic equity exposure to the supplier, which weakens the order’s value as an independent demand signal. Public medium-duty competitors such as PCAR and CMI face little immediate earnings risk, but a successful deployment could pressure diesel residual-value assumptions and accelerate fleet RFPs in 2027-28.
Consensus may overstate the ESG angle and understate execution optionality. FDX shares should not rerate materially on a multi-year, sub-scale fleet program absent evidence that electrification lowers total cost per route without impairing service metrics. The key falsifier is a rise in FDX capital intensity, missed delivery productivity targets, or an inability to secure depot power upgrades; conversely, disclosed cost-per-stop savings and follow-on orders would make the initiative commercially material.
Over the next 1-3 months, treat this as a diligence catalyst rather than a standalone FDX buy signal. Monitor FDX’s next capex outlook, fleet-maintenance expense trend, utility interconnection commitments, and any disclosure of charging partners; these determine whether the program becomes an earnings lever rather than a long-dated sustainability commitment.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- Maintain FDX at neutral-to-overweight only within a broader parcel thesis; do not add solely on this announcement. Reassess at the next earnings release if management quantifies depot infrastructure capex, cost-per-stop savings, or a 2028 operating-margin benefit.
- Set a 6-12 month alert on UPS versus FDX: consider long FDX / short UPS only if FDX demonstrates stable service levels alongside lower maintenance and energy expense, while UPS does not announce comparable medium-duty deployment. Exit if FDX raises capex guidance without a corresponding margin or productivity bridge.
- Avoid treating BLNK or EVGO as direct beneficiaries until contract awards, equipment volumes, and utility-interconnection financing are independently disclosed. Their exposure to this fleet is otherwise speculative and unlikely to be earnings-material.
- Monitor PCAR and CMI for medium-duty order-book commentary through 2027. A broad fleet shift—not a single customer order—would be the trigger for a tactical underweight, especially if diesel truck residual values or engine demand guidance begin to weaken.
More News
- Wall Street is closing out a strong quarter. Plus, Lilly's mixed obesity drug trial data
- FedEx orders 2,000 electric trucks from Harbinger in $300M deal
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Why is Nidec stock plunging today?
- Nidec Corp shares slump after auditor declines to sign off on earnings
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Track Guidance Changes Across a Coverage List With AI
- Stop Treating AI Like a Chatbot: What Are Agents, SubAgents, MCP, and Skills, and How Do They Actually Work?