
XPENG Launches Its Next-Gen AI Flagship SUV G9L in China, with Global Launch Set for Oct 12 at the Paris Motor Show
Source: PR Newswire
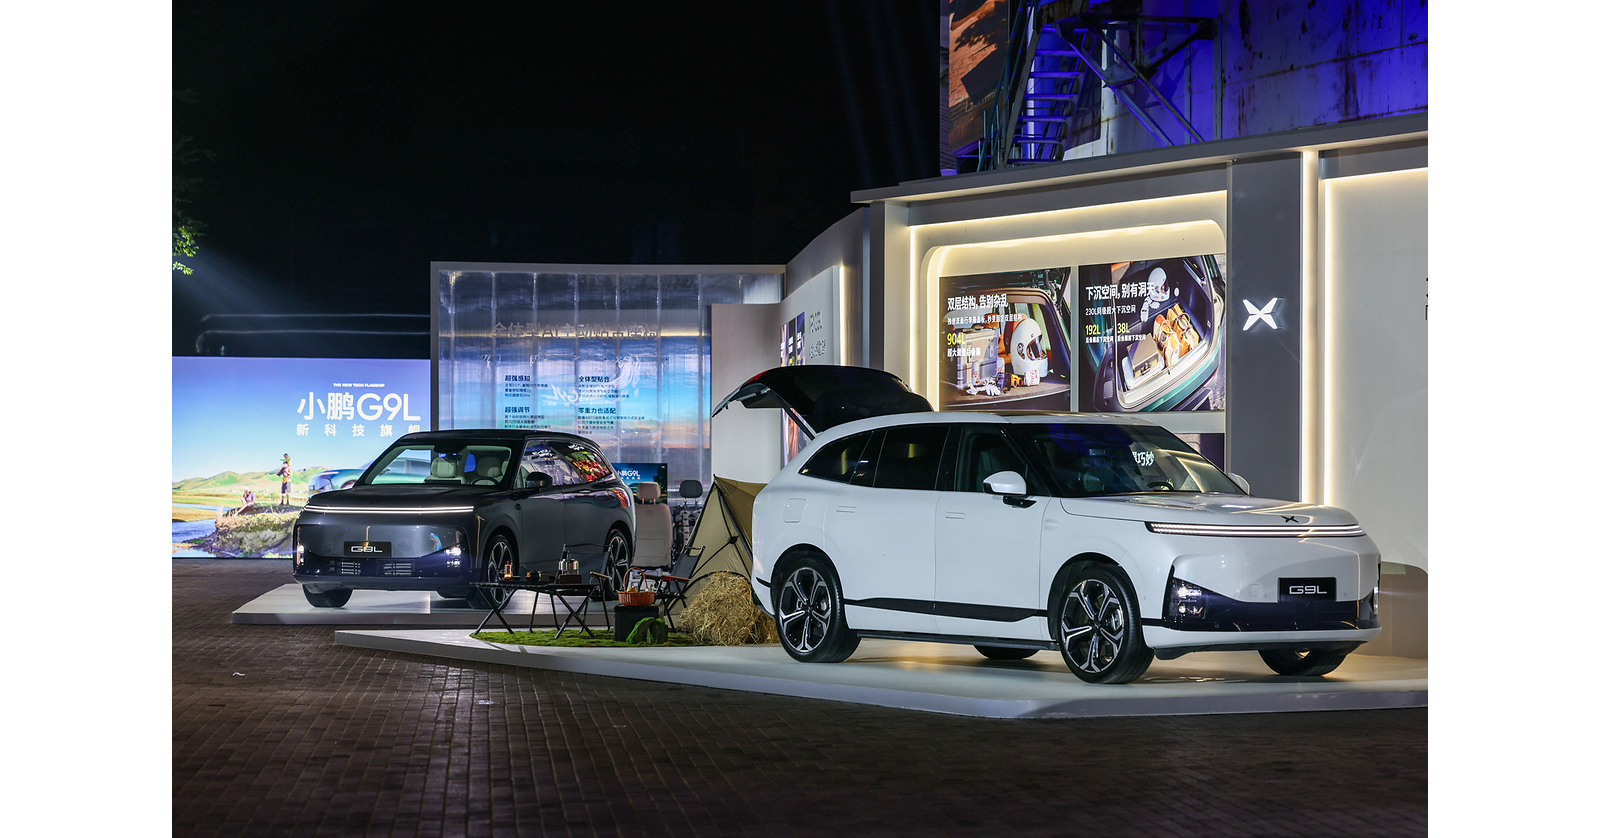
XPENG launched its next-generation G9L AI flagship SUV in China and plans an October 12 global debut at the Paris Motor Show, targeting availability in 64 markets. The BEV and REEV model will be XPENG's fourth vehicle produced at Magna's Graz, Austria plant, extending localized European production following the G6, G9 and P7+. XPENG highlights VLA 2.0 autonomous-driving capabilities, its Turing AI chip, 192 crash tests across four major safety protocols, and more than 6.74 million km of global road testing.
Analysis
The investment relevance is not the launch itself but whether XPENG can convert a broad platform rollout into higher factory utilization and lower unit software/R&D burden. A dual-powertrain flagship expands its addressable market beyond pure-BEV buyers, putting the most direct competitive pressure on LI in China’s premium family-SUV segment and on BYD/Geely-owned premium brands in export markets. If volumes scale, XPENG’s proprietary compute/software stack could support gross-margin improvement through feature reuse across vehicles; absent scale, the same AI and localization spend is a fixed-cost drag.
European assembly creates a potential strategic advantage only if local production meaningfully reduces landed-cost volatility, tariff exposure, or delivery lead times. Investors should not assume this outcome: the applicable EU origin rules, local-content thresholds, and Magna contract economics determine whether the setup is margin accretive or simply a higher-cost route to market. Magna (MGA) has a modest second-order utilization opportunity, but a single program is unlikely to move consolidated earnings without disclosed annual production volumes.
The Oct. 12 event is a near-term sentiment catalyst, but sustained rerating over the next 1-3 months requires independently verifiable order intake, European pricing, delivery timing, and gross-margin guidance. Consensus may be overvaluing the AI narrative relative to the harder question of residual values and incentive intensity: premium Chinese EV launches often generate early reservation headlines that do not translate into stable realized pricing. Over 6-18 months, success would validate XPENG as a global platform exporter; failure would reinforce that overseas expansion dilutes margins before it diversifies revenue.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Ticker Sentiment
Key Decisions for Investors
- Treat XPEV as a catalyst watch into Oct. 12 rather than a pre-event chase. Initiate a tactical long only if disclosed pricing/order data imply premium positioning without incremental incentives and management reiterates or raises automotive gross-margin guidance; target 10-15% upside over 1-3 months versus a 7% stop, with a guidance cut or weak initial delivery cadence as thesis failure.
- Run a small long XPEV / short LI pair for 1-3 months only after China order data demonstrate meaningful REEV mix. The mechanism is substitution in premium large-SUV demand; exit if LI maintains monthly delivery momentum and discounting remains contained, because LI’s brand and distribution advantage can overwhelm product-level competition.
- Monitor MGA, but do not establish a standalone position on this development. Upgrade to a long only if Magna discloses committed annual European volume, contract duration, and contribution margins sufficient to affect European utilization; without that data, the earnings sensitivity is too small and uncertain.
- Set alerts for EU rules-of-origin or tariff determinations and for XPEV’s first European delivery data. A determination that China-sourced components preserve punitive duty treatment, or evidence of elevated dealer incentives, would invalidate the localization-margin thesis and favor reducing any XPEV exposure.
More News
- Xpeng stock rises on plans to license tech to foreign automakers
- Italy to deploy warships to protect shipping through Bab al-Mandeb
- Oil prices fall for 3rd day as supply concerns ease, diplomacy in focus
- Saudi Pivots Oil Routes After Pipeline Attack
- Australia’s central bank chief warns inflation risks materialising
- Asian stocks rise as oil retreat eases inflation fears, BOJ in focus