
ESGAMING Launches Global Distributor Program at 2026 HK and Canton Fairs
Source: PR Newswire
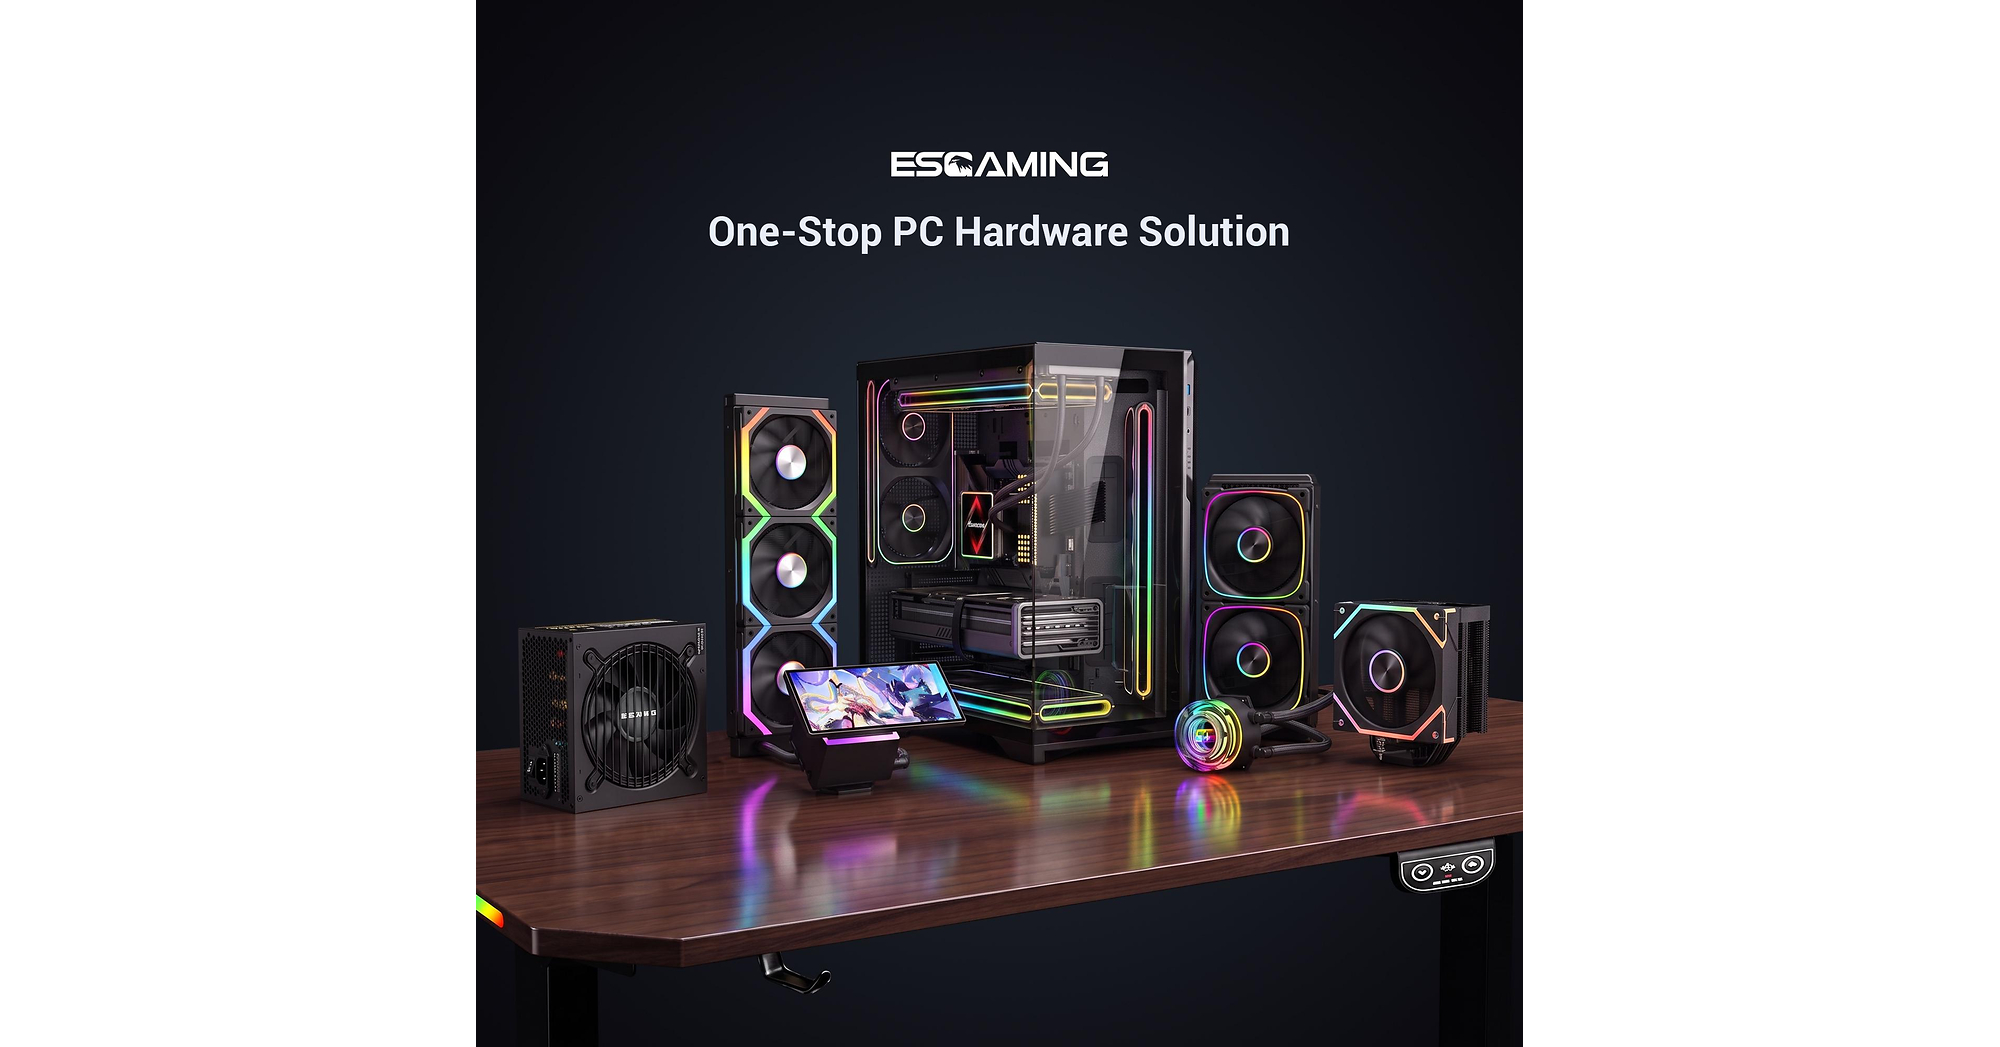
ESGAMING announced a Global Distributor Program rolled out alongside its participation in the 2026 Hong Kong Global Sources Consumer Electronics show (Oct 11–14) and the Canton Fair (Oct 15–19), aiming to expand hardware distribution across South America, the Middle East, Southeast Asia, and Africa. The launch spotlights its EdgeFlow gaming PC chassis, featuring a 60-degree angled mesh side panel for direct cold-air delivery to the GPU, a dual-chamber design, and support for up to 10 fans and 420mm liquid-cooling radiators. The firm also cites in-house scale of 6M PC cases, 4M power units, and 3M liquid coolers annually with a 98% first-pass yield, plus a stated 20–25 day standard shipping cycle.
Analysis
This reads more like channel positioning than a market event. The only real investable takeaway is that a low-cost, vertically integrated OEM is trying to take shelf space in price-sensitive emerging markets, which matters most to incumbents with weaker brand moats and higher logistics costs. If the distributor rollout is real, the second-order effect is margin pressure on mid-tier PC case/PSU/cooling vendors that depend on regional importers to defend ASPs; the product mix risk is greatest in LATAM, MENA, and Southeast Asia where buyers are less brand-loyal and more shipment-cycle sensitive.
For public comps, the most relevant implication is not top-line loss today but incremental discounting over the next 1-3 quarters if similar bundled sourcing models proliferate. That would be a headwind for Corsair (CRSR) and, to a lesser extent, other accessory/peripheral names exposed to channel inventory and promotional activity. The counterpoint is that this is still a private-company expansion story with no evidence of material scale in public filings, so the immediate tradable signal is weak and likely drowned out by broader PC demand and gaming refresh trends.
The contrarian view is that investors may over-interpret the brand launch and underweight execution risk: distributor programs often look expansive on paper but fail without local service density, spares, and marketing spend. The real falsifier is not the announcement but reorder data and channel checks over the next 2-4 quarters—if shipped volume doesn’t translate into visible share gains or if competitors keep ASP discipline, this is noise. If ESGAMING starts showing up in import data and reseller pricing, then the margin pressure thesis becomes actionable.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Key Decisions for Investors
- No immediate equity trade: treat this as a watch item unless channel checks show rising sell-through in LATAM/MEA over the next 1-2 quarters.
- If you want a downside hedge on emerging-market PC component pricing, consider a small tactical short in CRSR on strength into earnings, with a 1-2 quarter horizon and a stop if management re-accelerates gross margin or inventory normalizes faster than expected.
- Pair idea: long a broader hardware demand proxy, short CRSR, only if PC build demand stays firm but channel pricing weakens; thesis is mix/margin compression rather than industry volume collapse.
- Set an alert on CRSR gross margin and inventory turns for the next two earnings calls; a 100-150 bps margin miss or rising channel inventory would validate the competitive pressure thesis.
- Do not use public China hardware proxies here as a high-conviction long: this is a private-company distribution expansion, and without import/customs data the signal is too thin for a levered position.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- What's behind the sell-off in AI neocloud stocks like CoreWeave and Nebius
- AI Selloff Deepens in Asia as Funding Fears Mount
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Research Workflows, Report Format Selection, and Interactive Synthesis
- Can ChatGPT Analyze a 10-K? A Verification Workflow