
HiTHIUM Ranks TOP 2 Globally in Energy Storage Battery Shipments Again, Driven by Full-Chain Integrated Capabilities
Source: PR Newswire
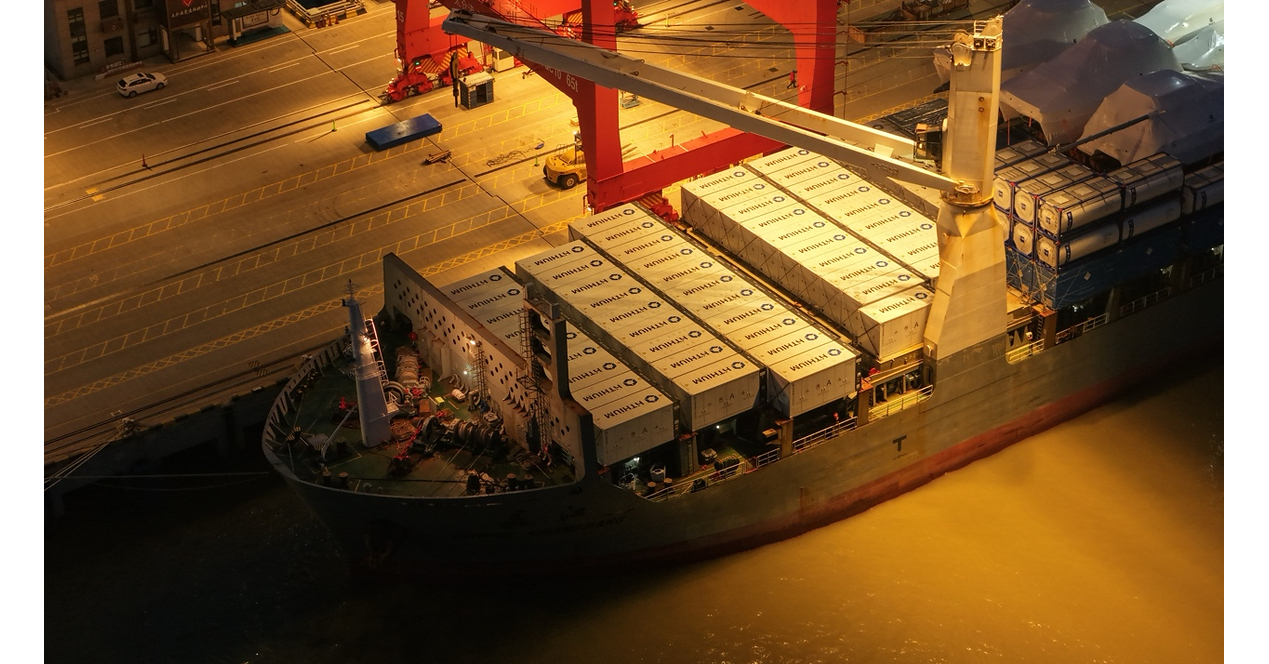
HiTHIUM says it ranked TOP 2 globally for energy storage battery shipments in 1H 2026, maintaining the position for a second consecutive year. The article cites total industry shipments of 467.84 GWh in 1H 2026 (+94.76% YoY), with HiTHIUM attributing its share to full-chain integrated capabilities and a focus on 4–8 hour long-duration energy storage (LDES). It also highlights ramp milestones including a “Lighthouse Factory” certification in Chongqing (Jan 2026) and entry into production rollout for an LDES industrial park in Heze, Shandong (Aug 2026), plus Texas and Spain facilities progressing.
Analysis
This reads more as a pricing and competitive-intensity signal than a standalone earnings catalyst. In storage, scale plus localized manufacturing usually translates into lower delivered cost and better financing terms, which tends to compress margins at smaller Western integrators before it shows up in market-share data. The first place to look is not demand, but whether public peers can hold ASPs and gross margin while the supply base keeps expanding.
The second-order winner is the buyer of storage, not necessarily the seller: utilities, IPPs, and data-center power developers can lock in cheaper capex per installed MWh, improving project IRRs and accelerating deployment. That is constructive for balance-sheet-heavy names that can warehouse projects, while it is bearish for asset-light vendors whose only edge is software or channel access. The most vulnerable are firms without local manufacturing or differentiated chemistry, because they have the least pricing power when customers can dual-source.
Near term, the market may overreact to shipment rankings that are backward-looking and do not tell us anything about profitability or warranty risk. Over 1-3 months, watch for tariff/local-content headlines and for any evidence that US or EU procurement shifts to non-China supply chains; that would blunt the competitive message. Over 6-18 months, the real thesis is that long-duration storage becomes cheaper and more bankable, but the upside accrues more to project owners and grid assets than to commodity-like battery vendors.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate broad-sector trade on the press release alone; treat it as a watch item until public comps show through in backlog, ASPs, and gross margin.
- Relative value idea: long NEE / short FLNC over the next 1-3 months. Thesis: cheaper storage improves utility project economics, while storage integrators face the first-order margin squeeze from a more crowded supply base. Invalidate if FLNC prints sustained backlog growth with stable or expanding gross margin.
- If we want a cleaner expression of pricing pressure, buy 3-6 month FLNC put spreads on any rally into earnings. Risk/reward improves if management signals lower pricing or weaker mix; cut if the stock re-rates on evidence of durable local-market share or policy support.
- Set an alert on TSLA energy gross margin and storage backlog rather than trading TSLA outright. If the company can keep margins stable while the category scales, it would be a relative winner; if not, the market is likely underestimating commoditization risk in utility-scale batteries.
More News
- One Singapore ship was sunk, but here's why others are still transiting the Strait of Hormuz
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- BOE Chief Says Energy Shock Delays 2% Inflation Target
- FDA approves Enspryng for thyroid eye disease treatment