
Haier Showcases AI-Powered Smart Home Ecosystem at IFA 2026
Source: PR Newswire
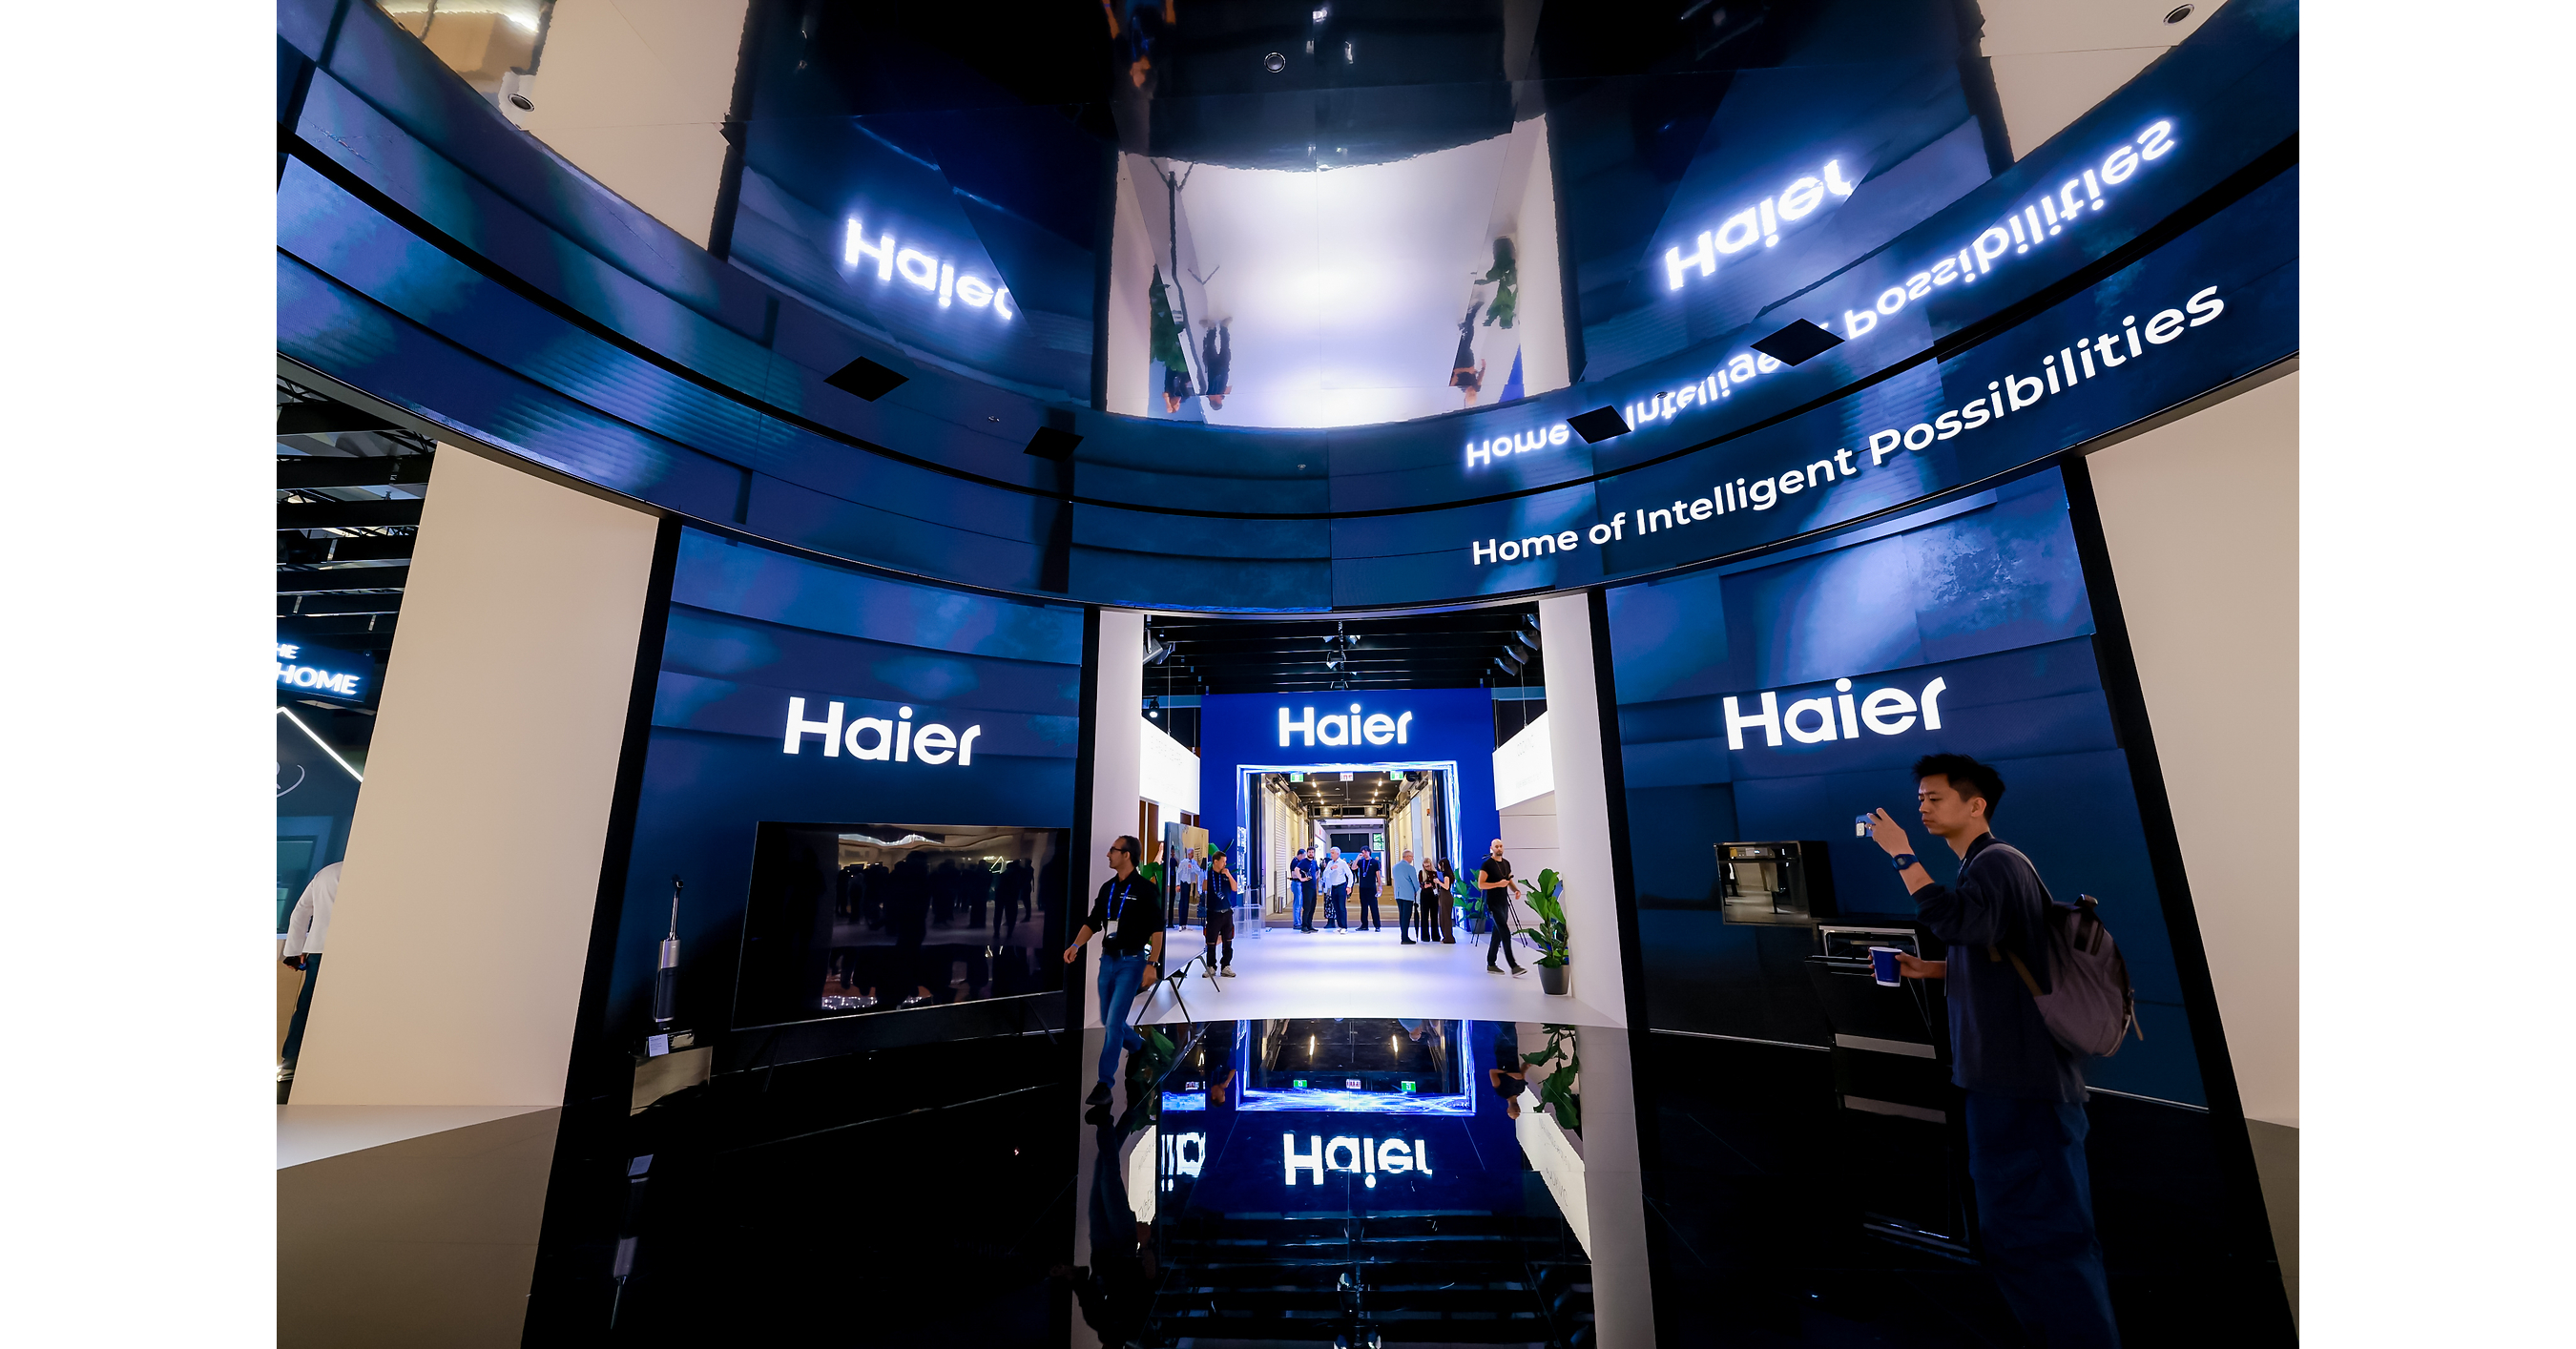
Haier showcased an AI-powered smart home ecosystem at IFA 2026, extending connected appliances into a coordinated system that senses conditions, learns routines, and automatically adjusts operations (e.g., Vision 15 laundry load/foam detection, Maestro fridge AI food care, and ID Ultimate 6 oven stop-on-result). The company highlighted scale—130M+ registered smart home users and 86.1B smart scene interactions in 2025—and plans to invest at least €13B over the next five years in AI, semiconductors, and IoT security. Overall this is a promotional product/tech rollout with incremental near-term market relevance, but supportive of Haier’s longer-term AI-native transformation.
Analysis
This is more credible as a branding and mix-upgrade event than an immediate earnings catalyst. In appliances, “AI” only matters financially if it lifts ASPs, lowers warranty/service costs, or creates repeat-touch revenue; otherwise it is mostly a marketing wrapper on a mature category. The near-term read-through is modestly positive for HSHCY because it can defend share at the premium end, but the bigger implication is that the industry is moving into a feature arms race where software, sensors, and ecosystem integration become table stakes.
The second-order winner set is broader than the stock itself: sensor, embedded compute, connectivity, and IoT-security suppliers should benefit more cleanly than appliance OEMs, because hardware makers will likely absorb most of the incremental R&D and localization cost while component vendors capture content expansion. The likely losers are legacy white-goods peers with weaker digital ecosystems and less ability to fund five-year platform investments; their risk is not immediate demand loss, but margin compression as they either match features or cede premium mix. For HSHCY, the key question is whether this supports a higher multiple or merely higher capex.
The contrarian view is that the market may be overestimating monetization. Consumers buy appliances on reliability, price, and energy efficiency; AI features rarely change replacement cycles enough to move the top line in the next 1-3 quarters. The risk is that the investment burden lands now, while the payoff is delayed 6-18 months and may never show up in operating margins if the features do not improve retention or service economics. What would falsify a bullish view is no evidence of gross-margin lift, no improvement in premium mix, or a follow-on disclosure that the ecosystem requires materially higher opex/capex than peers without share gains.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.20
Ticker Sentiment
Key Decisions for Investors
- Small tactical long HSHCY vs. short WHR for 1-3 months: play relative premiumization and AI narrative outperformance, but size modestly because the fundamental monetization is unproven; cut if HSHCY underperforms WHR by ~5-7% after the next earnings/consumer-channel update.
- Treat HSHCY as a watchlist long only on evidence of margin translation: look for 50-100 bps gross margin expansion or a clear increase in premium SKU mix over the next 2 quarters; absent that, do not chase the headline.
- Long component-enablers rather than OEMs if the thesis is AI appliance penetration: favor semiconductor/IoT-security exposure over appliance names, since content per unit is more direct and less cyclical; confirm with supplier disclosures before adding risk.
- Avoid paying up for the stock on the IFA event alone; the trade only works if channel sell-through, not just press coverage, shows up in the next 1-3 monthly data points. Set an alert for any guidance revision that raises capex faster than operating profit.
- If you want a cleaner contrarian pair, short the least differentiated global appliance incumbent against HSHCY on a 6-12 month view; the thesis breaks if the incumbent launches comparable software features or if HSHCY discloses materially higher investment without share gains.
More News
- Copper is outshining gold this year. Investors say the rally can survive an AI correction
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Volkswagen bet on Xpeng to save its China business. It’s not going to plan
- Gartner analyst behind tech rout: AI returns are not yet large enough to justify neocloud build-out
- Asia stocks slump as AI jitters hammer Korean chipmakers ahead of tech earnings