
REJURAN® COSMETICS Brings K-Beauty to LAFC Korean Heritage Night as Proud Skincare Partner
Source: PR Newswire
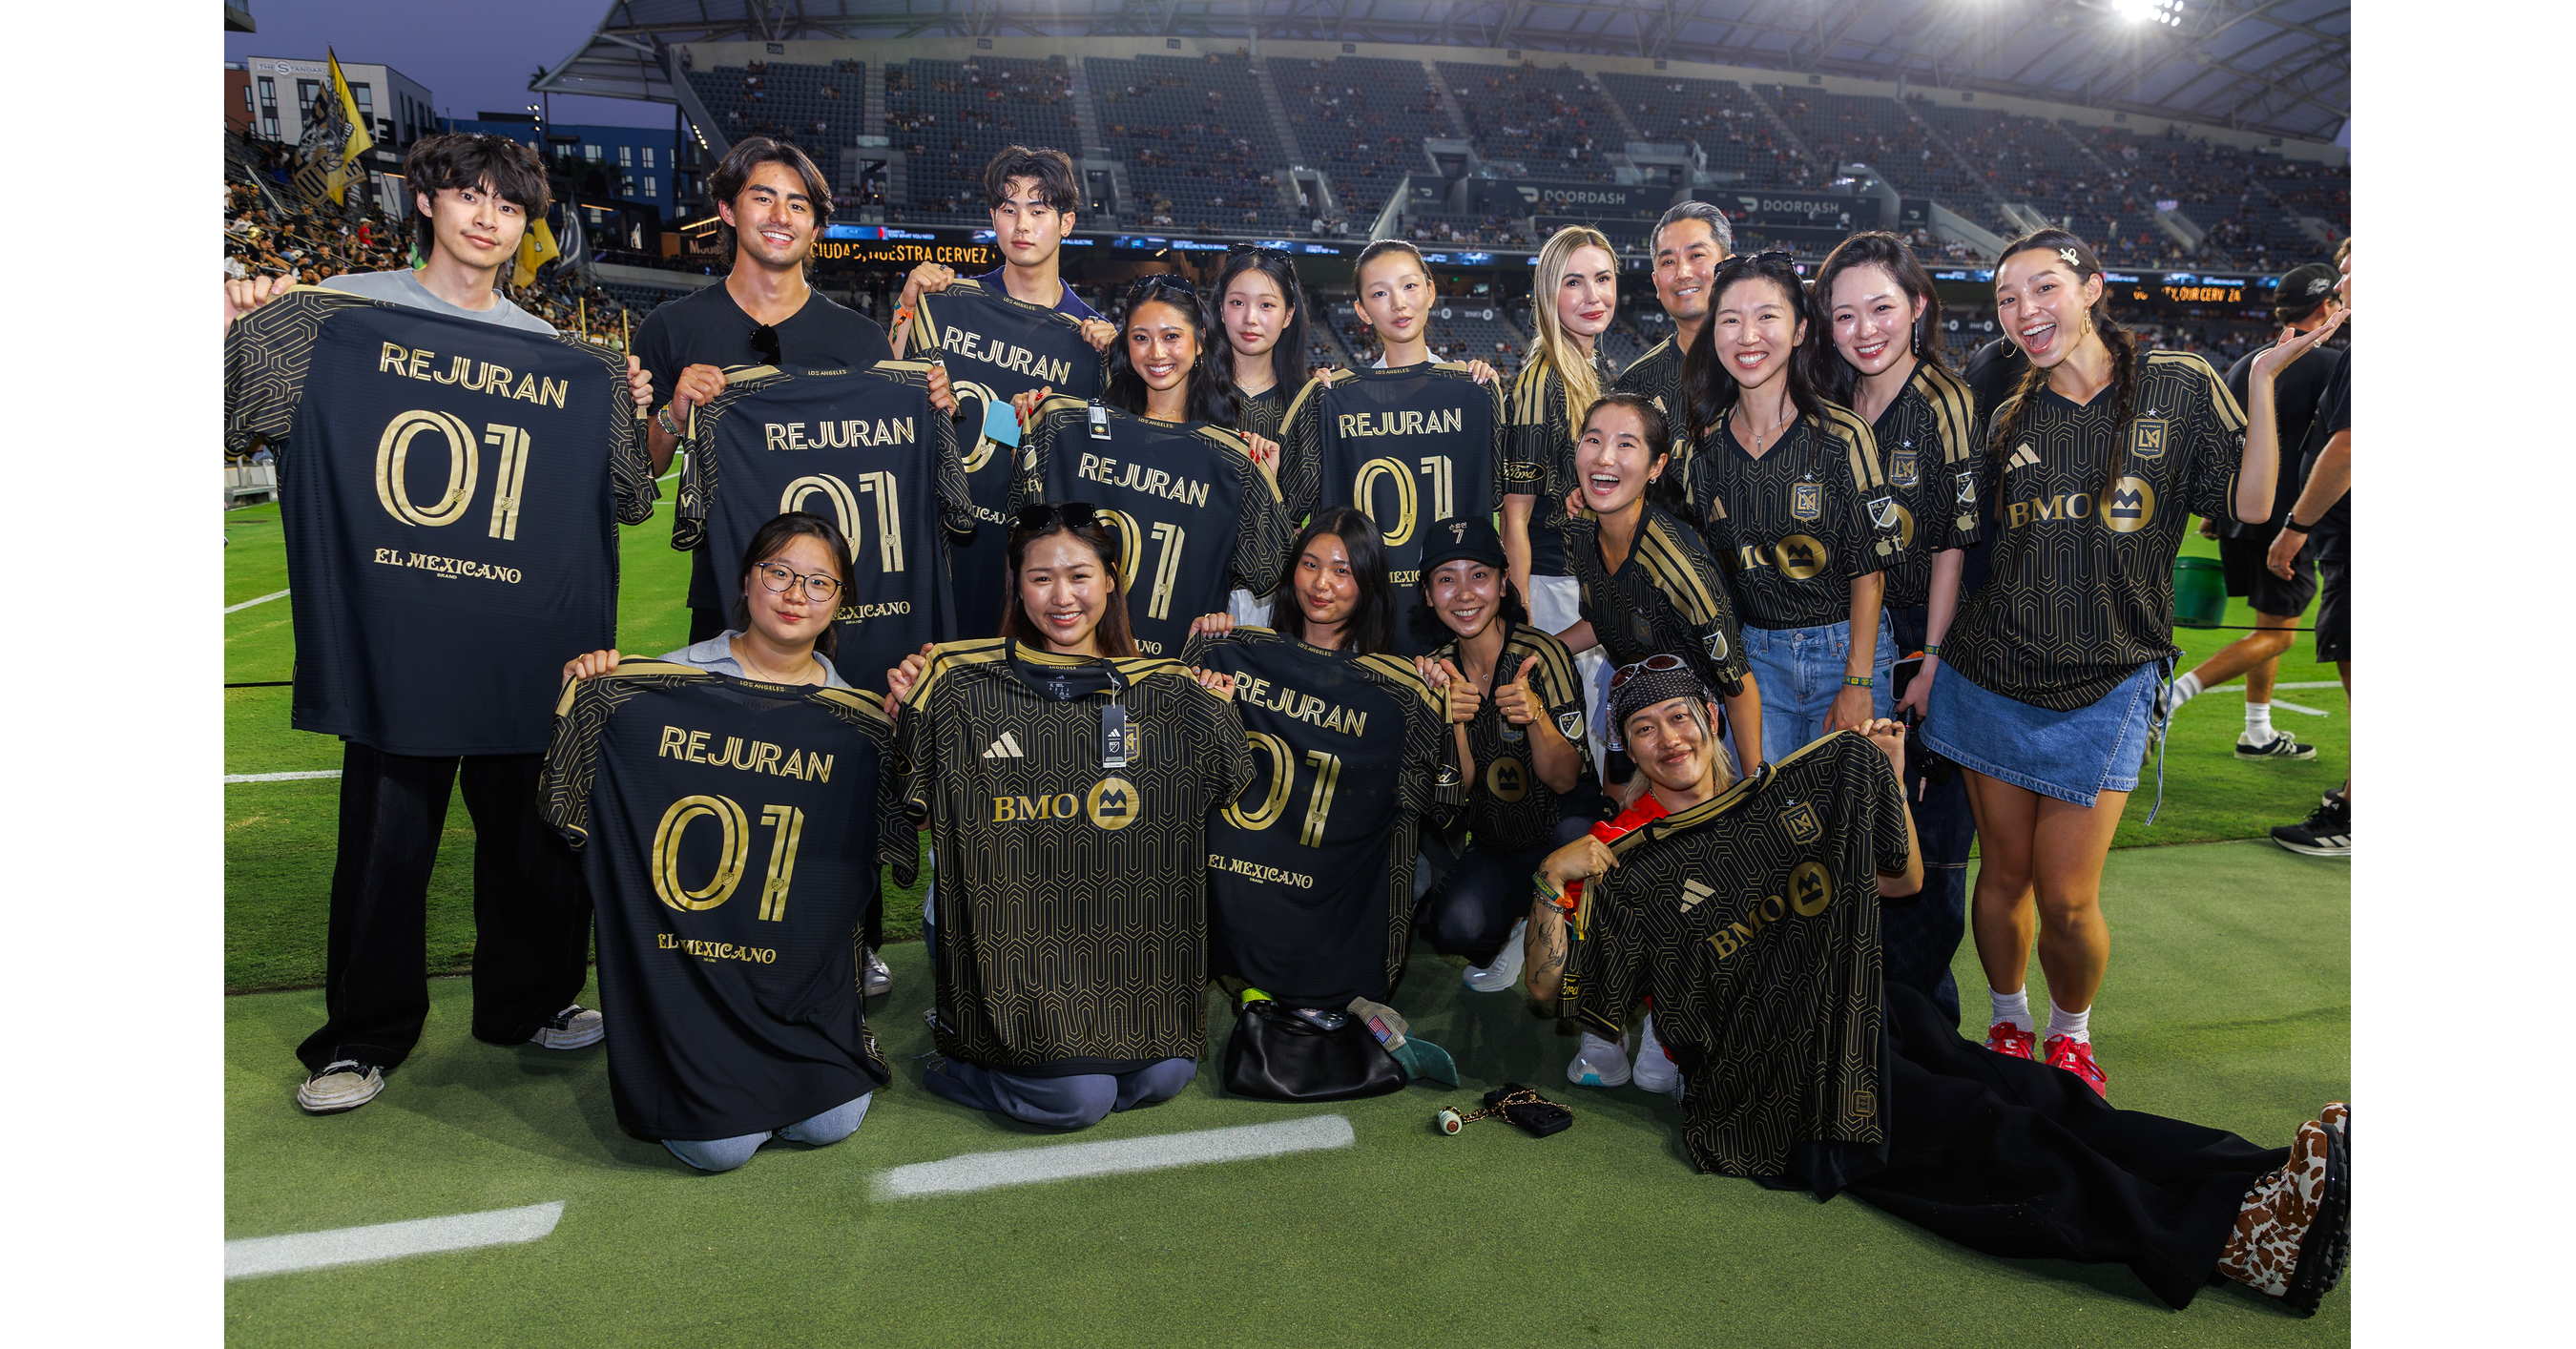
REJURAN COSMETICS used LAFC's Korean Heritage Night to expand K-beauty brand awareness, distributing approximately 10,000 5ml Turnover Ampoule samples and hosting creator experiences at BMO Stadium. The activation supports PharmaResearch's North American expansion, following a rollout across all 148 Sephora Canada stores and a planned acquisition of California-based Cosmetic Group USA to bolster local manufacturing and supply capabilities. The announcement is a positive consumer-marketing update but is unlikely to materially affect broader markets.
Analysis
This is not independently investable news: a one-night experiential campaign and sample distribution provide no evidence of repeat purchase, retailer sell-through, customer-acquisition cost, or incremental gross margin. The relevant underwriting question is whether North American expansion converts into recurring shelf productivity before local manufacturing investment adds fixed costs; until then, the event is marketing spend rather than a revenue catalyst.
The more consequential second-order issue is competitive intensity in prestige skincare. Korean brands can gain awareness efficiently through cultural distribution, but Sephora-style retail expansion typically shifts bargaining power to the retailer through promotional allowances, returns, and inventory commitments. That dynamic favors scaled incumbents with established U.S. logistics and marketing budgets—L'Oréal (OR.PA), Estée Lauder (EL), and e.l.f. Beauty (ELF)—unless REJURAN demonstrates differentiated clinical efficacy that supports premium pricing and lower promotional dependence.
Over the next 1-3 months, monitor Canadian retail velocity, replenishment orders, and evidence that the planned U.S. manufacturing acquisition closes on acceptable terms. Over 6-18 months, local production could improve lead times and tariffs/logistics resilience, but only if capacity utilization rises; an underutilized acquisition would dilute margins. The bullish thesis is falsified by weak retailer reorder data, rising promotional intensity, or acquisition consideration implying an excessive multiple relative to achievable North American sales.
Contrarian view: broad "K-beauty" enthusiasm can obscure category saturation. Sports-led sampling may reach consumers outside the core skincare buyer, but conversion rates from free 5ml samples are likely low absent a measurable CRM capture and retail redemption funnel. No listed security or disclosed financial metric supports a directional trade today.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No immediate position: treat as a watch item rather than a catalyst trade; require verified Sephora Canada sell-through/reorder data and disclosed U.S. revenue contribution before underwriting growth.
- For prestige-beauty exposure over 6-12 months, prefer diversified scale in OR.PA over a thematic K-beauty read-through; reassess if REJURAN's U.S. expansion shows sustained premium-price velocity rather than sampling-led awareness.
- Monitor EL and ELF earnings for category read-through: accelerating K-beauty shelf allocation or promotional pressure would be a negative margin signal for incumbents, but this activation alone does not justify a short.
- Set an event alert around the CG USA transaction: valuation, assumed liabilities, manufacturing utilization targets, and closing conditions are needed to determine whether the acquisition is margin accretive or a fixed-cost burden.
More News
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns
- China’s tech darlings are losing their shine. Here’s what’s behind the sell-off
- Google's Gemini 4 Carbon looks like a diamond in the rough
- Aker BP Q3 profit tops forecast on $870 million writedown reversal
- GE Vernova shares slip despite a beat-and-raise. What the sellers are getting wrong