
Niutech Completes Group Restructuring to Advance Tire and Plastic Chemical Recycling
Source: PR Newswire
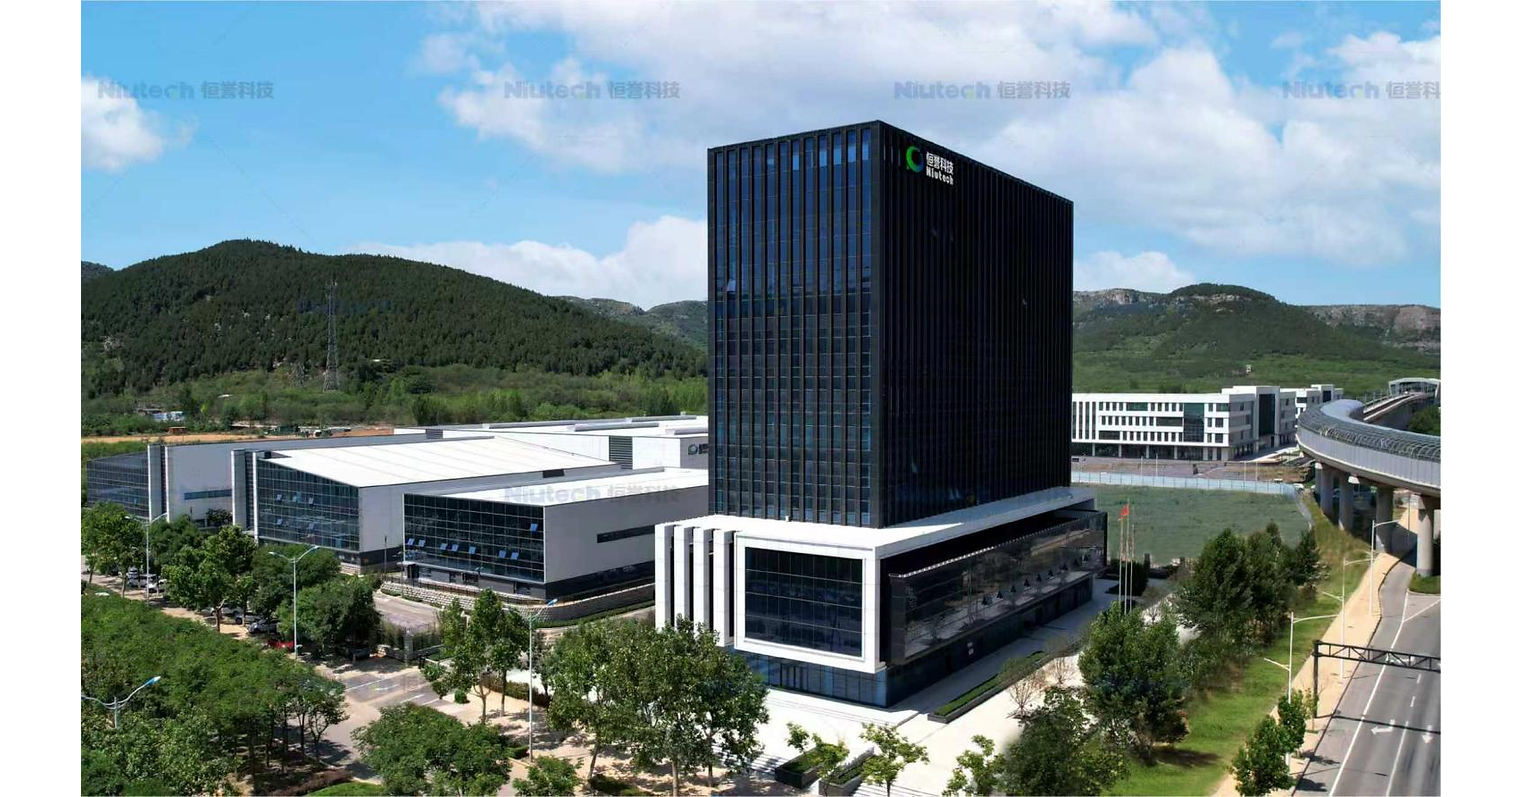
Niutech completed its group restructuring on August 26, 2026 and is scaling its continuous pyrolysis platform for tire and plastic recycling. Its new line processes more than 100 tonnes per day per unit, while majority-owned Hesheng Environmental Protection launched a 100,000-tonne Phase II project that increases total capacity to 160,000 tonnes annually. A UK customer placed a RMB198 million order following project and technology evaluations, while Niutech is extending R&D into sustainable aviation fuel and alternative-energy applications.
Analysis
The investable read-through is not the restructuring itself but whether continuous pyrolysis can move recycled carbon black and plastic-derived oil from low-value fuel substitution into certified chemical feedstock. That upgrade shifts economics from waste-gate-fee dependence toward spreads linked to virgin carbon black, naphtha and compliance-credit markets; it is incrementally disruptive to conventional carbon-black suppliers such as Cabot (CBT) and Orion (OEC) only if product qualification by tire makers is sustained. Near term, the listed Chinese parent, 688309, remains a project-order and execution story rather than a proven recurring consumables franchise, so a single overseas equipment order should not justify a material rerating without backlog, gross-margin and cash-conversion disclosure.
European recycled-content mandates create a 6-18 month demand tailwind for qualified feedstock, but the bottleneck is likely permitting, traceability certification and offtake contracts rather than reactor capacity. Tire producers Michelin (ML.PA), Continental (CON.DE), Bridgestone (5108.JP) and Pirelli (PIRC.MI) could gain optionality from reliable recovered-carbon-black supply, while waste operators with collection networks—Veolia (VIE.PA) and Renewi (RWI.L)—may hold more durable negotiating leverage than equipment vendors. The second-order risk is that low oil/naphtha prices compress chemical-recycling economics and force output toward lower-value fuel markets, weakening returns despite favorable regulation.
Consensus may overvalue headline throughput: mixed-plastic input claims are commercially meaningful only if yields, contaminant tolerance, energy intensity and mass-balance certification hold at customer sites. Over the next 1-3 months, monitor independently disclosed order backlog, customer acceptance testing, operating uptime and receivables; over 6-18 months, monitor contracted offtake and EBITDA per tonne. The thesis is falsified by delayed European commissioning, inability to secure ISCC-plus/mass-balance customer qualification, or sustained virgin-feedstock prices that erase the recycled-product premium.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- No immediate directional position in 688309: treat this as an alert until the next results disclose backlog, revenue recognition, project gross margin and operating cash flow. Reassess for a long only if overseas orders convert into multi-project backlog with stable margins rather than one-off equipment sales.
- Build a 6-12 month watchlist long in Veolia (VIE.PA) or Renewi (RWI.L) versus a short basket of pure equipment exposure only after permitting and feedstock contracts are visible; collection control should capture value if recycled-content compliance tightens. Exit if EU implementation is diluted or gate-fee economics deteriorate materially.
- For a liquid competitive hedge, monitor a long CBT/OEC pair against European tire manufacturers rather than shorting carbon-black producers outright. Initiate only if verified recovered-carbon-black qualification begins displacing virgin volumes; absent that evidence, incumbents retain pricing power and the disruption thesis is premature.
- Set alerts on Brent/naphtha and European recycled-polymer spreads over the next two quarters: a sharp decline in virgin-feedstock prices is a downside catalyst for chemical-recycling project returns and would argue against adding exposure to the theme.
More News
- South Korea’s exports hit record high on AI boom
- US judge approves settlement allowing Paramount to acquire Warner Bros
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
- Tencent leases 100,000 chips from Oracle for $7 bln- FT
- Greer urges G20 to back Trump tariff agenda, takes aim at China
- Paramount Skydance prices $42 billion debt for Warner Bros deal
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Search Earnings Call Transcripts With AI
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI