
Skyven Arcturus Heat Pump Achieves COP of 8.0, Marking A New Level of Industrial Steam Efficiency
Source: PR Newswire
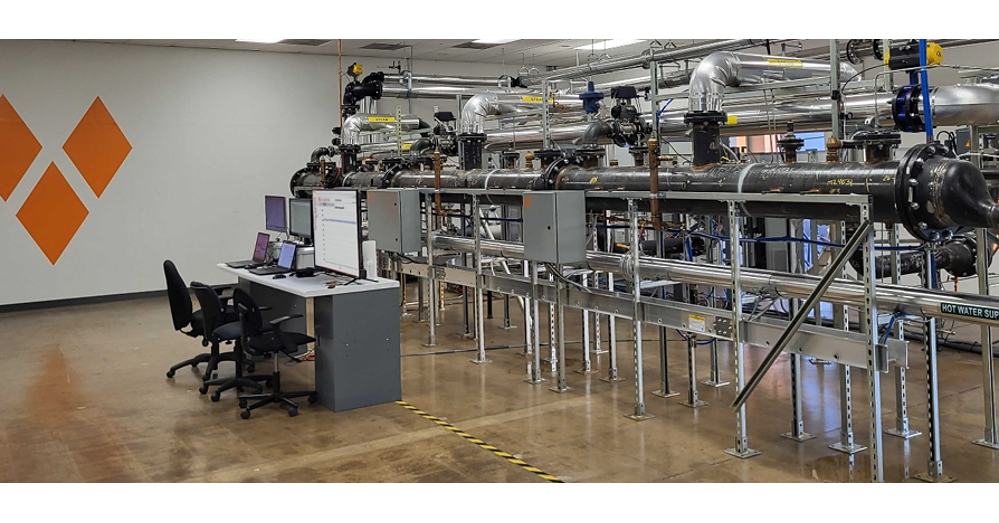
Skyven Technologies said its Arcturus industrial heat pump in Texas achieved a sustained COP of 8.0, up from 6.5 at commissioning—an improvement of 20%+ and above the stated roadmap target. At COP 8.0, it claims ~10x less energy per unit of steam versus conventional boilers, with steam lifts from 38°C to 185°C. The company links the efficiency to lower European steam costs and reduced exposure to EU ETS and natural-gas price volatility, but this is a technology milestone rather than a public earnings catalyst.
Analysis
This is more useful as a proof-of-technology signal than as an immediate revenue event. The economic implication is that high-temperature electrified steam is moving from “green pilot” to a plausible procurement decision for sites where power is reliable and carbon cost is material; that expands the addressable market for firms that can package electrification as an operating-expense swap rather than a capex project. The near-term market impact is still limited because adoption is gated by site integration, uptime, and contract structure, not by lab efficiency.
Second-order winners are the picks-and-shovels around electrification: controls, power electronics, grid interconnect, and energy-as-a-service financing. The losers are not boiler OEMs overnight, but rather the long-tail maintenance and replacement stream tied to gas-fired process heat; that erosion tends to show up slowly in order books before it shows up in earnings. In Europe, the tighter the gas-power spread and the higher the carbon price, the faster the payback math improves; cheap gas or softer ETS pricing would blunt the thesis quickly.
Contrarian take: the consensus will likely over-index on the headline efficiency number and underweight the operational risk of sustaining that performance in messy industrial environments. The real bottleneck is not thermodynamics but utilization, warranty risk, and whether customers can finance multi-year conversion projects with credible savings guarantees. If Skyven can convert this into third-party contracted volume, the signal matters; if not, it remains a strong demo with little public-market translation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No direct trade in ARCT/private exposure here; treat as a watch item only. Reassess after the first third-party commercial contract or backlog disclosure, not on demo headlines. Falsifier: no visible customer conversion within the next 2 quarters.
- Conditional relative-value idea: long XLU / short XLE over 6-12 months if industrial electrification gains traction and gas-demand erosion becomes visible in Europe. Risk/reward is modest but asymmetric if utilities see load growth while hydrocarbons face slow terminal-value compression.
- Accumulate EMR and ABB on pullbacks as second-order beneficiaries of industrial electrification controls and integration. The setup is better on weakness than on strength; the thesis breaks if industrial order flow fails to broaden beyond pilots.
More News
- Here are Friday's biggest analyst calls: Nvidia, SpaceX, Tesla, Apple, Mobileye, EchoStar, Toll Brothers & more
- Amid rising streaming subscription costs, here are 3 strategies CNBC staffers use to save
- Iran-backed Houthis strike Yemen’s Aden: What that means
- Christine Lagarde: IMFC Statement
- Palantir patient data tech rejected by many NHS trusts in England
- IMF urges support for poorer nations facing high inflation, war spillovers